Quick updates: Rubis, Fielmann, Auto Trader & Rightmove
As I was on vacation last week, here is a quick summary of some quarterly updates that were released last week for companies in my portfolio:
Rubis:
Rubis reported a Q3 trading update early last week. As to be expected, the numbers continued to be quite good.
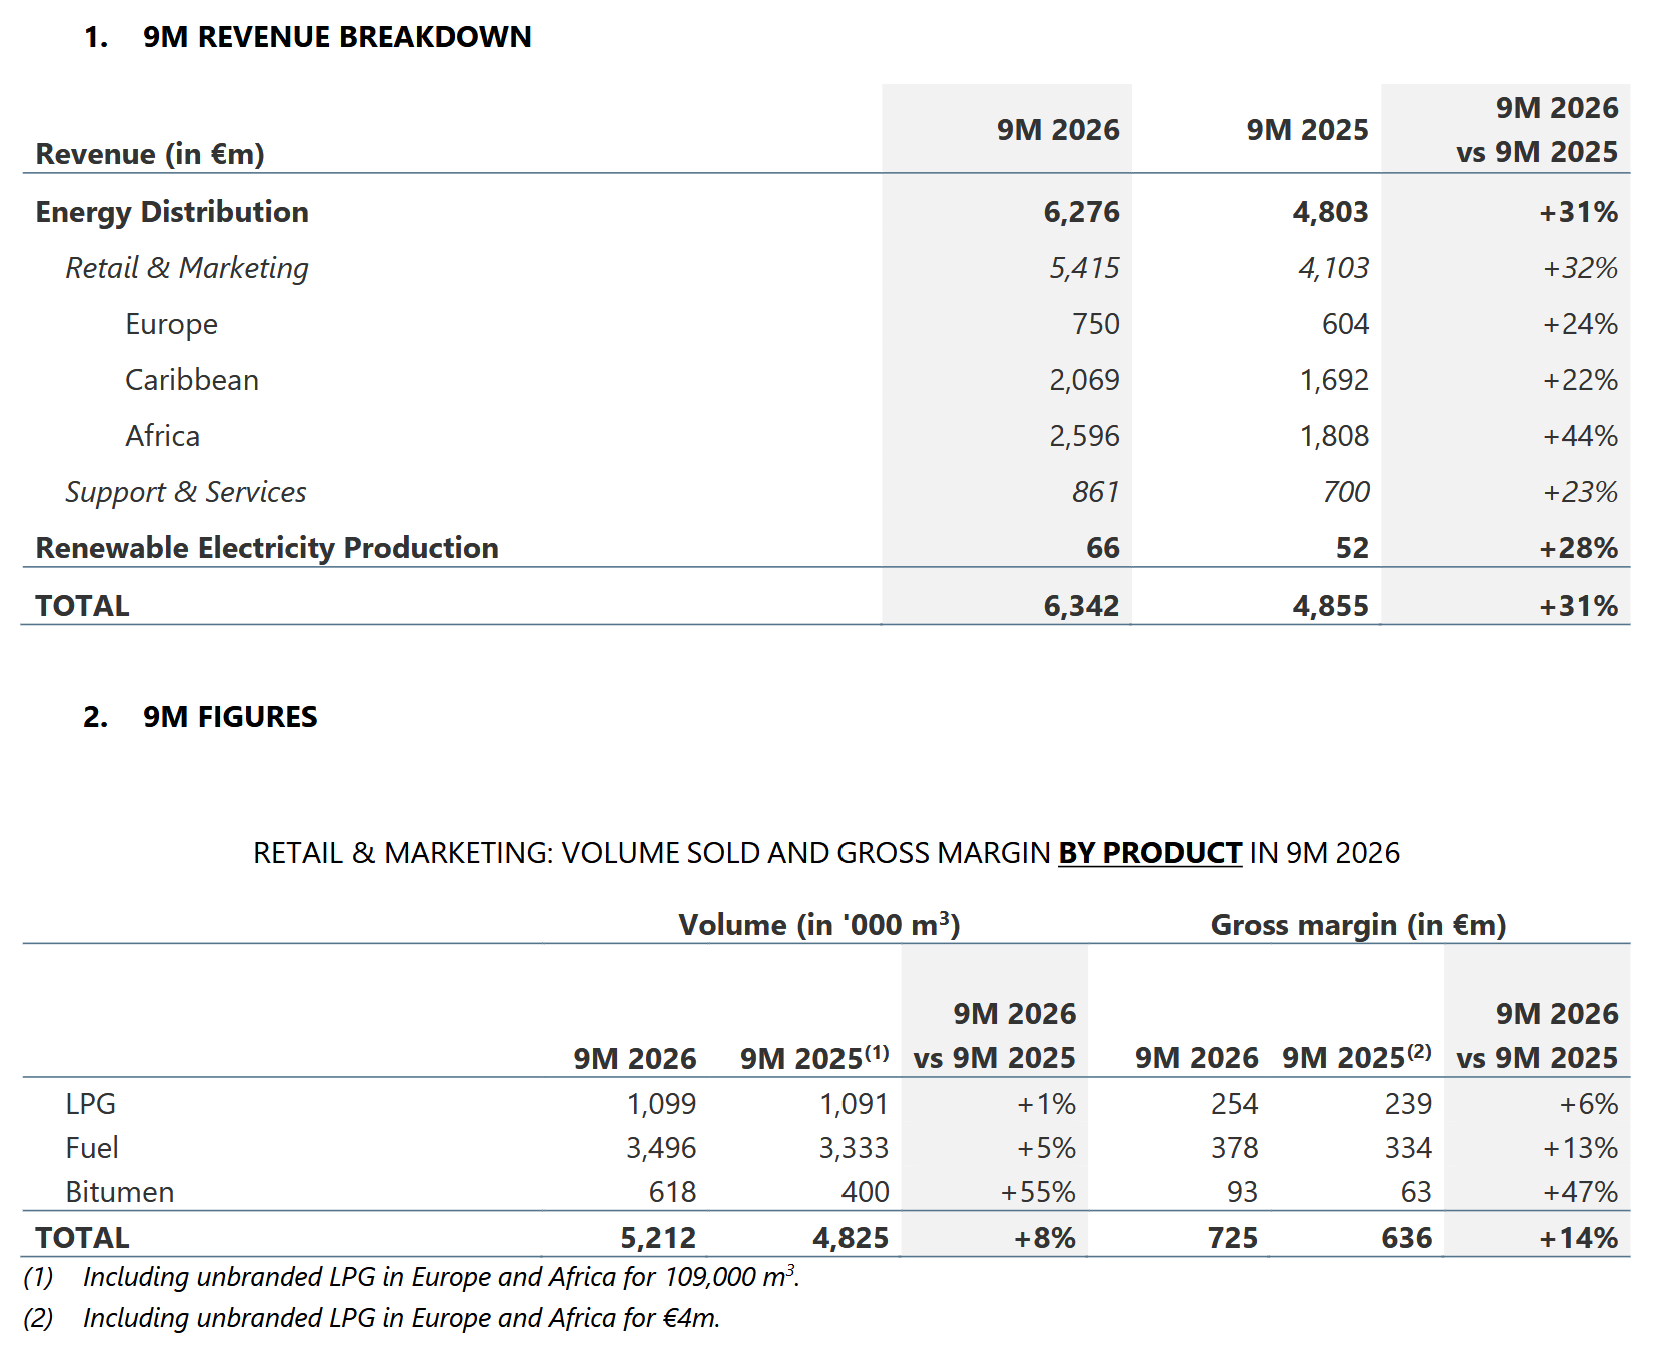
While revenue is influenced by the current oil prices, the more important numbers are volumes which are up +8% and Gross margins which are up +14%.
If we compare volumes and Gross margins with the 6M numbers, we can see that growth has decreased a tiny little bit:
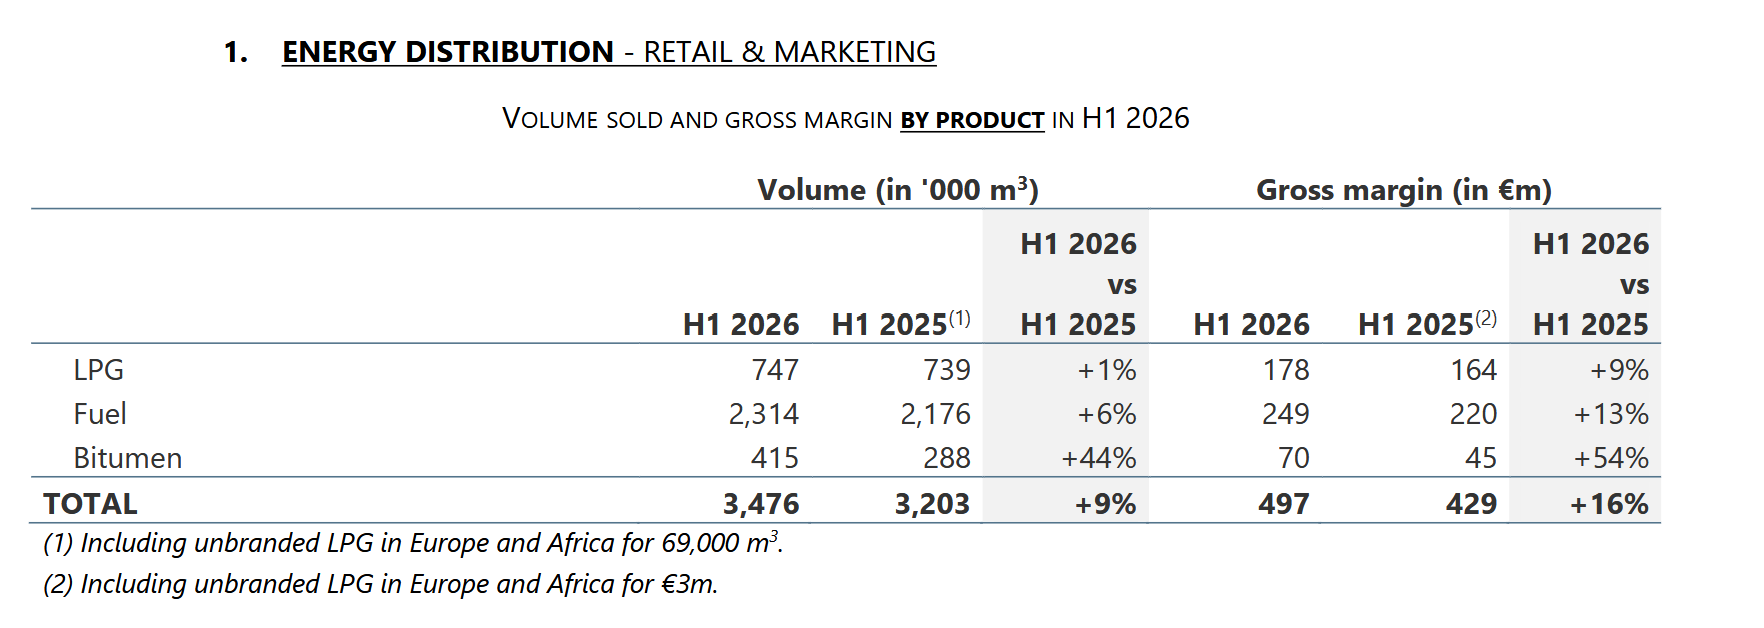
But Rubis has confirmed the increased guidance from mid year.
They have also published the full set of documents for the December 9th special Shareholder meeting, so it seems that this is going according to plan as well.
The “Governance Roadshow presentation” nicely summarizes the new Managment and Supervisory board structure and Management incentive plans.
So from my perspective, the Rubis case is developing according to plan.
Fielmann:
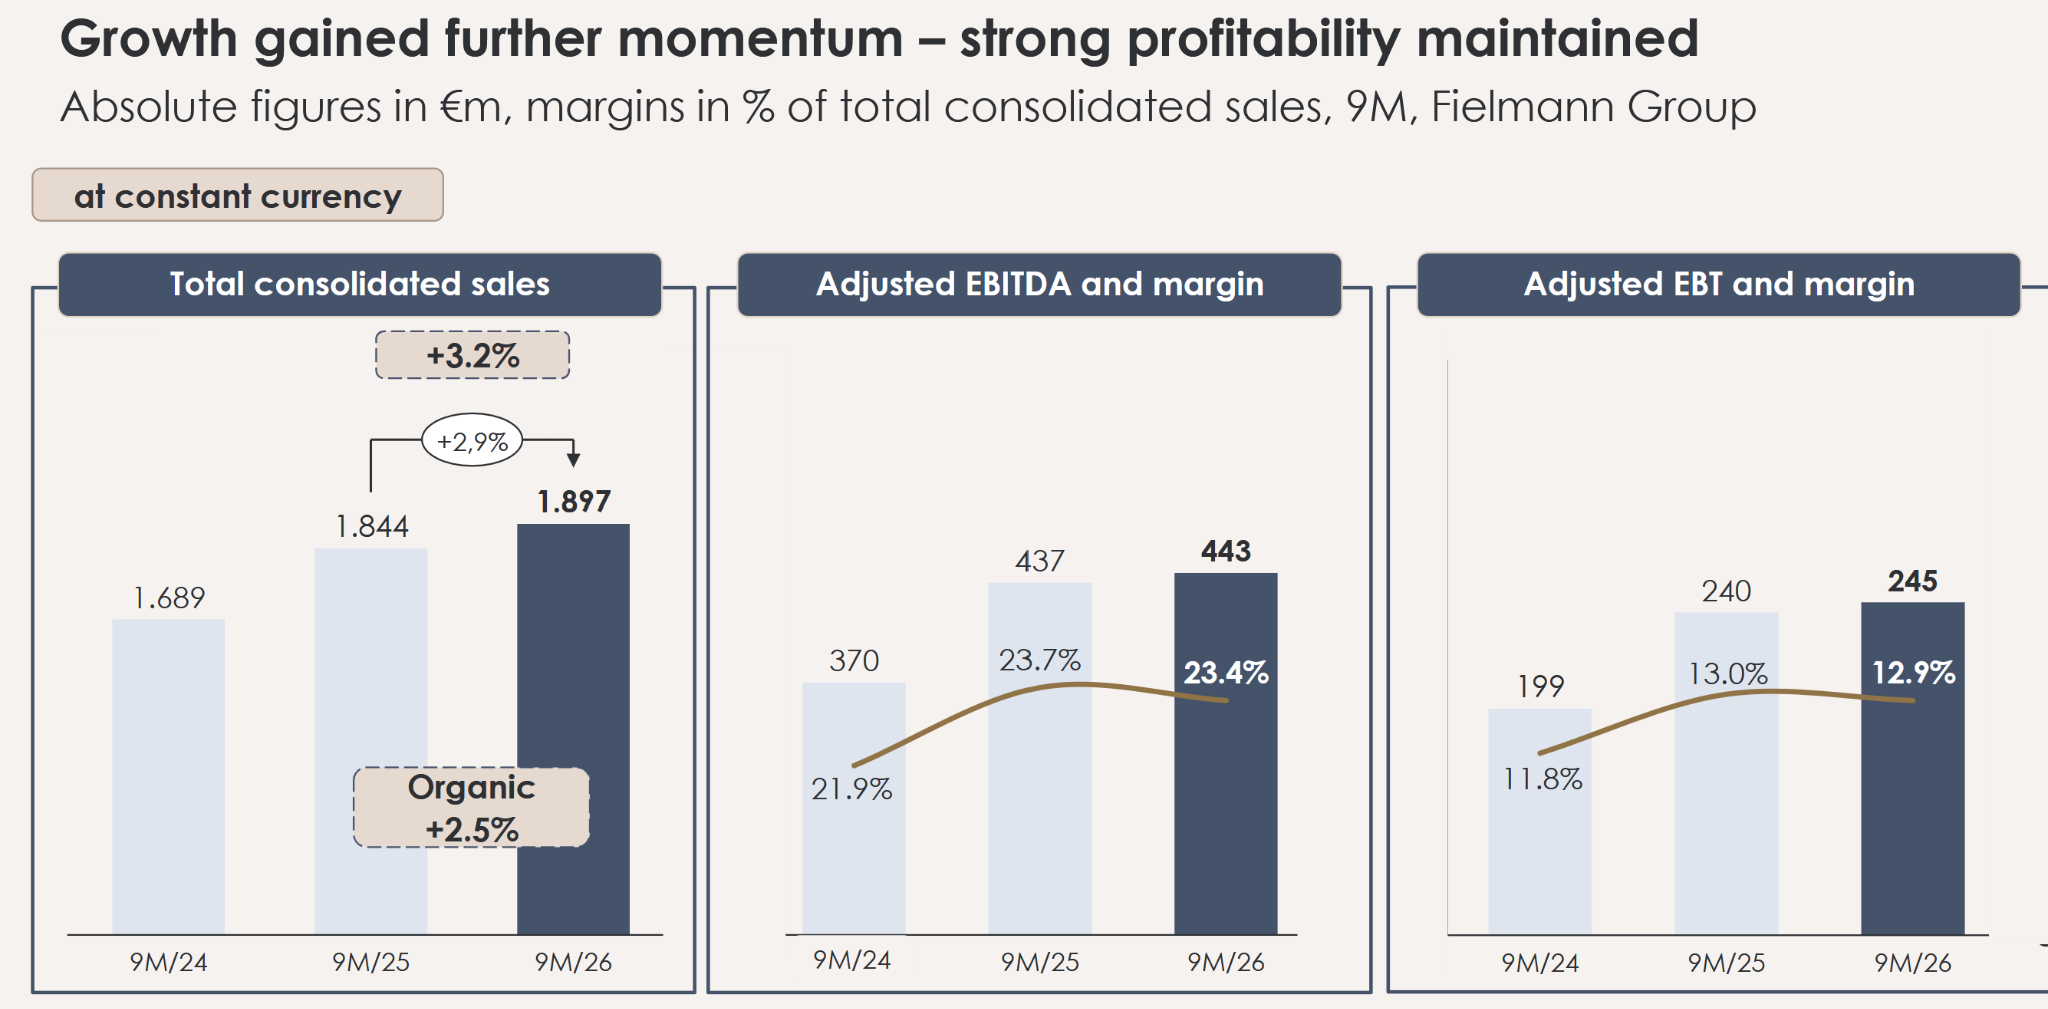
After EssilorLuxottica published decent Q3 numbers already in October, Fielmann came out with their Q3 numbers early last week.
Organic sales growth recovered from the low 6M numbers:
Interestingly, the Hearing aid products showed the largest growth, followed by Sunglasses:
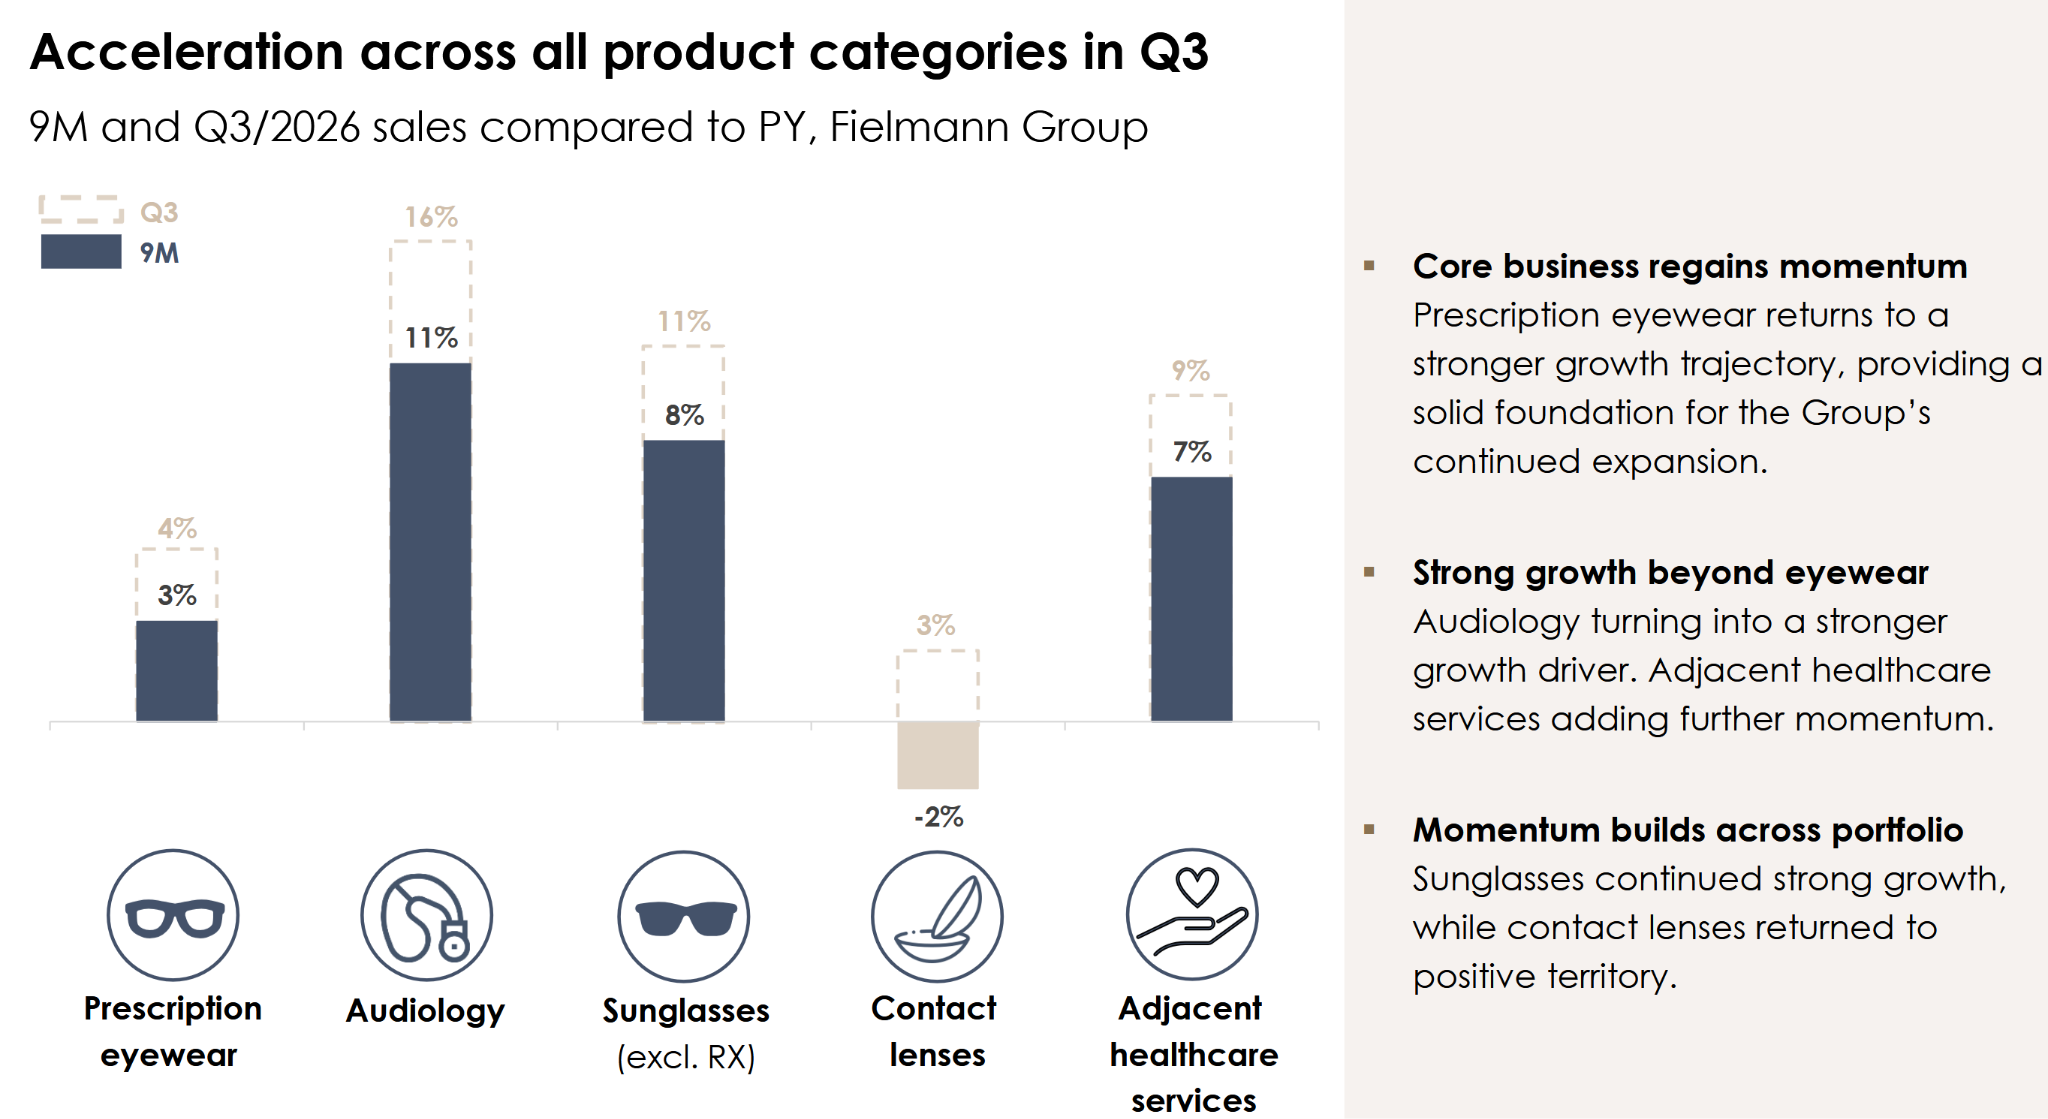
The only negative aspect here is that the US business didn’t grow and profitability declined as they are investing into new store concepts.
Filemann’s share price is now back to flat YTD while Essilor has still some way to go to reach the level from the beginning of the year:
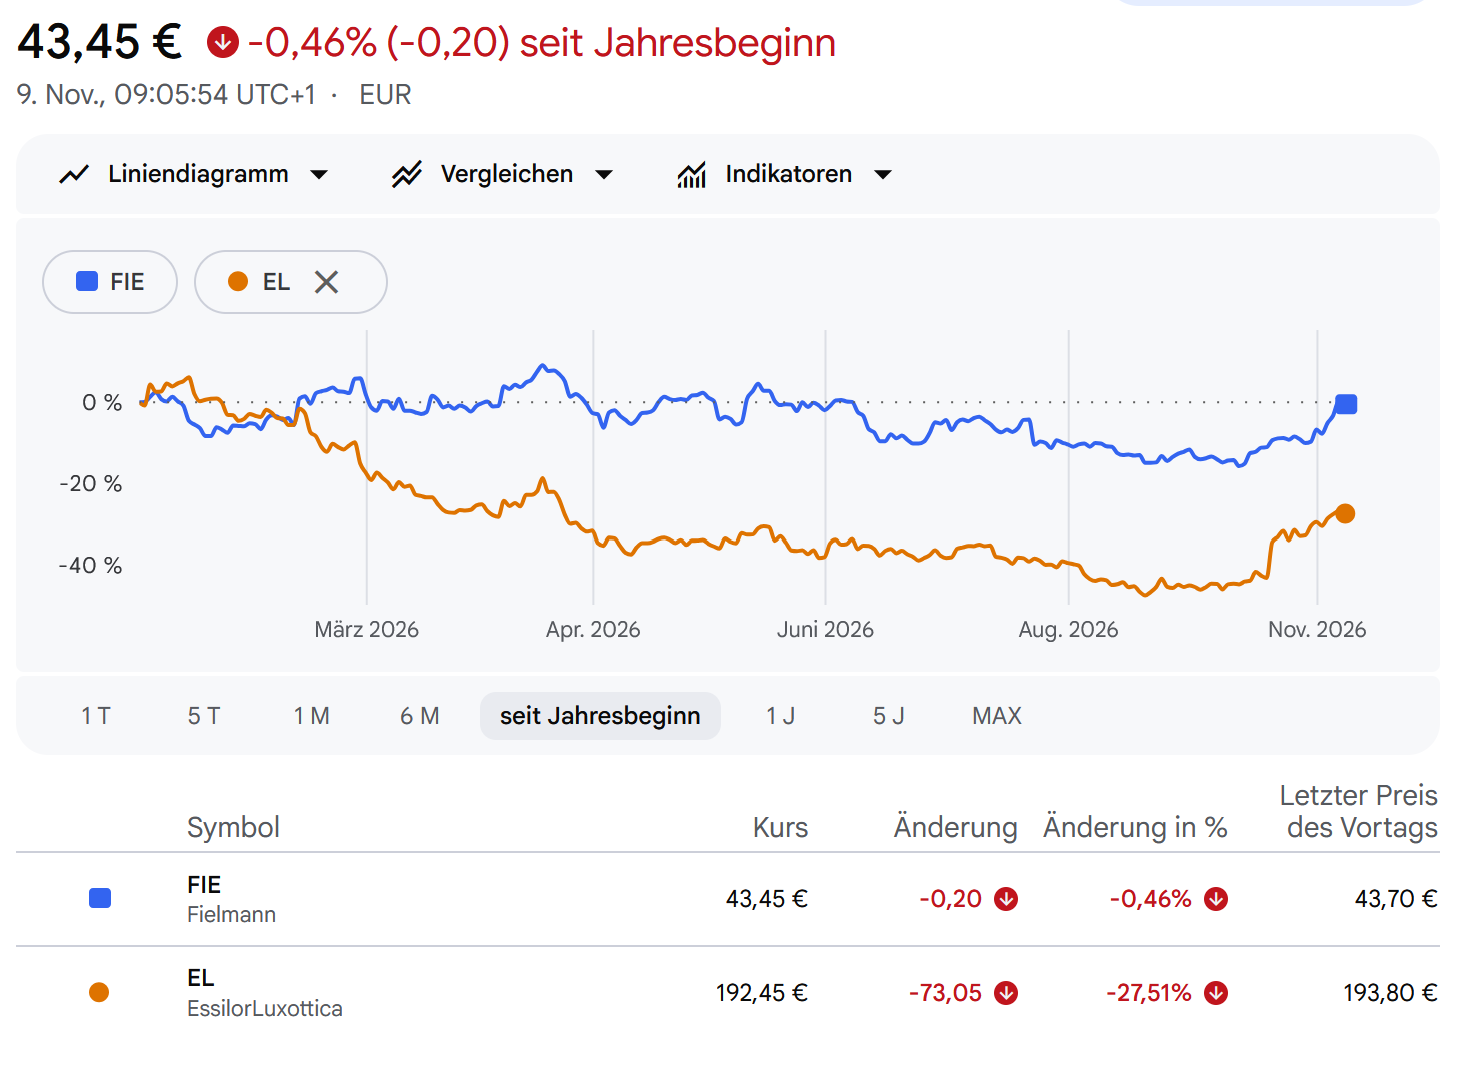
For Fielmann, it seems that they will most likely reach their 2026 targets, but the US business still seems to be in a turn-around mode, which maybe explains the exit of the US business head earlier this year.
Auto Trader
My “Portal Pain Basket” member Auto Trader released HY numbers last week. The results are only “so so” at a first glance:
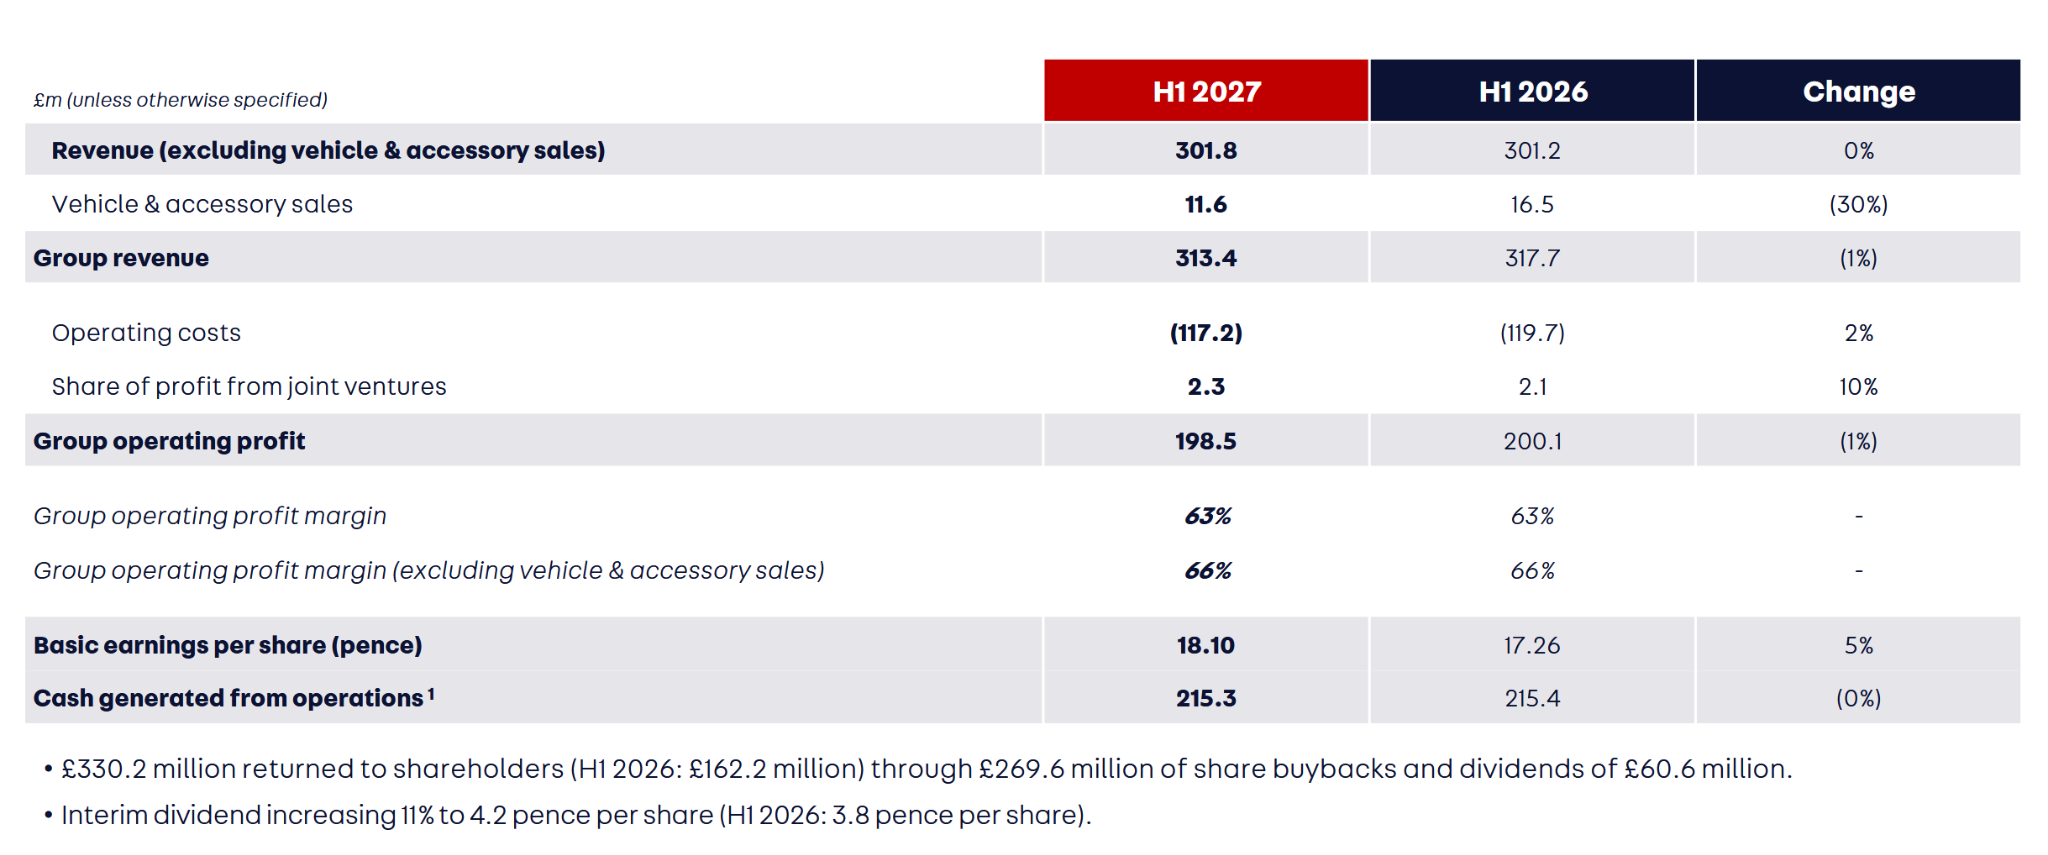
Revenues slightly declined, margins stayed constant but EPS went up due to massive buy backs. In their outlook they mention that they expect revenue growth in the second half of their financial year.
On the plus side, they report that they bought back a lot of stock at a decent price:
“During the period, a total of 55.7 million shares (H1 2026: 12.6 million) were purchased for a consideration of £269.6m (H1 2026: £100.2m) before transaction costs of £1.3m (H1 2026: £0.5m). The average price per share was 483.4p “
With a NTM P/E of 13,6x, Auto Trader is still cheap but of course without any visible growth, the upside is also limited. If they can actually return to growth in the second half, then this could get more interesting.
Rightmove
Rightmove issued a Trading update last week. The good news is that revenues have been growing at 7%, however operating profit was lagging revenue growth:
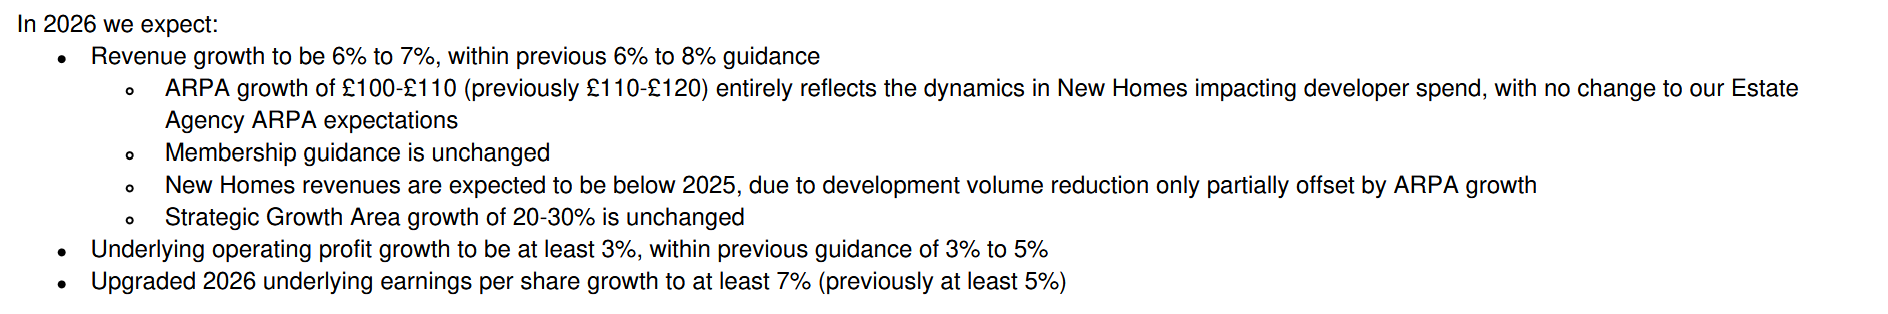
In 2027, they see similar revenue growth as in 2027 and improving operating results:
For 2027, reflecting the challenging and uncertain macro backdrop, we currently expect:
Revenue growth similar to 2026 as the current end-market dynamics are expected to continue into next year. This reflects the full-year impact of fewer New Homes developments and a subdued Estate Agency market. We expect: ARPA growth of £100-£110 Broadly flat Core membership Strategic Growth Areas growth of 20-30%
An increase in underlying operating profit growth to 4-7%. This will be driven by product launches, productivity gains and cost discipline alongside ongoing investment in
the initiatives announced in November 2025, with a margin of at least 67%
Underlying earnings per share growth of at least 10%
Considering the overall environment in the UK, this was a pretty decent trading update for Rightmove. As a (still) growing company, the slightly higher valuation compared to Auto Trader seems justified.

