Monthly Archives: September 2026

Another Return of the Travel Series: Is it now time to buy Booking at 15x NTM P/E ?

Background/Intro_

Some readers might remember that I did a series on Online travel companies some years ago. Here is the link to the last post, including links to previous posts (2017 to 2022, time flies…)

I ended up investing for a short time in Expedia but, for some reason, never looked at Booking.com, which even back then was the clear market leader.

Looking at the charts we can see that Expedia and Booking have done OK. Booking actually did better than the S&P until early 2026:
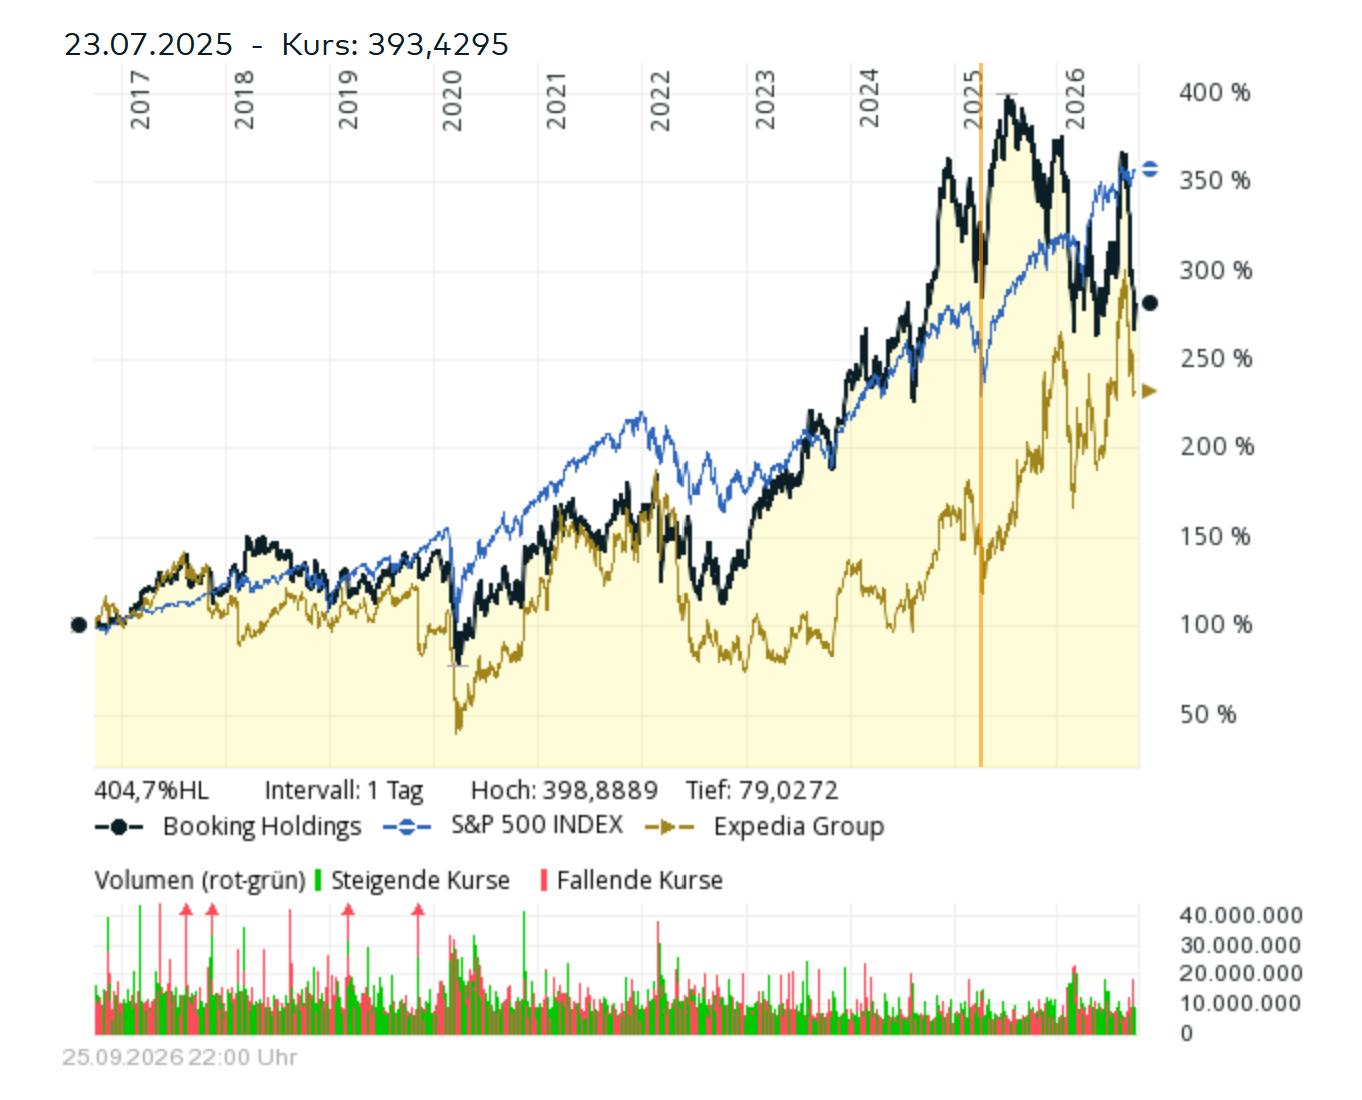
Back then when I wrote the series, the newly launched Google Travel was the big bogeyman and mostly killed the pure “display aggregators” like TripAdvisor and Trivago, whereas the “Booking engines with inventory” like Booking and Expedia did ok.

Another interesting comparison is AirBnB and Booking. Comparing both since AirBnBs much hyped IPO in Decmeber 2020 is pretty interesting:
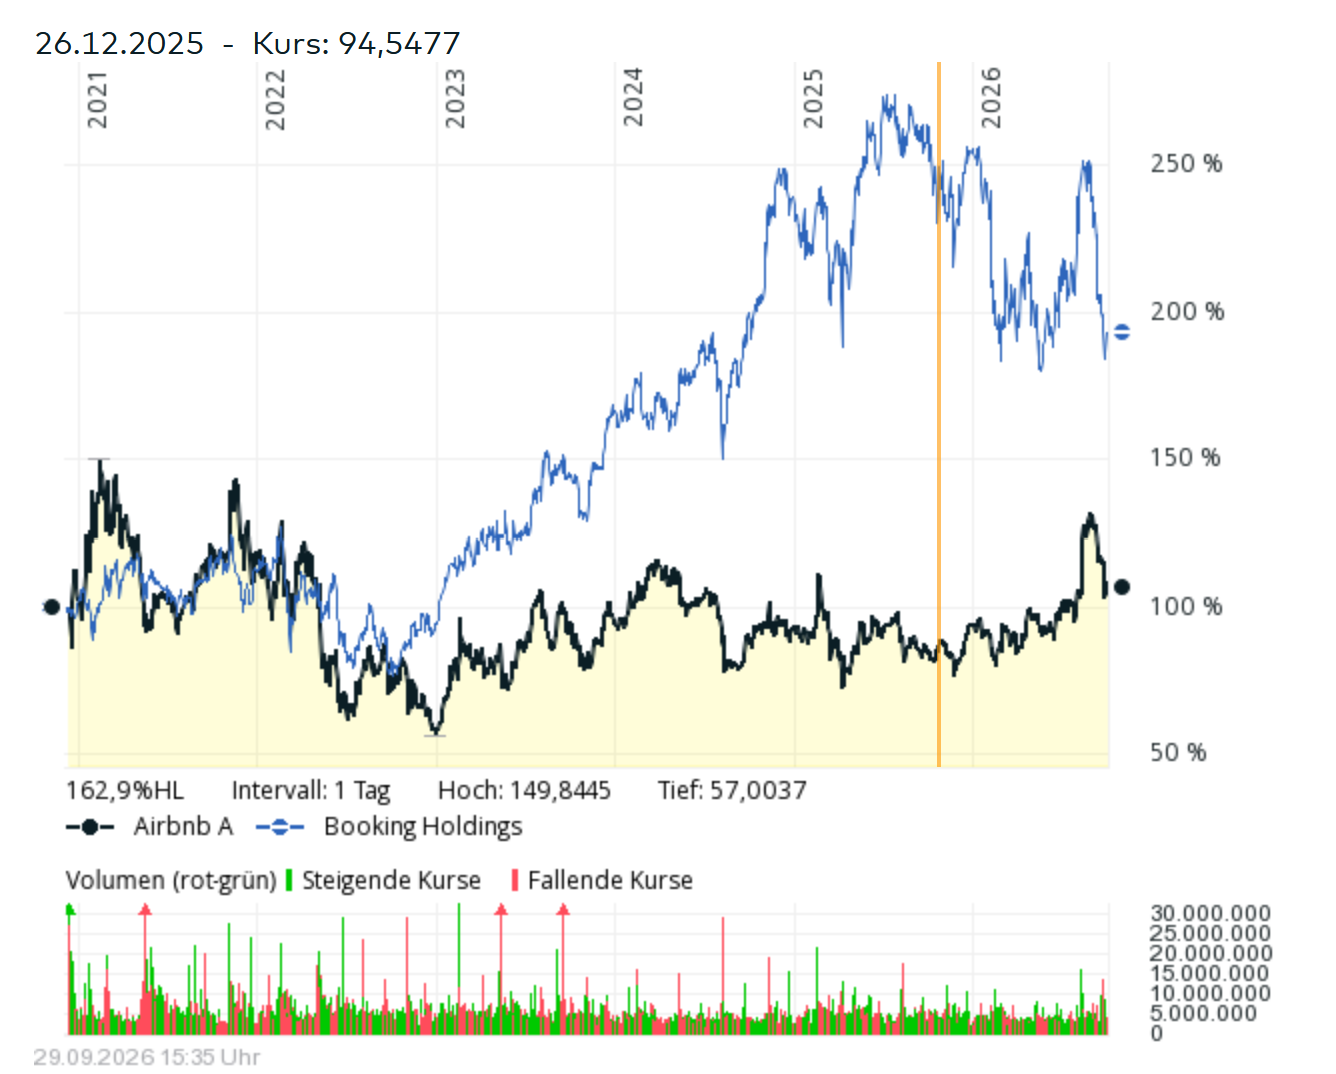
While Booking is still up nicely, AirBnB didn’t go anywher. for the last 5-6  years-

Under the hood however we can see Booking, with the exception of the Covid period, historically traded at a NTM P/E of ~25x whereas today it is only trading at ~15x NTM P/E-
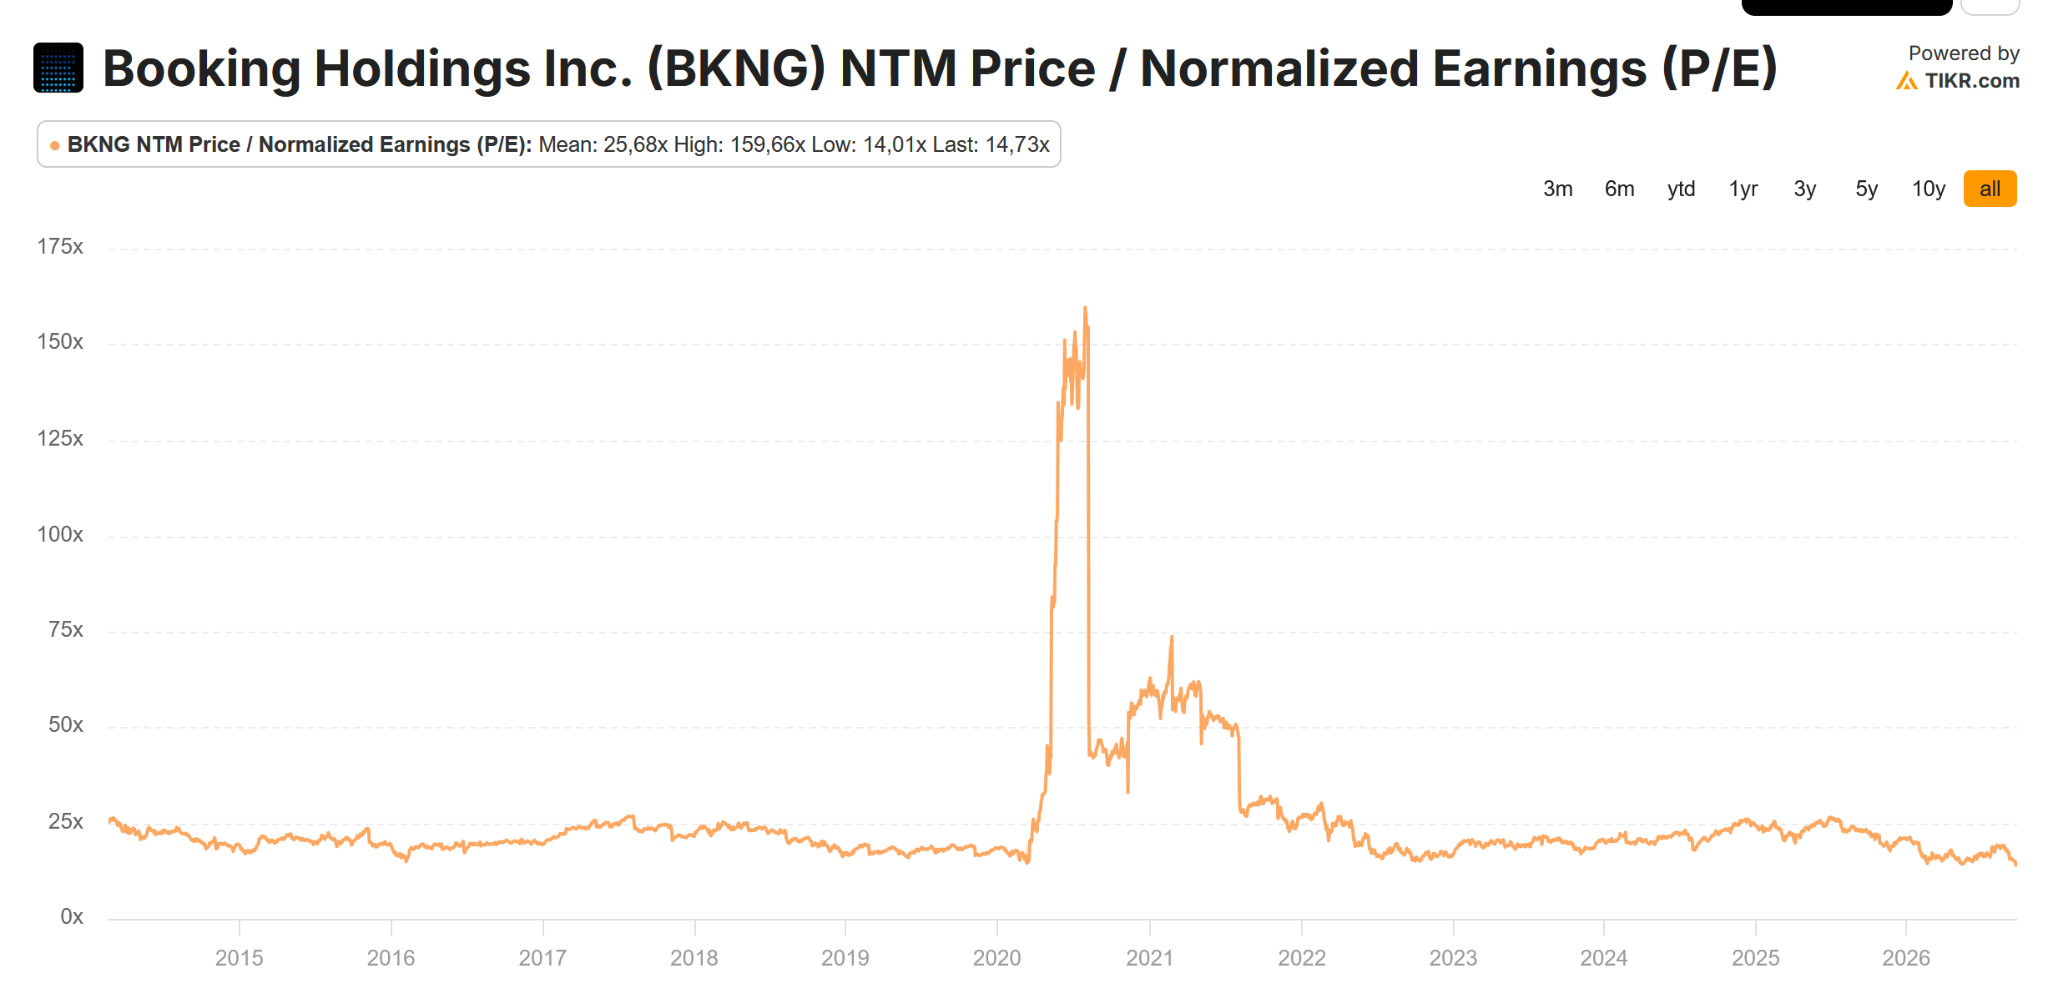
This is the reason why I decided to have at least a first look into it, as a P/E of 15 for a “high quality compounder” is not a bad starting point.

Booking has changed over the past years

One of the most striking things about Booking is how they have changed their underlying business model over the past few years compared to when I started the travel series.

They always distinguished between Merchant vs. Agency bookings. A merchant booking is when you pay to Booking first and then Booking pays the Hotel/Airline/Car rental. An agency booking in contrast is when Booking is not involved in the payment and just creates the “match”.

This is how things looked in 2018/2019:
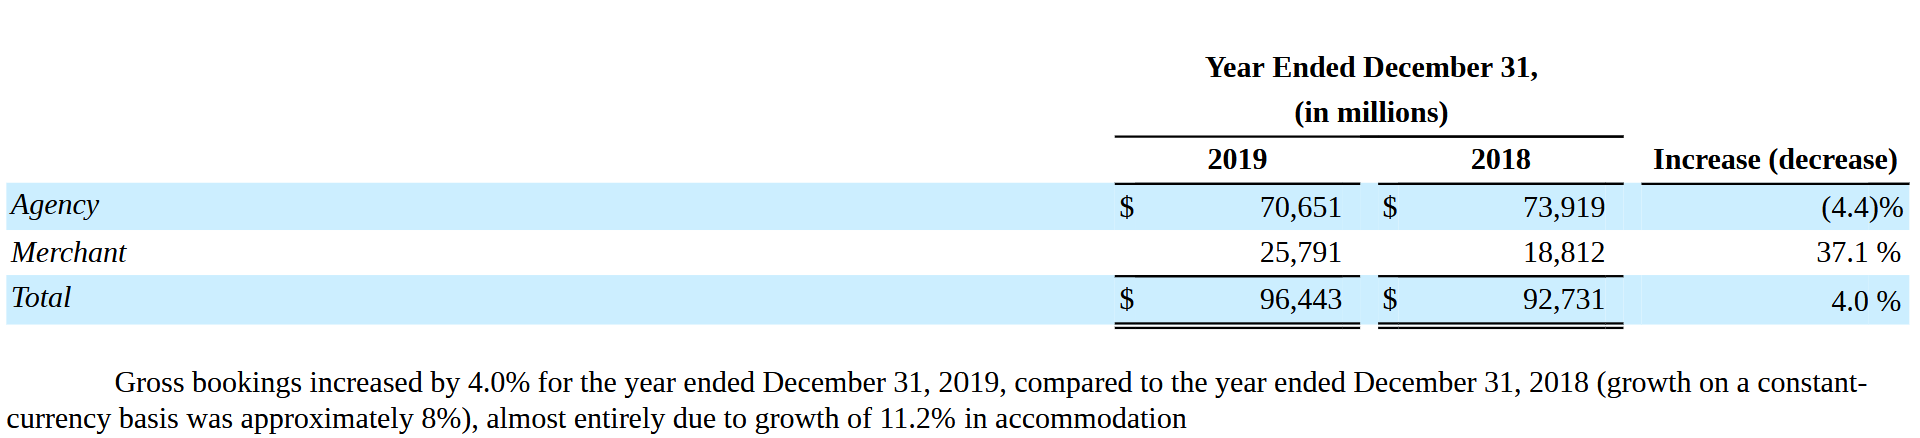
80% of Booking’s business was Agency, only 20% were merchant transactions. Now let’s compare with the first 6M 2026:
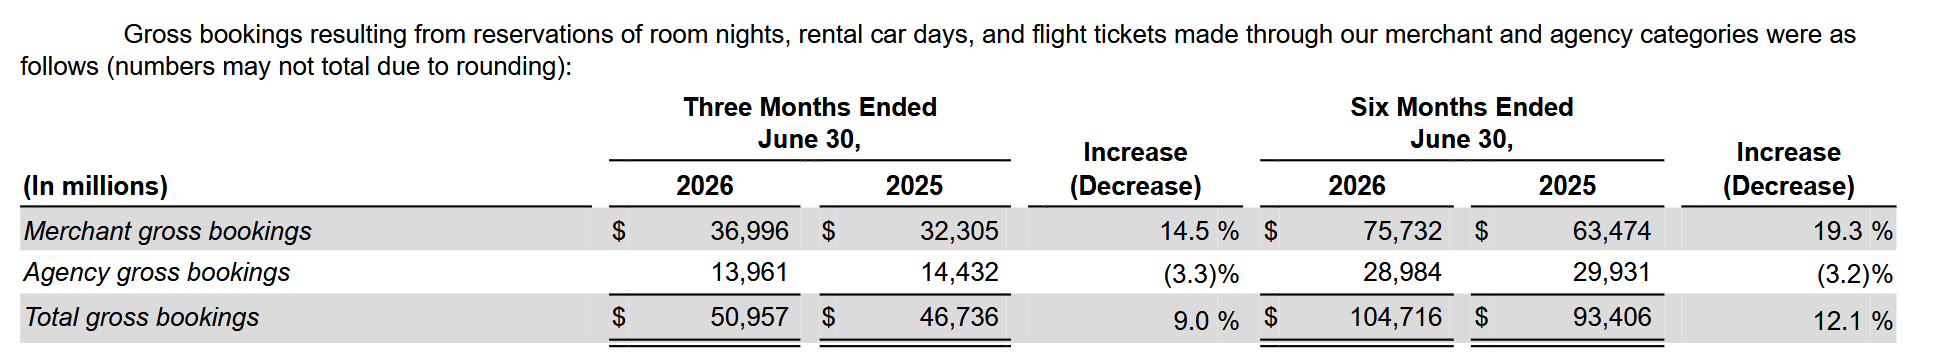
Today, 73% of the bookings are Merchant bookings and the merchant share is still increasing.

Booking initially focused on the Agency because this was market standard and easier to implement especially with the hotels but not very cash efficient, as they had to “front” all advertisement expenses and could only collect the commissions much later.

With the merchant model, similar to airlines or package holiday companies, they can create a nice, interest free “float” of customer prepayments. In total, that results in significant negative working capital, meaning that further growth actually creates capital instead of requiring capital which is a very nice position to be in.

In addition, Booking has diversified much more into apartment rentals,  airline tickets and car rentals. They don’t tell us how much the share of these categories is in USD, but this part from the 2025 report shows that especially airline ticket sales are growing significantly:
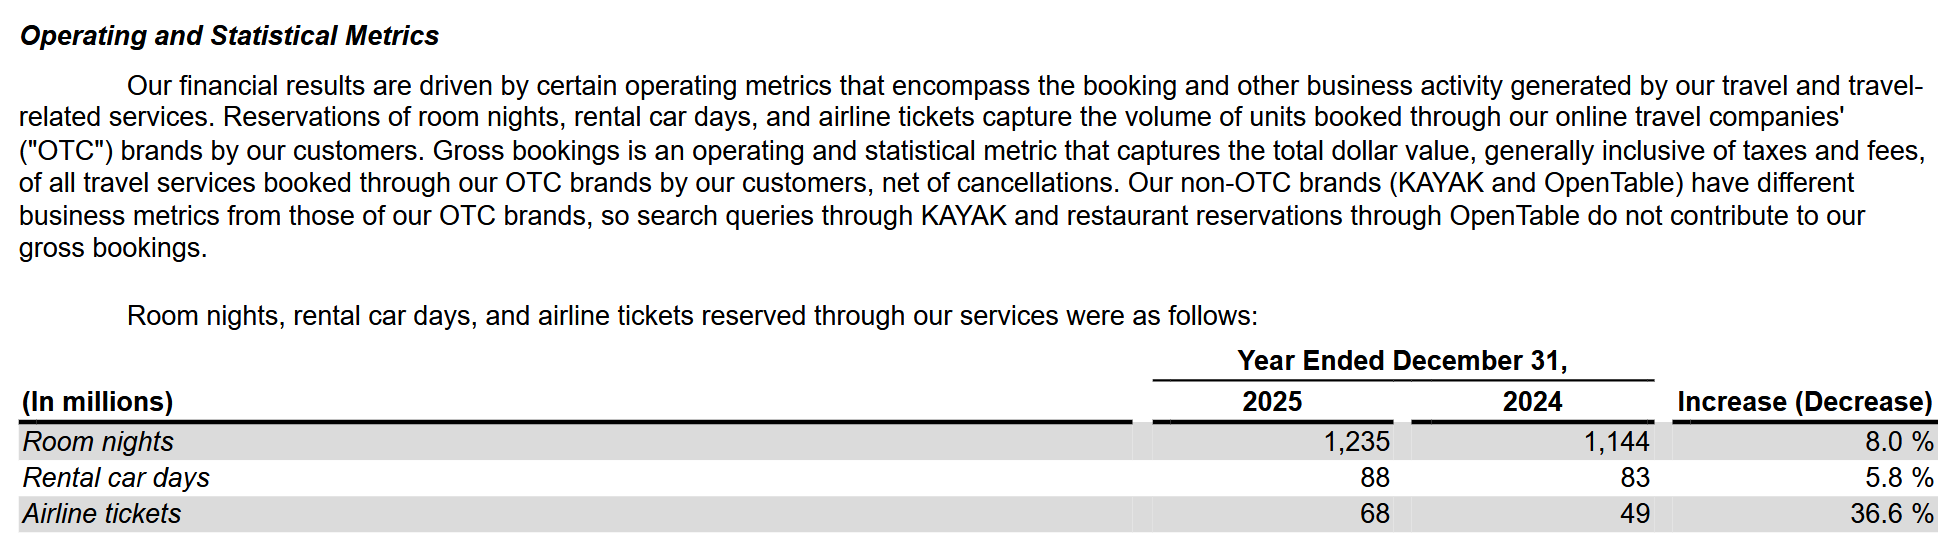
Booking is calling this the “connected trip” which is currently still a relatively small slice of the pie but seems to grow faster than the overall business:

Cash generation & share buybacks

Increasing the merchant model share means that Booking holding has been creating tons of cash despite nice growth in the past and uses most of that cash to buy back shares on top of a small dividend.

This is a chart from their latest presentation:
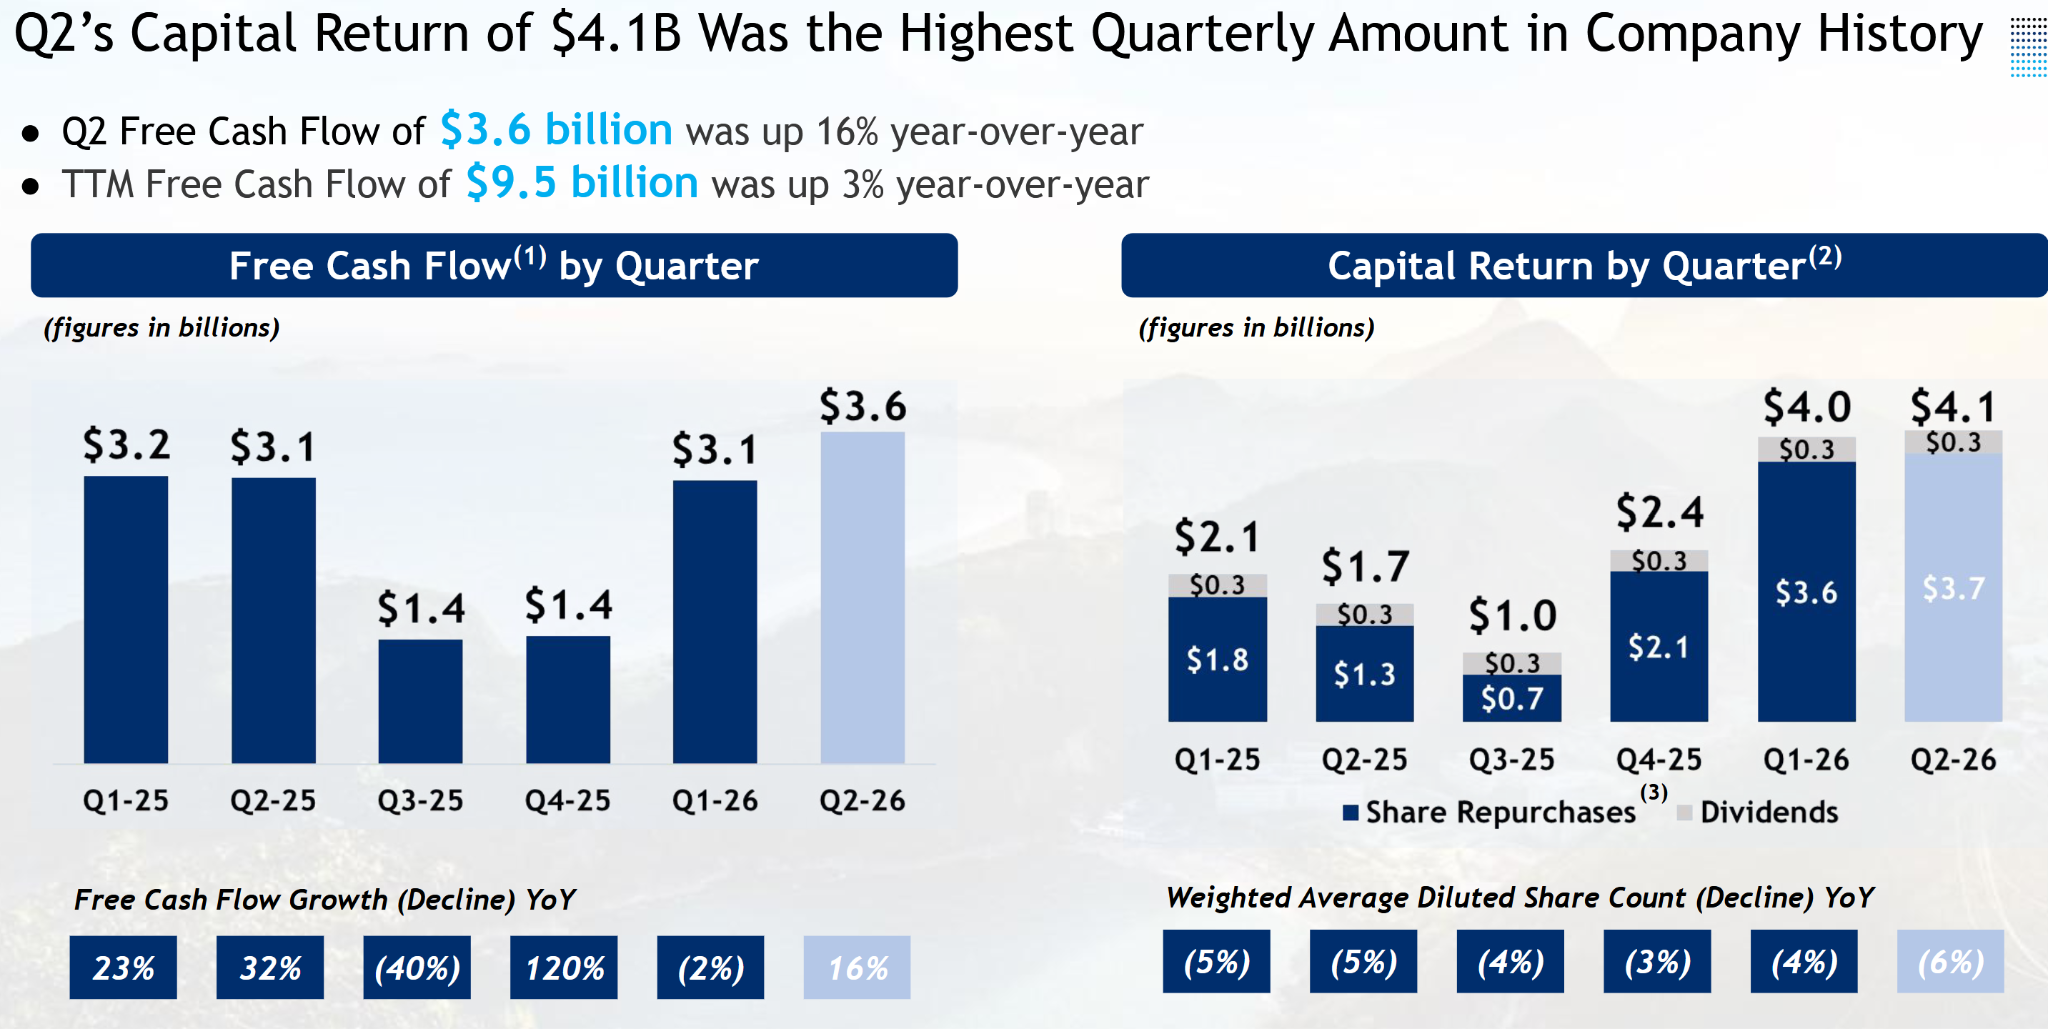
This TIKR chart shows how share count has evolved over the past 10 years:

With the exception of Covid, they have been reducing sharecount by around -5% CAGR over the past 8 or 9 years.

Geopolitical exposure

Travel and tourist related stocks like Booking are always exposed to Geopolitical tensions. As they mention in their Q2 report, the Iran war has dampened demand from the important Gulf region.

High fuel and ticket prices will also maybe lead to shorter holidays in many cases and less nights that are booked.

As we can see in Bookings 6M report, growth rates already came down in Q1 and further in Q2 because of the start of the Iran war:
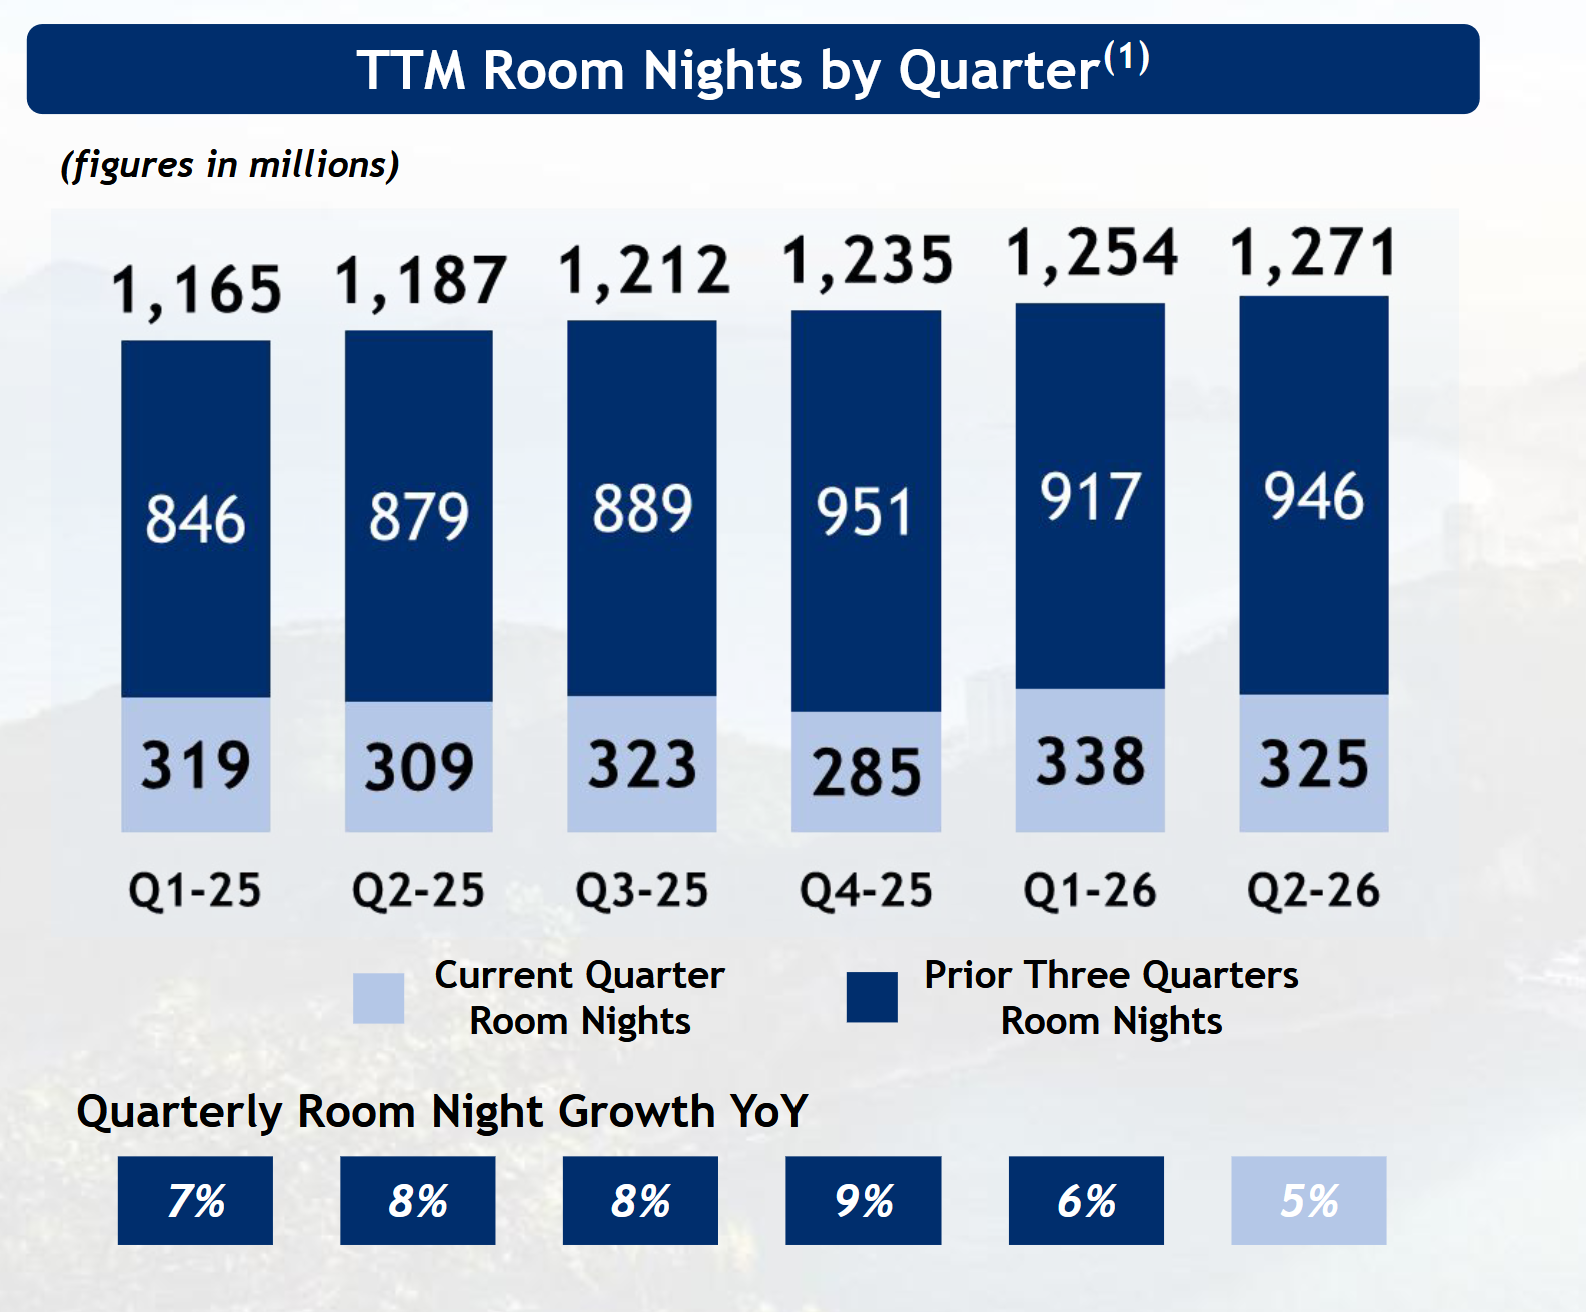
Especially the Q1 number is quite surprising, as the war started “only” at the end of February.

Normally, such a (temporary) weakness in global travel has always been a good time to invest especially in a market leader like Booking. From the lows in the initial Covid months, the stock had made 4x in the next 5 years or so. But: Also for Booking, the perceived threat of “Agentic AI” has to be considered.

So let’s move on now to the Agentic Thread (MUSE & Co)

Booking is a company where many people have some experience with the product, myself included. I have to admit that I have some kind of love&hate relationship. I love Booking for doing initial research on hotels. But in many cases I try to find out after choosing an option if I can get it at least as cheap directly. Sometimes it works, sometimes it doesn’t.

A big risk in investing especially with “consumer stocks” is always to look at ones own behaviour and then make conclusions for all the other consumers based on your own behaviour. That only works, if your behaviour is similar to the majority of consumers. If not, this can land you in a lot of trouble.

So in this case, I don’t think that my own behaviour is a good proxy for all consumers. I actually enjoy doing research for a family holiday trip, which is something that most likely not a lot of people share. 

From what I am reading right now, Muse is not very good and makes a lot of mistakes. A friend of mine experimented with Clawbot, which also had its limits. But as ChatGPT, I do assume that those agents get better rather quickly. 

So the question is: Will a lot of people delegate more and more tasks to these agents and which ones ?

The big question one needs to answer is the following: Is, maybe, travel a category that gets more easily disrupted by Agents compared to buying a car, an insurance policy or even a house ?

My answer to that is: I do not know, but I guess Travel is more exposed to this than Cars or houses. The next question then is: Will Agents “cut out” the middle man (Booking) or rather use the middle man as an easy source in order to fulfil tasks ?

Those are very difficult questions which in the case of Travel, I am not able to answer.

One indication that it could take more time than current “Agentic maxxers” think it takes is this page from the Booking presentation:
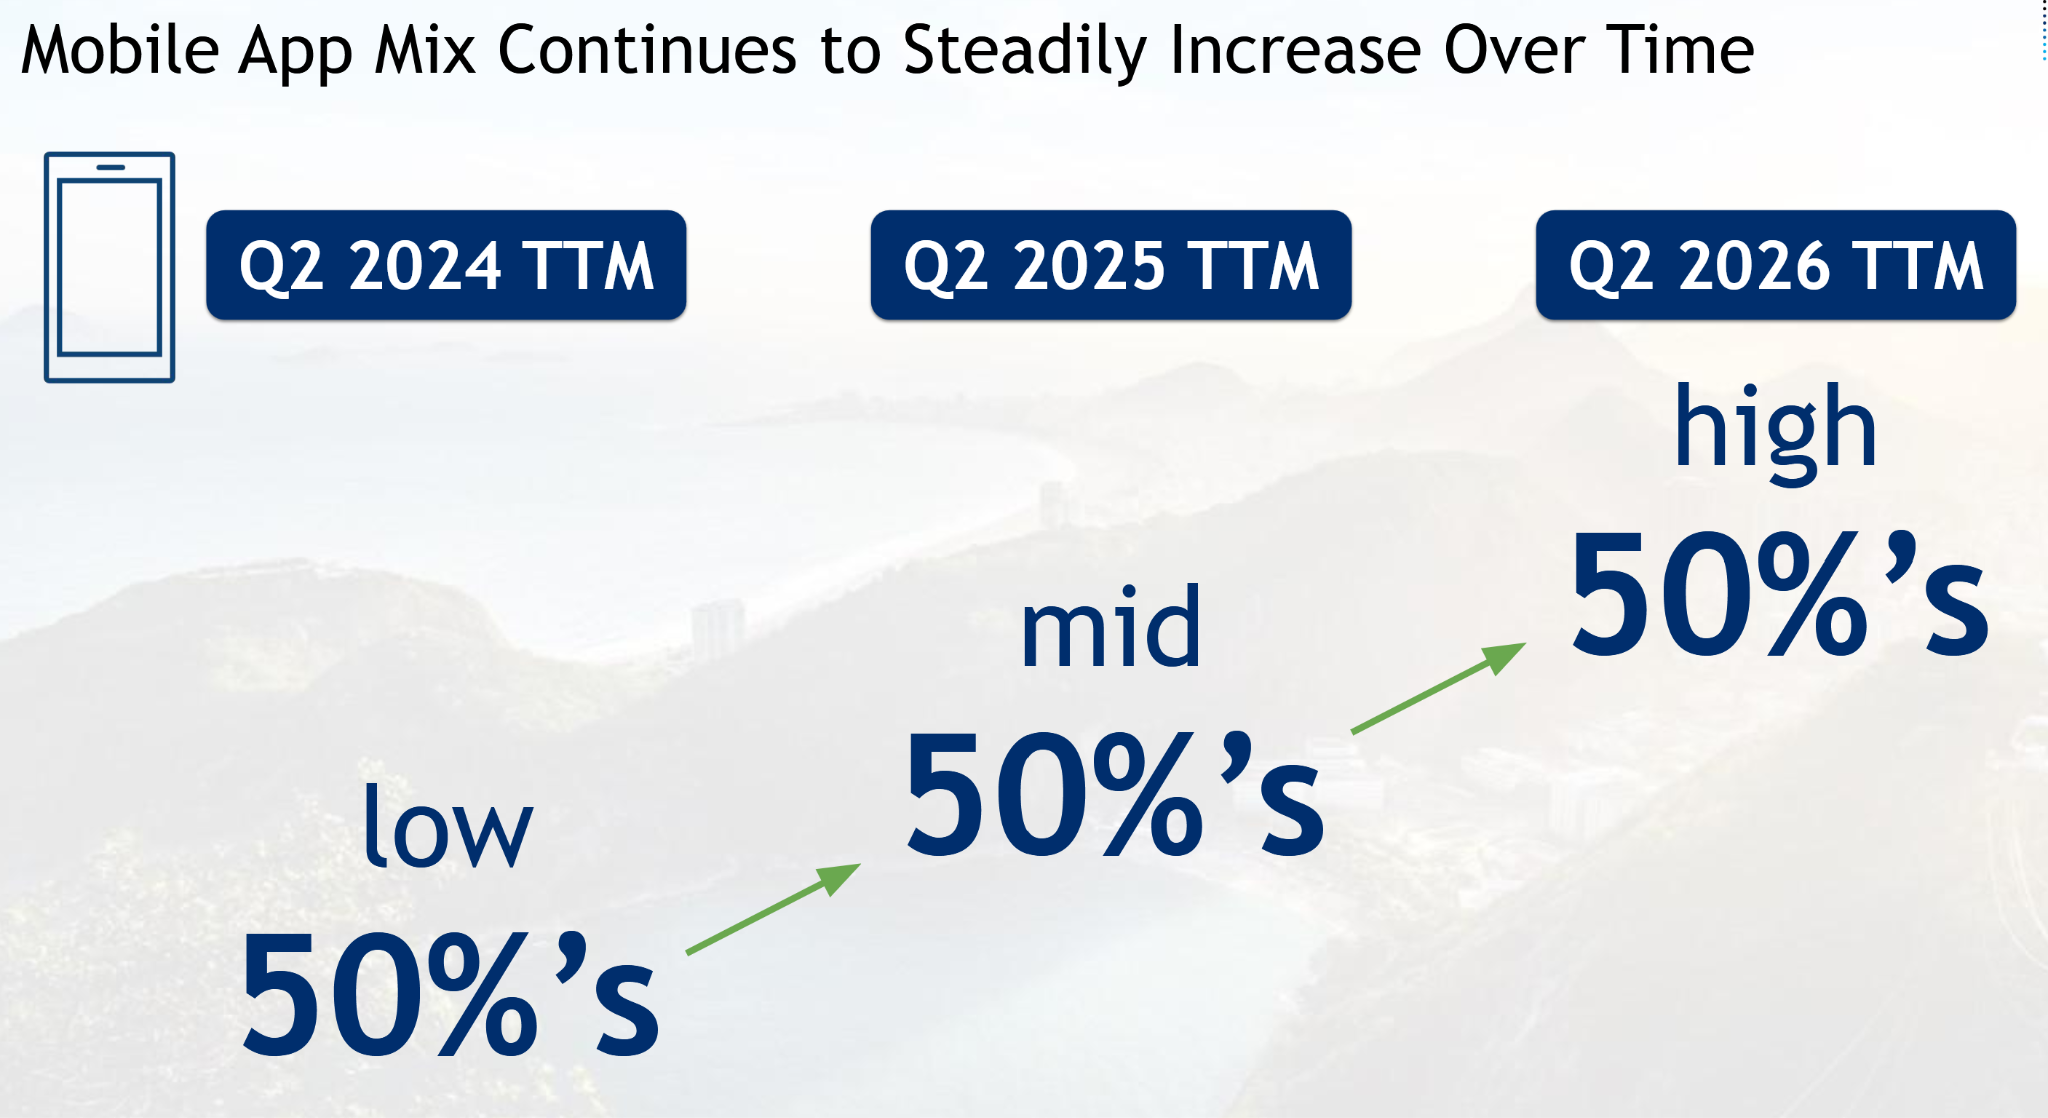
I think it’s still kind of interesting that only slightly more than half of Bookings clients are using a mobile device. This is interestingly below the average in E-Commerce which indicates that travel might be a little bit different compared to buying a new vacuum cleaner etc.

Some statistics show that more and more people use Chatbots for planning a trip, which so far however has not structurally changed the business model of Expedia and Booking, as they were able to integrate themselves into those conversations. So there is clearly also a path, where Expedia and Booking remain (very) relevant even within Agentic commerce.

On the other hand, Booking’s fast growing segments “connected trips” and airline tickets could be the first ones to see some kind of disruption. 

But in any case, I find it much harder to underwrite Booking at 15x NTM P/E compared to an Autotrader at 12x or a Rightmove at 15x.  Maybe I am wrong here, but only time will tell.

I do think that the risk is clearly higher for Travel and therefore for Booking than for categories such as Cars, real estate and even insurance which is regulated.

Summary:

Not looking at Booking 7-8 years ago because they were expensive, was clearly a “failure of omission”.

However, despite the rather attractive valuation, in Booking’s case, I am less sure if and how fast Agentic E-Commerce could negatively impact the business model.

Letting an AI Agent book a (cheap) flight is clearly less a leap of faith then letting an AI agent buy a new car or even a new home for you.

I will keep Booking on my watch list and might revisit if it becomes even cheaper, but for the time being, I could not convince myself to establish a position in the stock, despite all the obvious qualities of the Business model.

Appendix: Good Podcast discussing Booking’s business model

Why Booking.com built a business competitors can’t replicate

and another one
Some links 24/2026

Graoullie (or his Antagonist) on the history of Dior and the LVMH holding structure

Andrew Brown with an update on Exor Spa

Some good thoughts about the impact of Meta’s Muse on “Inertia loser” stocks

Corteva is spinning of its Seeds business soon. Good write-up from “Value don’t lie”.

Howard Marks on US interest rates, deficits and the Dollar

A decent deep dive into Rightmove from UK Dividend Stocks

The Hermit substack on struggling Swedish Serial Acquirer Green Landscaping

Not aMUSEd: The UK “Portal Pain Basket” (Mony Group, Autotrader & Rightmove)

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH

I actually started to write this post before the newest hype about “Muse”, the new AI Agent from META, really went mainstream. I decided to leave the old part and then update it instead of completely changing it.

As my DCC investment ends its “natural life” and I have begun to unwind it, I decided to have a look at a group of beaten up UK stocks that one could summarize as “Comparison portals” or “Two sided online market places”: : Mony Group (Insurance), Autotrader (cars) and Rightmove (real estate).

As the post became quite long, I also picked a track to keep you entertained while your LLM assistant is summarizing the post for you:

Green Day – Basket Case

Green Day – Basket Case [Official Music Video] (4K Upgrade)

Here a quick summary for each company: 

Mony Group SE

Mony Group, the former Moneysupermarket Group is a UK focused comparison portal where people go to compare quotes for Insurance policies, loans, broadband tariffs, electricity contracts. in addition they offer a referral shopping app/system that offers Cashbacks (discounts).

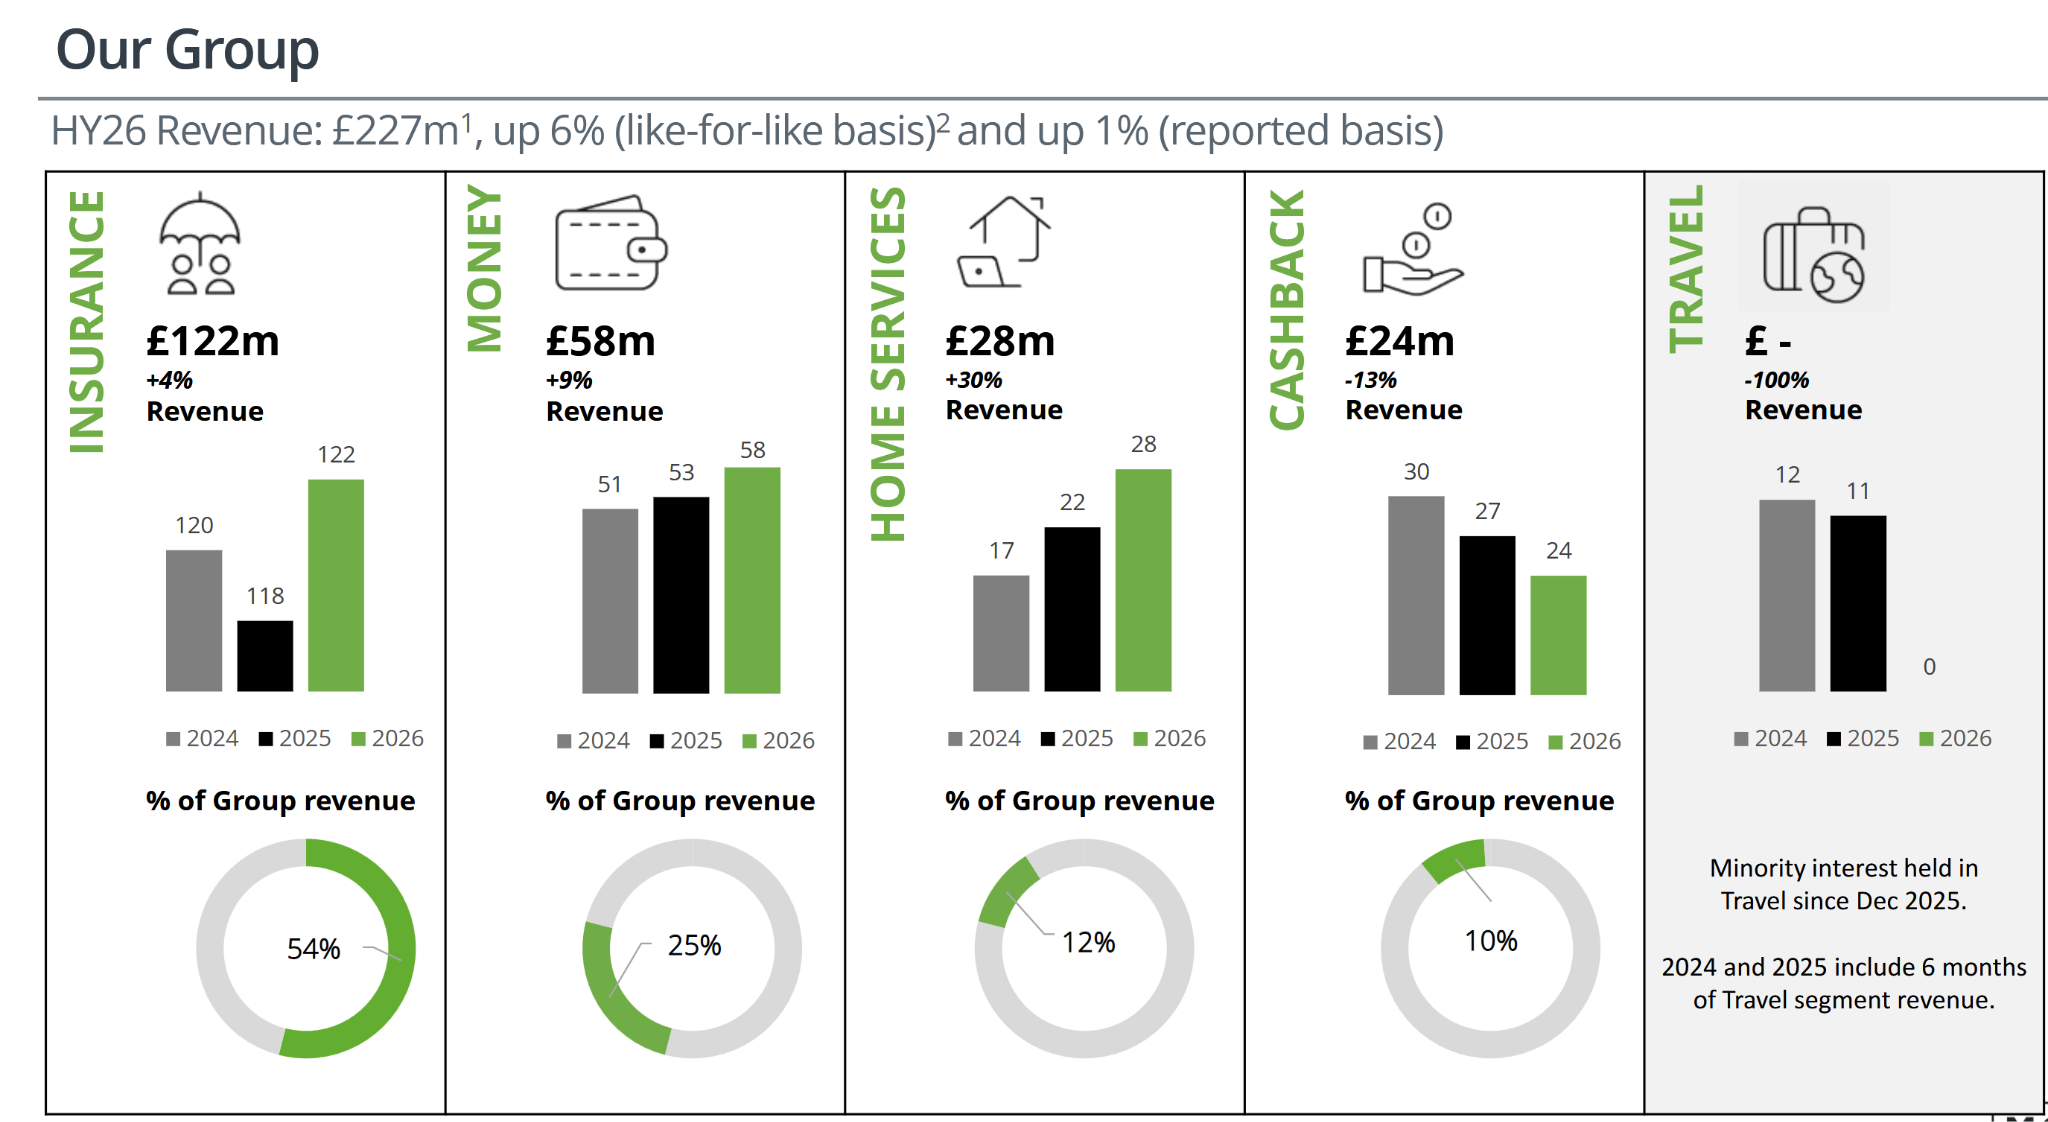
This is from the 6M Investor presentation with the distribution of sales::

We can see that insurance is over half and that they have disinvested travel related offerings in 2025.

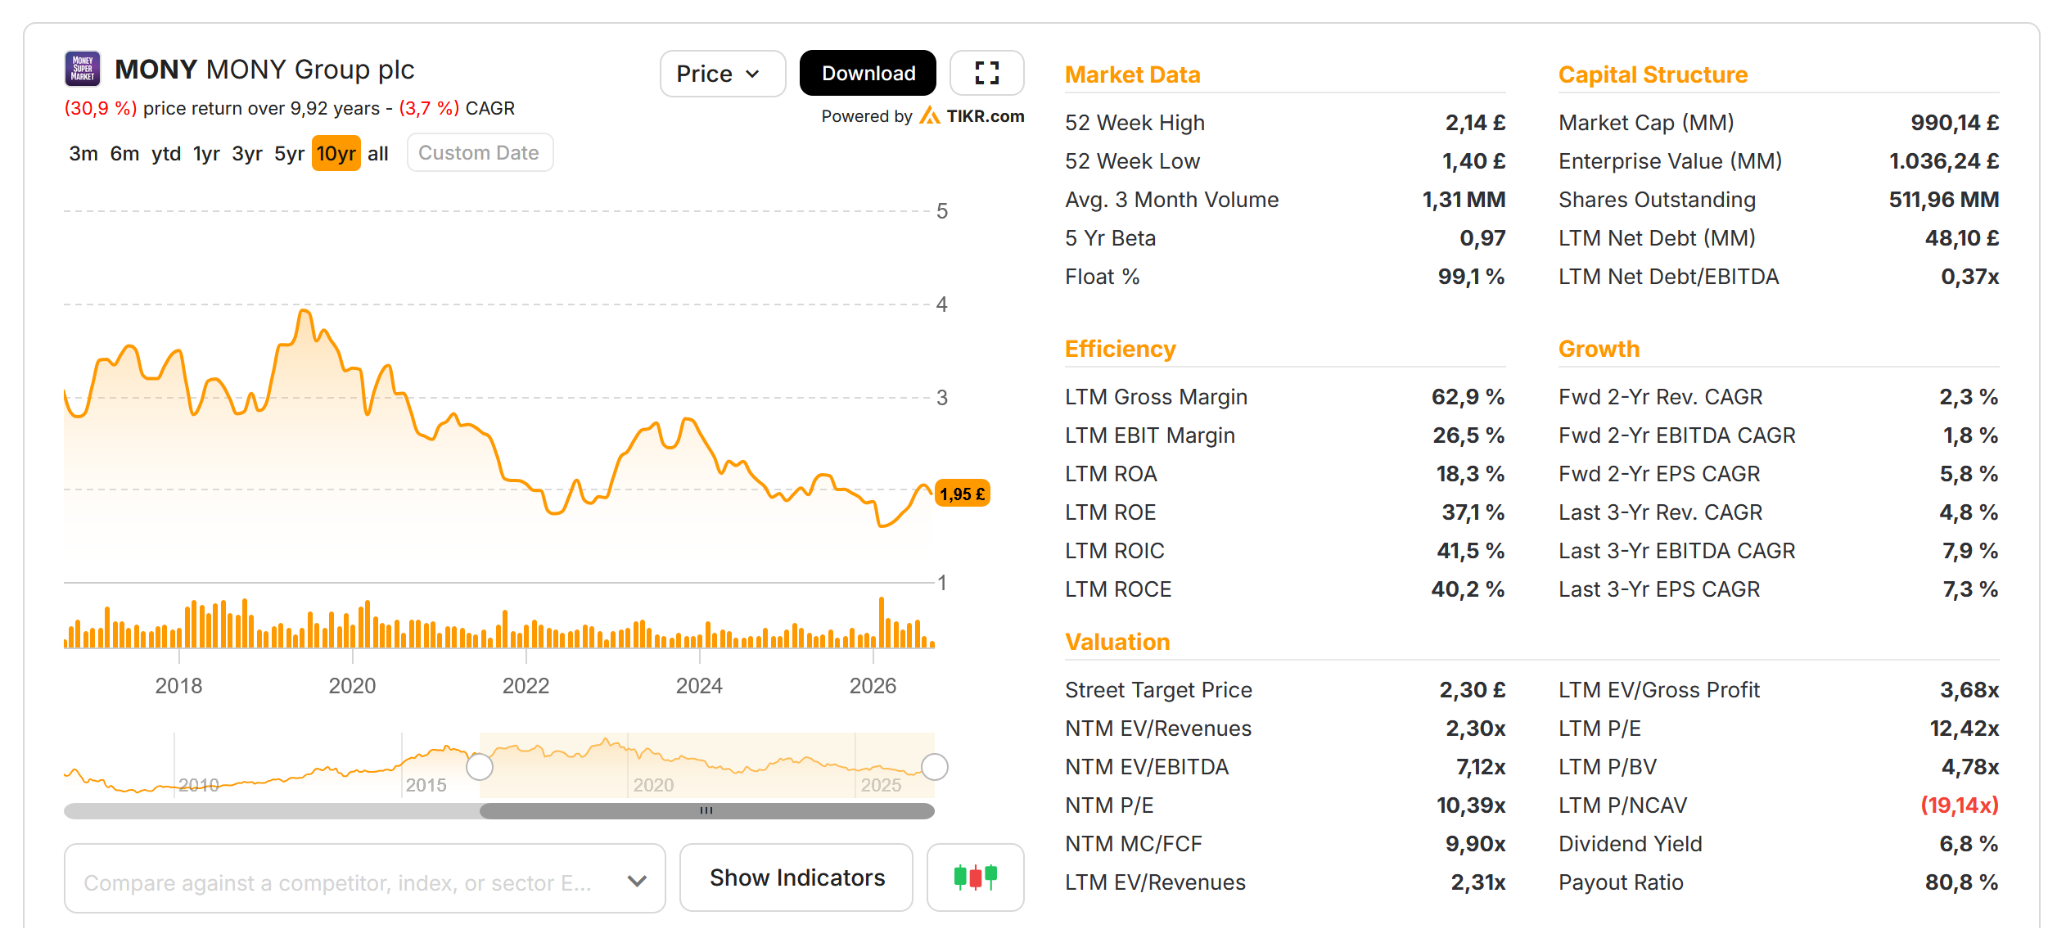
This TIKR Screenshot shows us that Mony’s stock was not a very good investment over the past 10 years:

However the share price seems to have stabilized to a certain extent and the stock is cheap. The business as such is very profitable and has been growing low single digits for the past 3 years or so.

Other than the next two companies, Mony is only the number two comparison portal in the UK, pretty far behind a site called “Compare the Market” but bigger than “go.Compare” and “Confused” which used to belong to Admiral.

One important detail is that Italian Marketplace company Moltiply (former Mutui Online) is the largest shareholder with ~12% and they have been adding as recently as in June 2026.

Multiply has been collecting comparison marketplaces steadily, like Verivox in Germany or the non-UK sites from Admiral.

Autotrader

Autotrader is THE leading UK online car portal where both auto dealers and private customers are buying and selling mostly used cars. It used to be a print magazine but successfully transformed into THE dominant online market place in the UK.

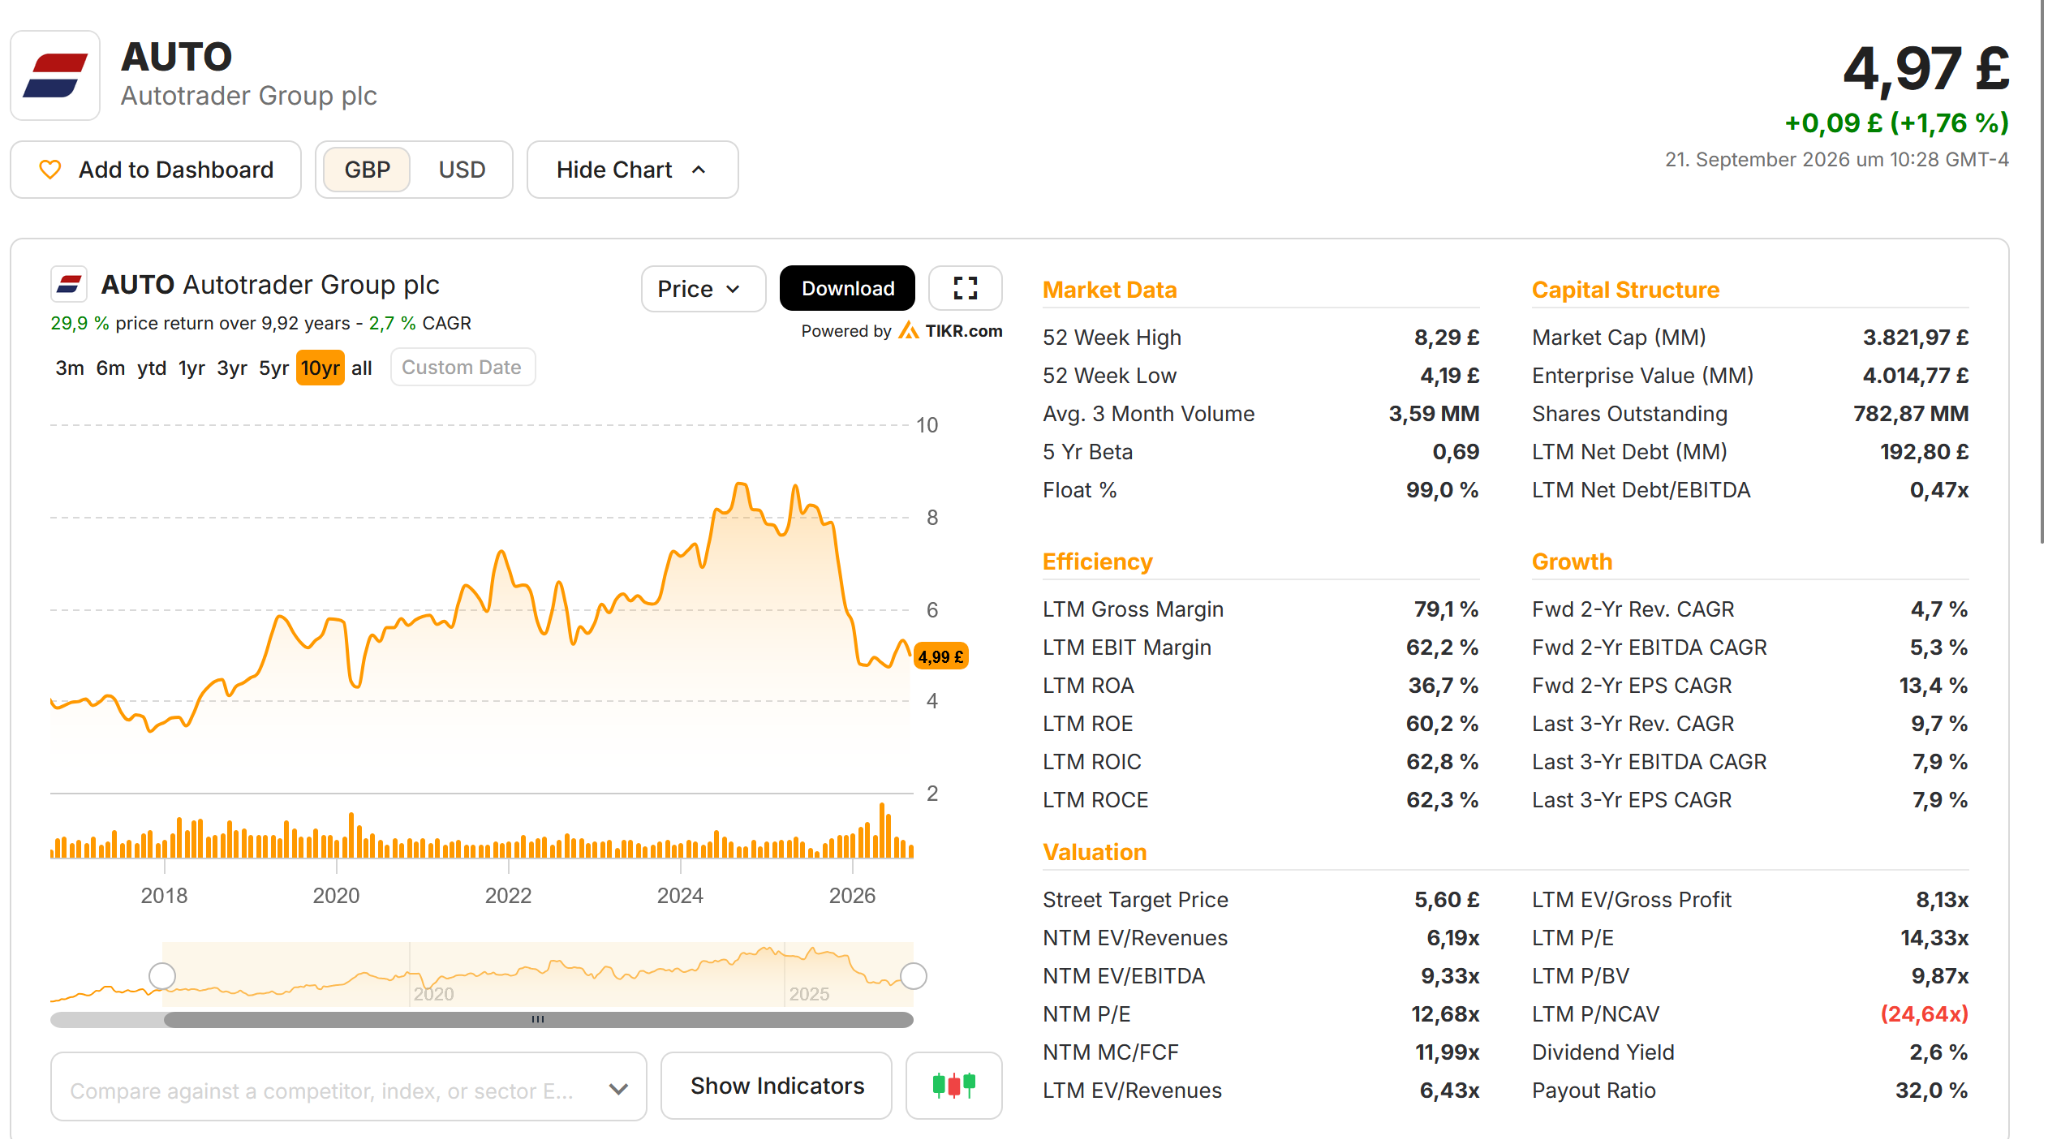
It is supposed to have a market share of 75-80% in the UK. Over the last 10 years, it has not done much especially after it got hit by “SAASocalypse” fears:

The stock is a little bit more expensive than Money Group, but almost absurdly profitable.

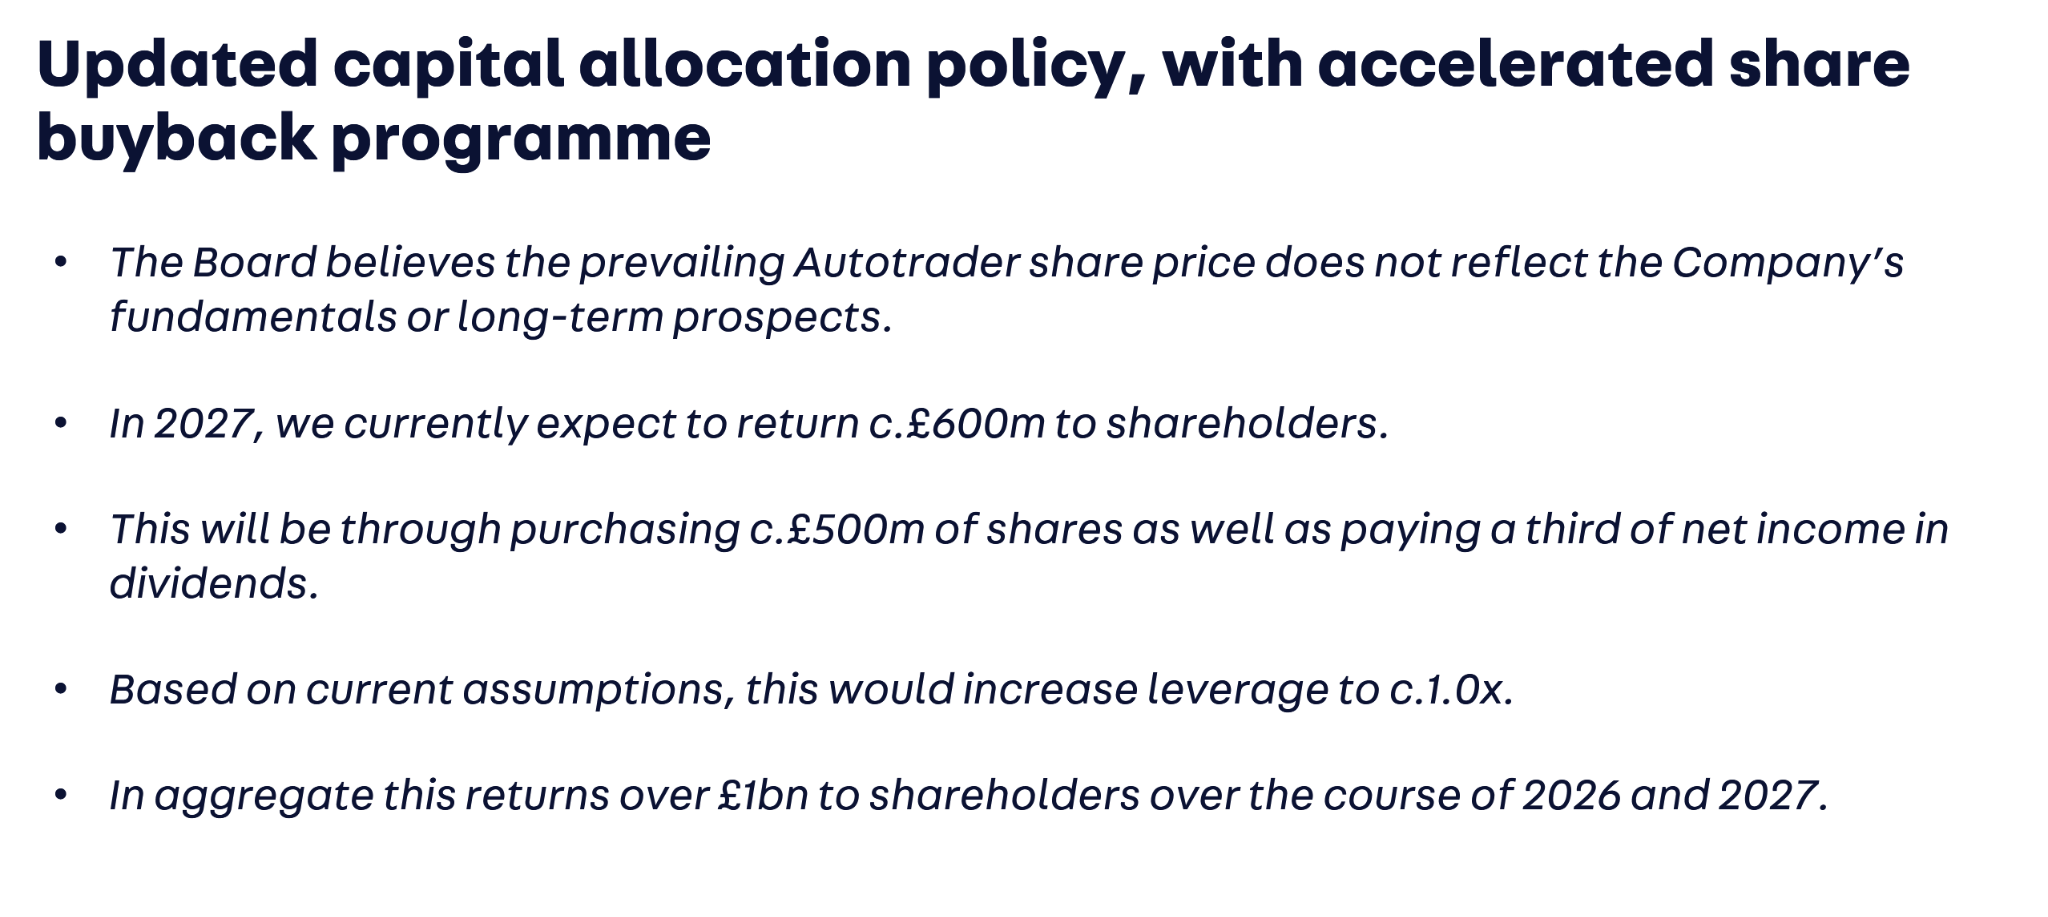
What is worth mentioning is that Autotrader has already started and committed to a massive share repurchase program:

One additional threat for Autotrade is that Amazon seems to be going for a piece of Autotraders cake and wants to enter the market still in 2026.

In the US, where Amazon is already in the market, success so far seems to be mixed at best. It reminds me a little bit about the auto tire business where Amazon started some years ago but didn’t succeed either.

Rightmove

What Autotrader is to cars, Rightmove is to real estate with the only exception that Brits are really obsessed about real estate. Almost any (friendly) Brit I know is using far too much time scrolling through right move listings.

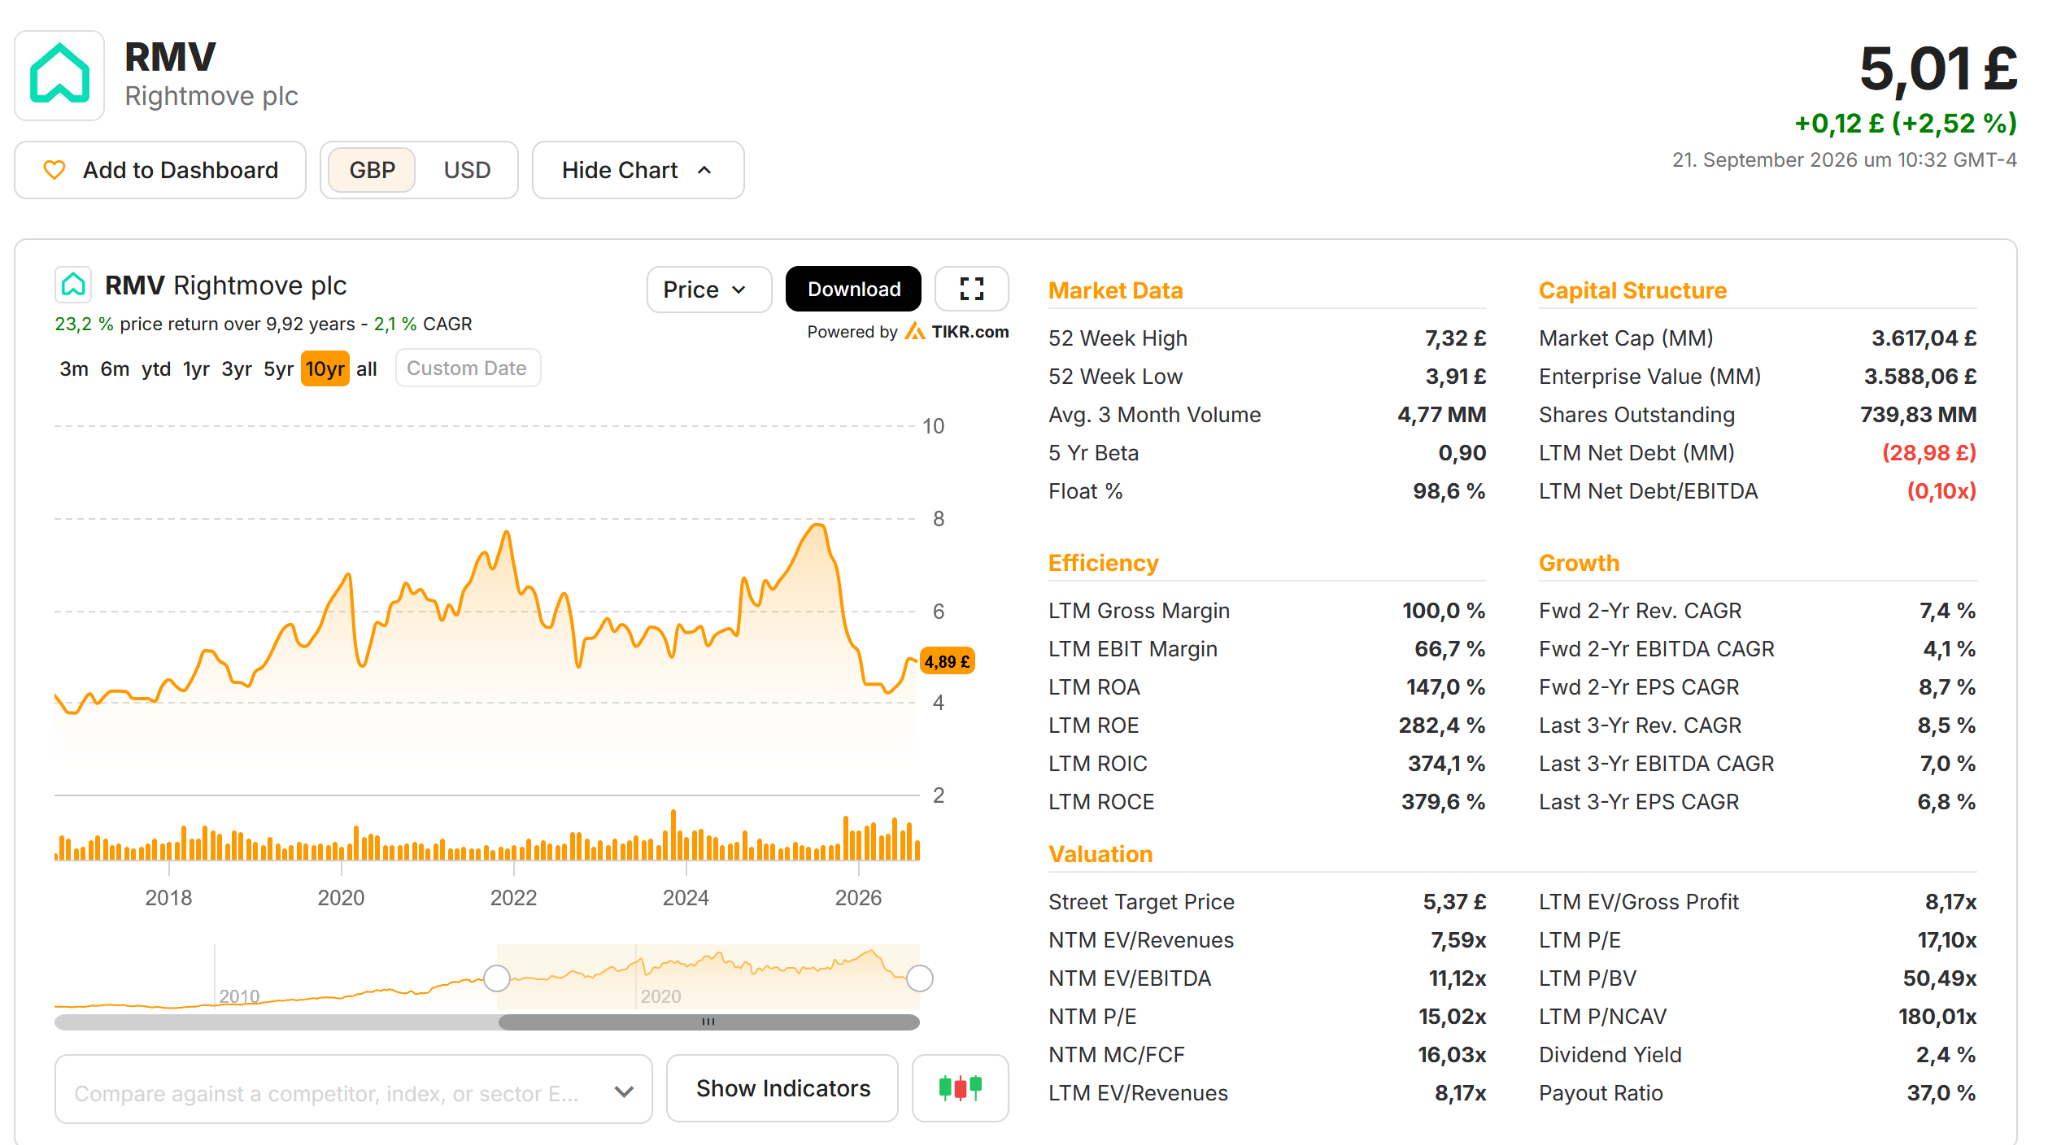
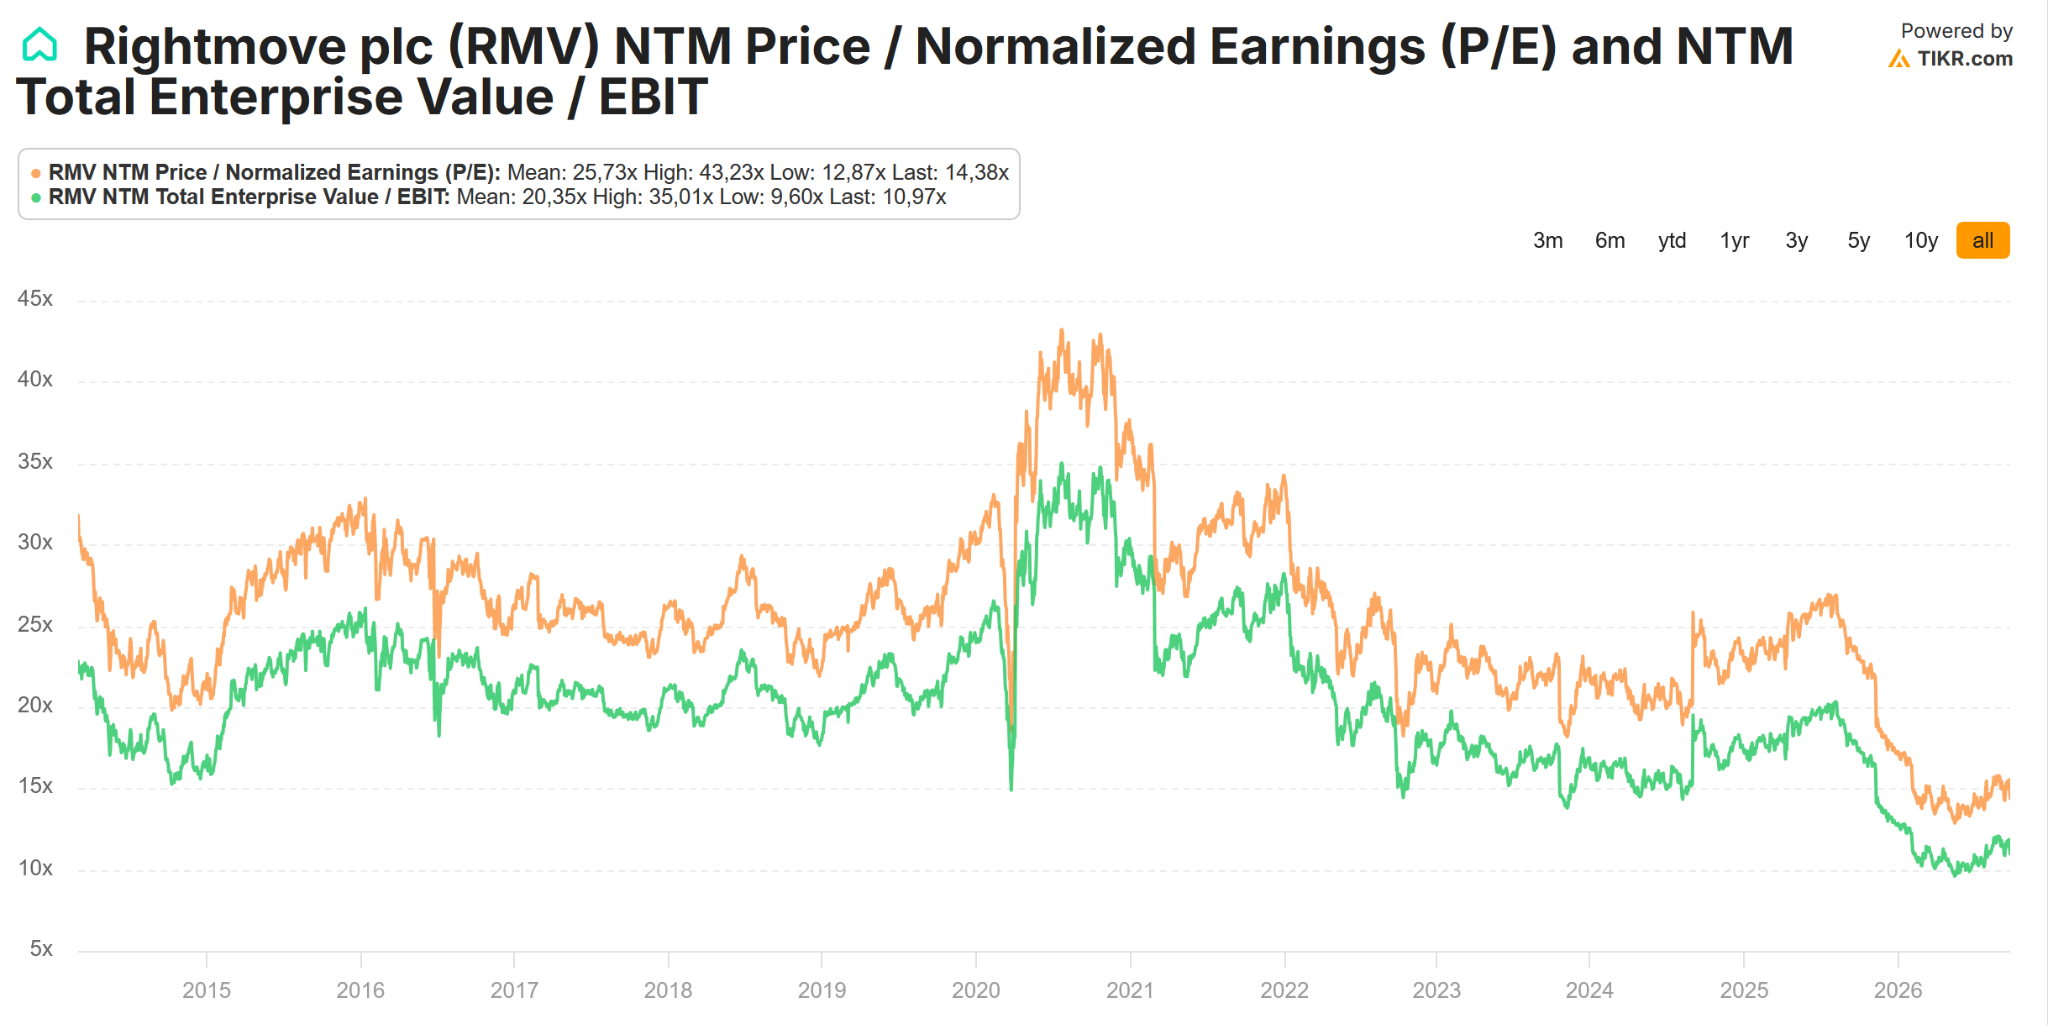
Rightmove is the most profitable of the three and also the most expensive at 15x next year P/E.

In 2024, REA, the “rightmove of Australia” tried to take over Rightmove at a final offer of 7,80 GBP/share but wasn’t successful.

Interestingly, earnings are up between 20-30% depending on which line you look at since then, but the stock is trading at a deep discount to that take-over bid.

The AI Threat:

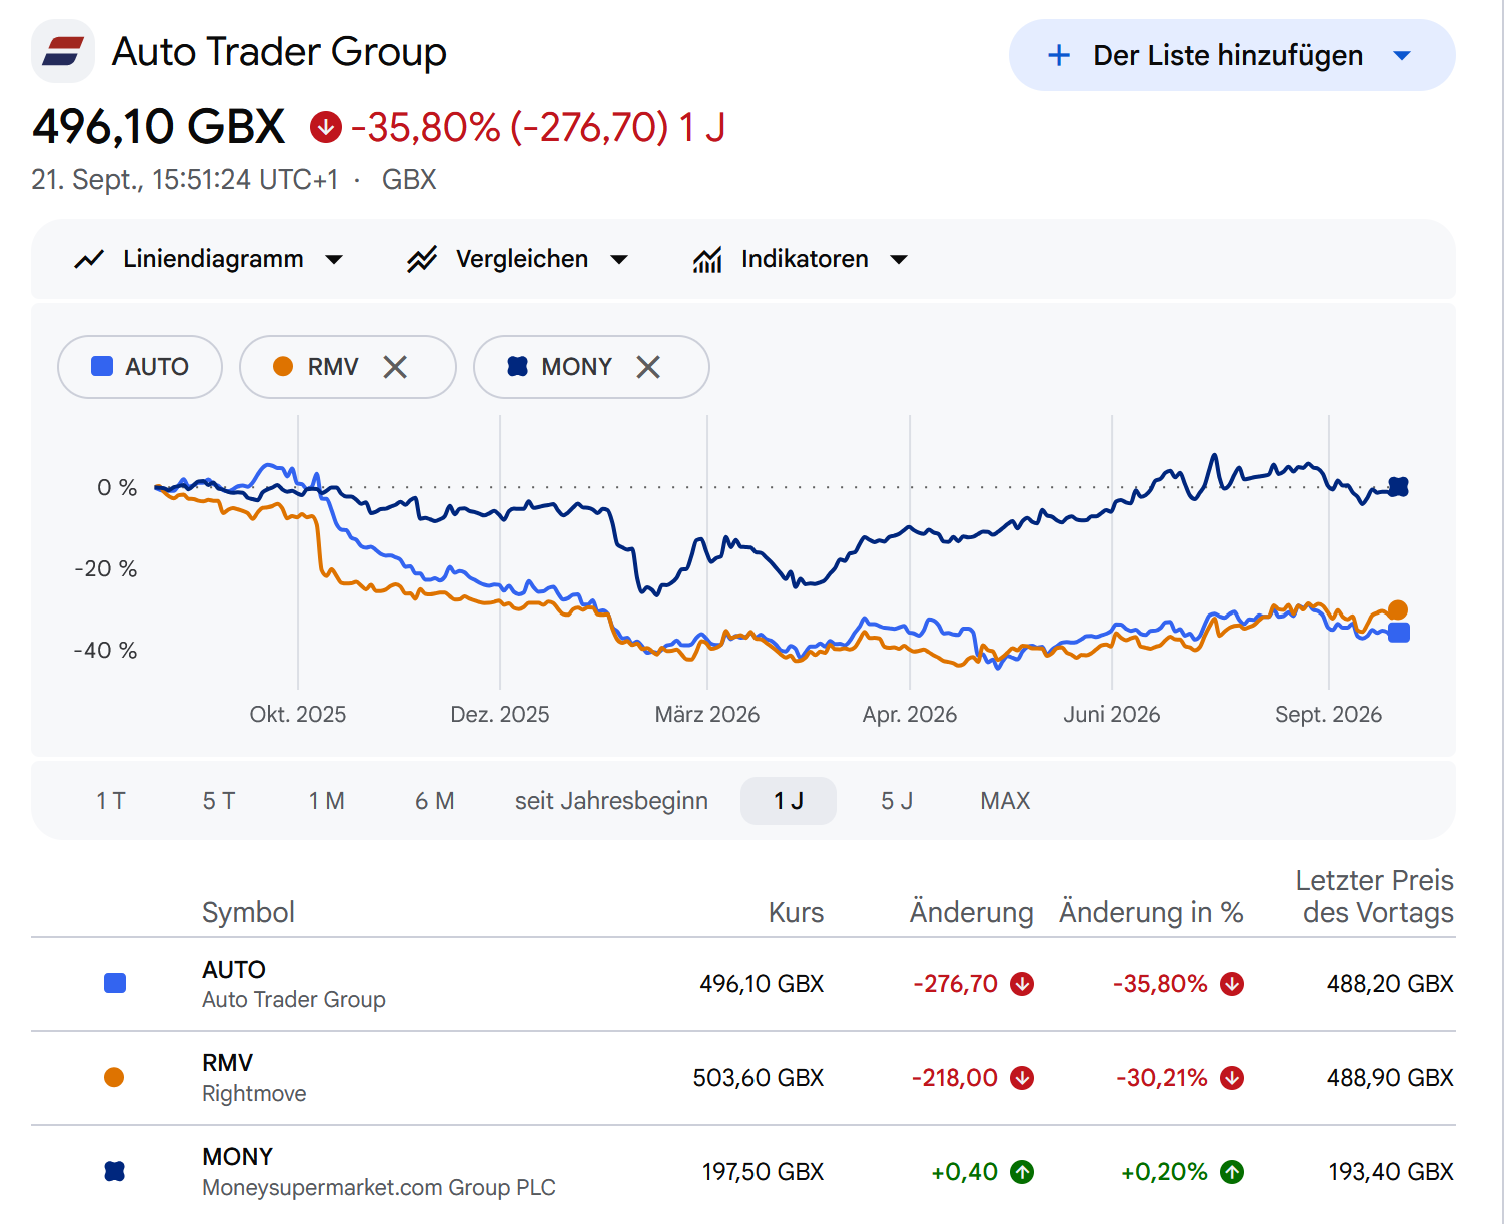
Looking at 1 year charts we can see that especially Autotrader and Rightmove were hit by AI fears, Moneysupermarket a little bit less so:

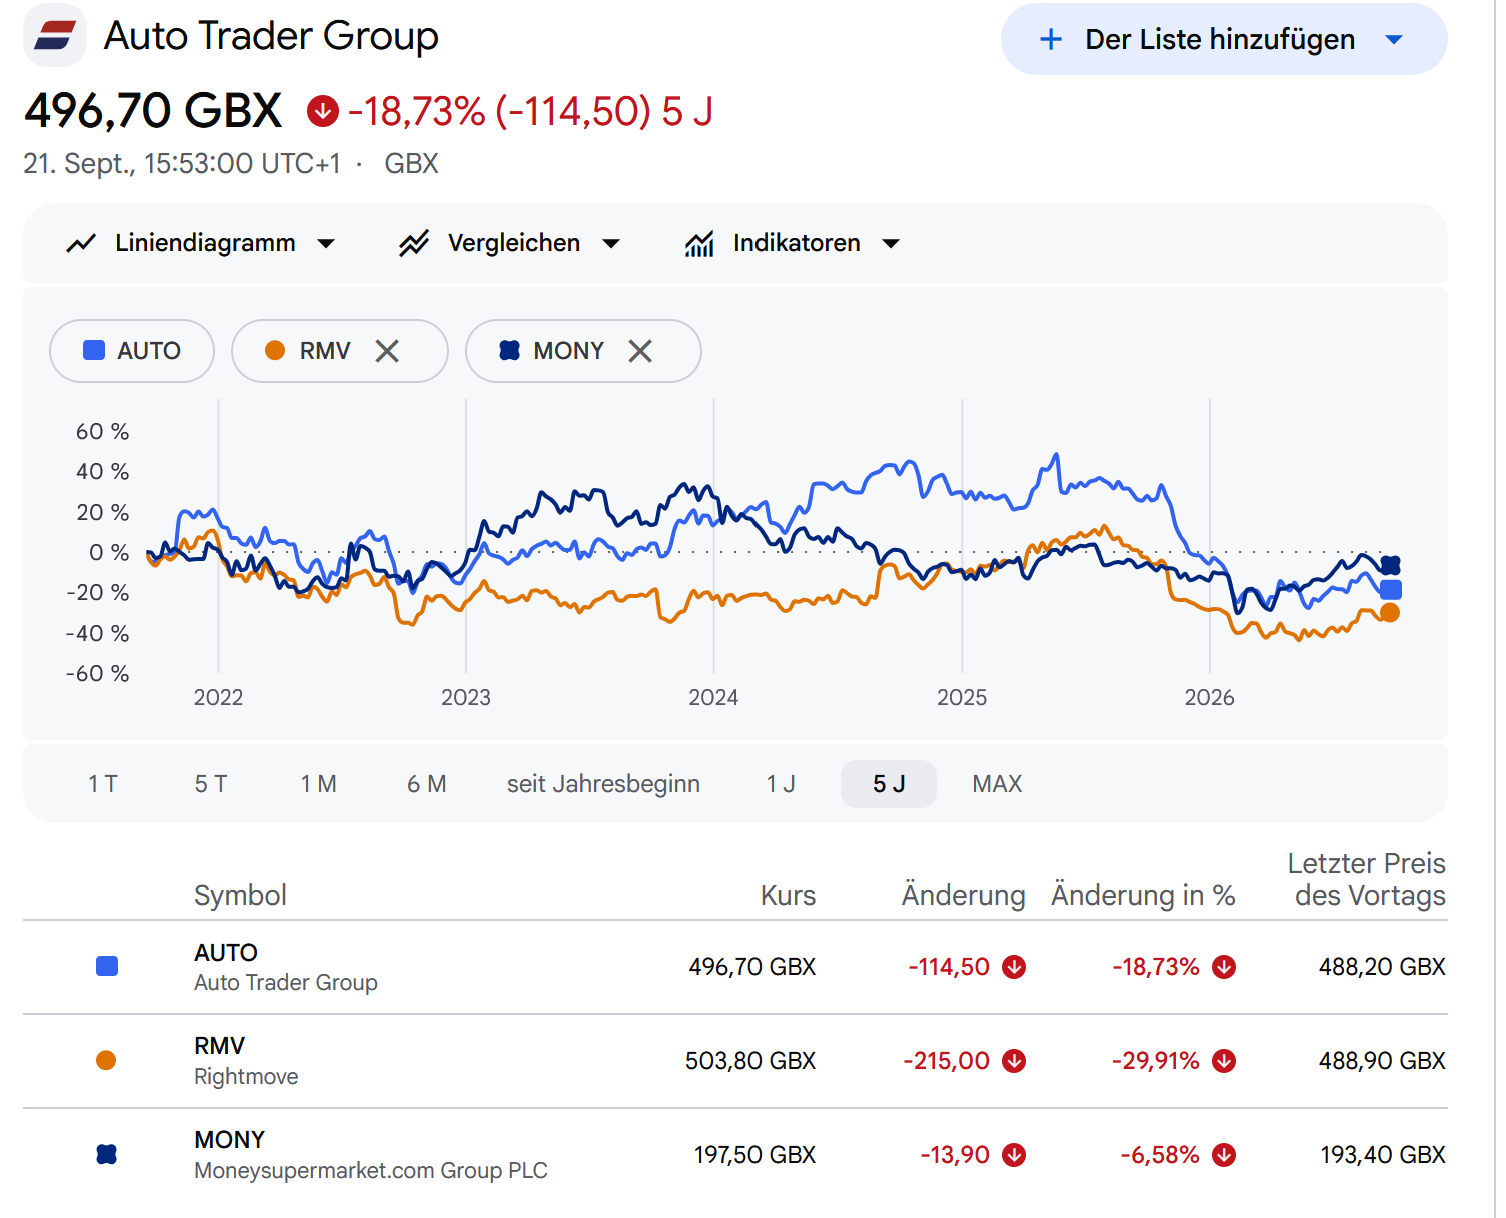
The 5 year chart shows that Moneysupermarket started to struggle earlier, in 2024:

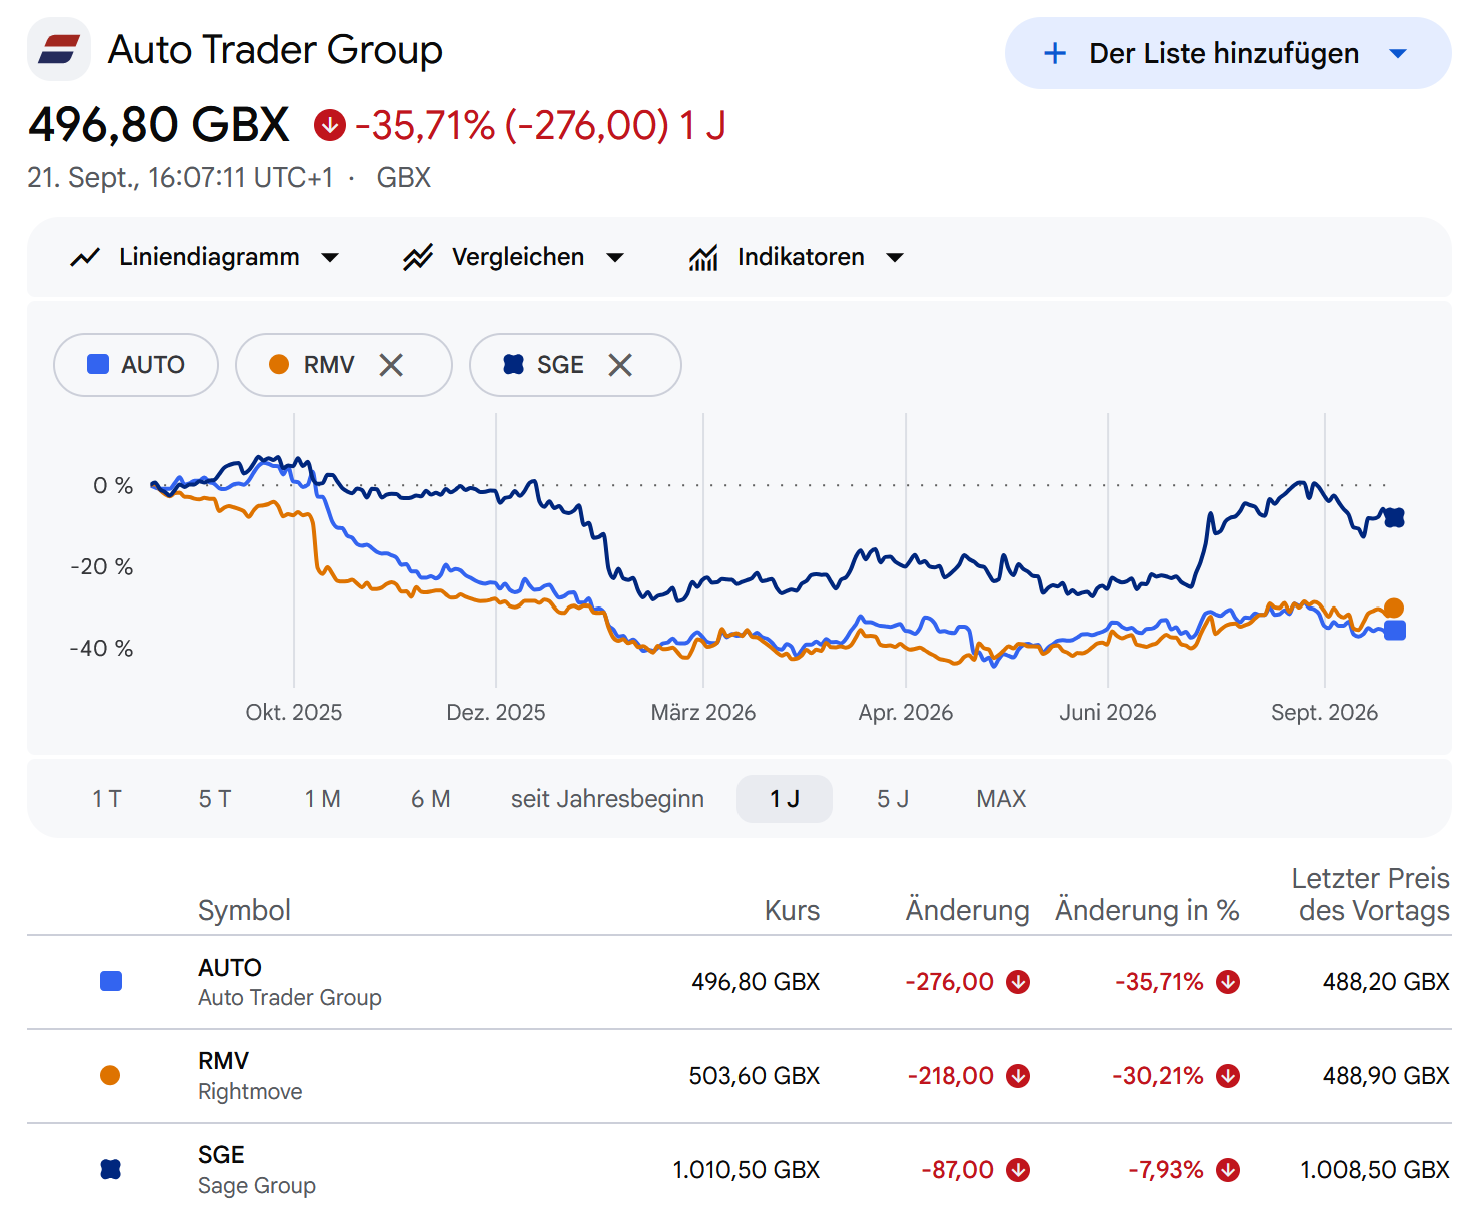
While we are having fun with charts, we can compare Autotrader and Rightmove with Sage, the listed UK Accounting Software company:

Interestingly, Sage has recovered most of its losses in the last 12 months, wile Autotrader and Rightmove so far have not.

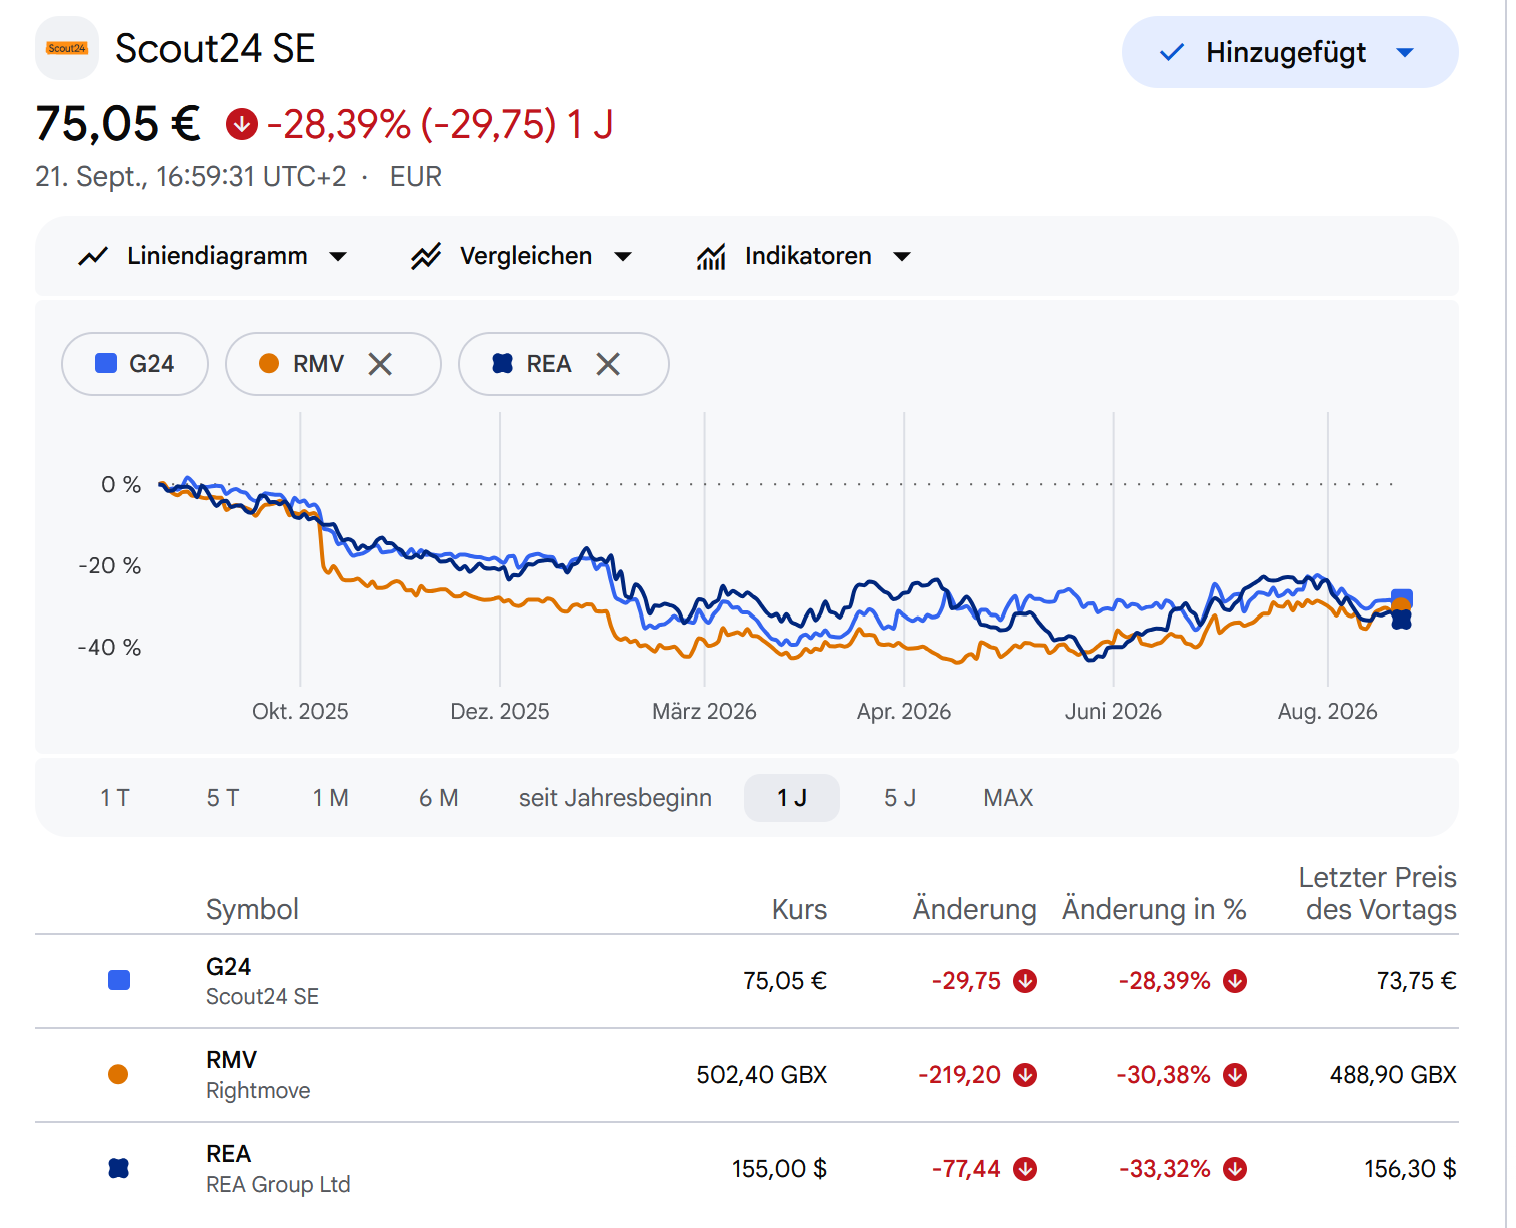
Now to our last Chart comparison. This time Rightmove with Scout24 from Germany and REA from Australia which shows that across geographies, the stock market is really sceptical vs. portals and that this is not only a UK thing:

So the Billion Dollar question here is clearly: Will AI (and especially agents) disrupt the “Two sided marketplace” model and if yes, how fast will this happen ?

Clearly, Vibe coding a new AutoTrader or Rightmove or Moneysupermarket is not so hard. However that leaves you with the main task:

  • how to you motivate, both, corporate and retail clients to move over to the new “platform” quickly ?

Or, will people just go to their favorite chatbot and type in: Please look for a new house and buy it for me ?

In my opinion, the audience of the current platforms could be quite sticky, especially in the case of Rightmove, which to my understanding is only partially about buying a new house and partially just entertainment.

And yes, there will be people going directly through agents but an agent in order to deliver the same result as a good comparison site/market place would need to have the same infrastructure, i.e. connections to companies in order to get the required updated information and access to actually do the transactions.

Not aMUSEd – the Update

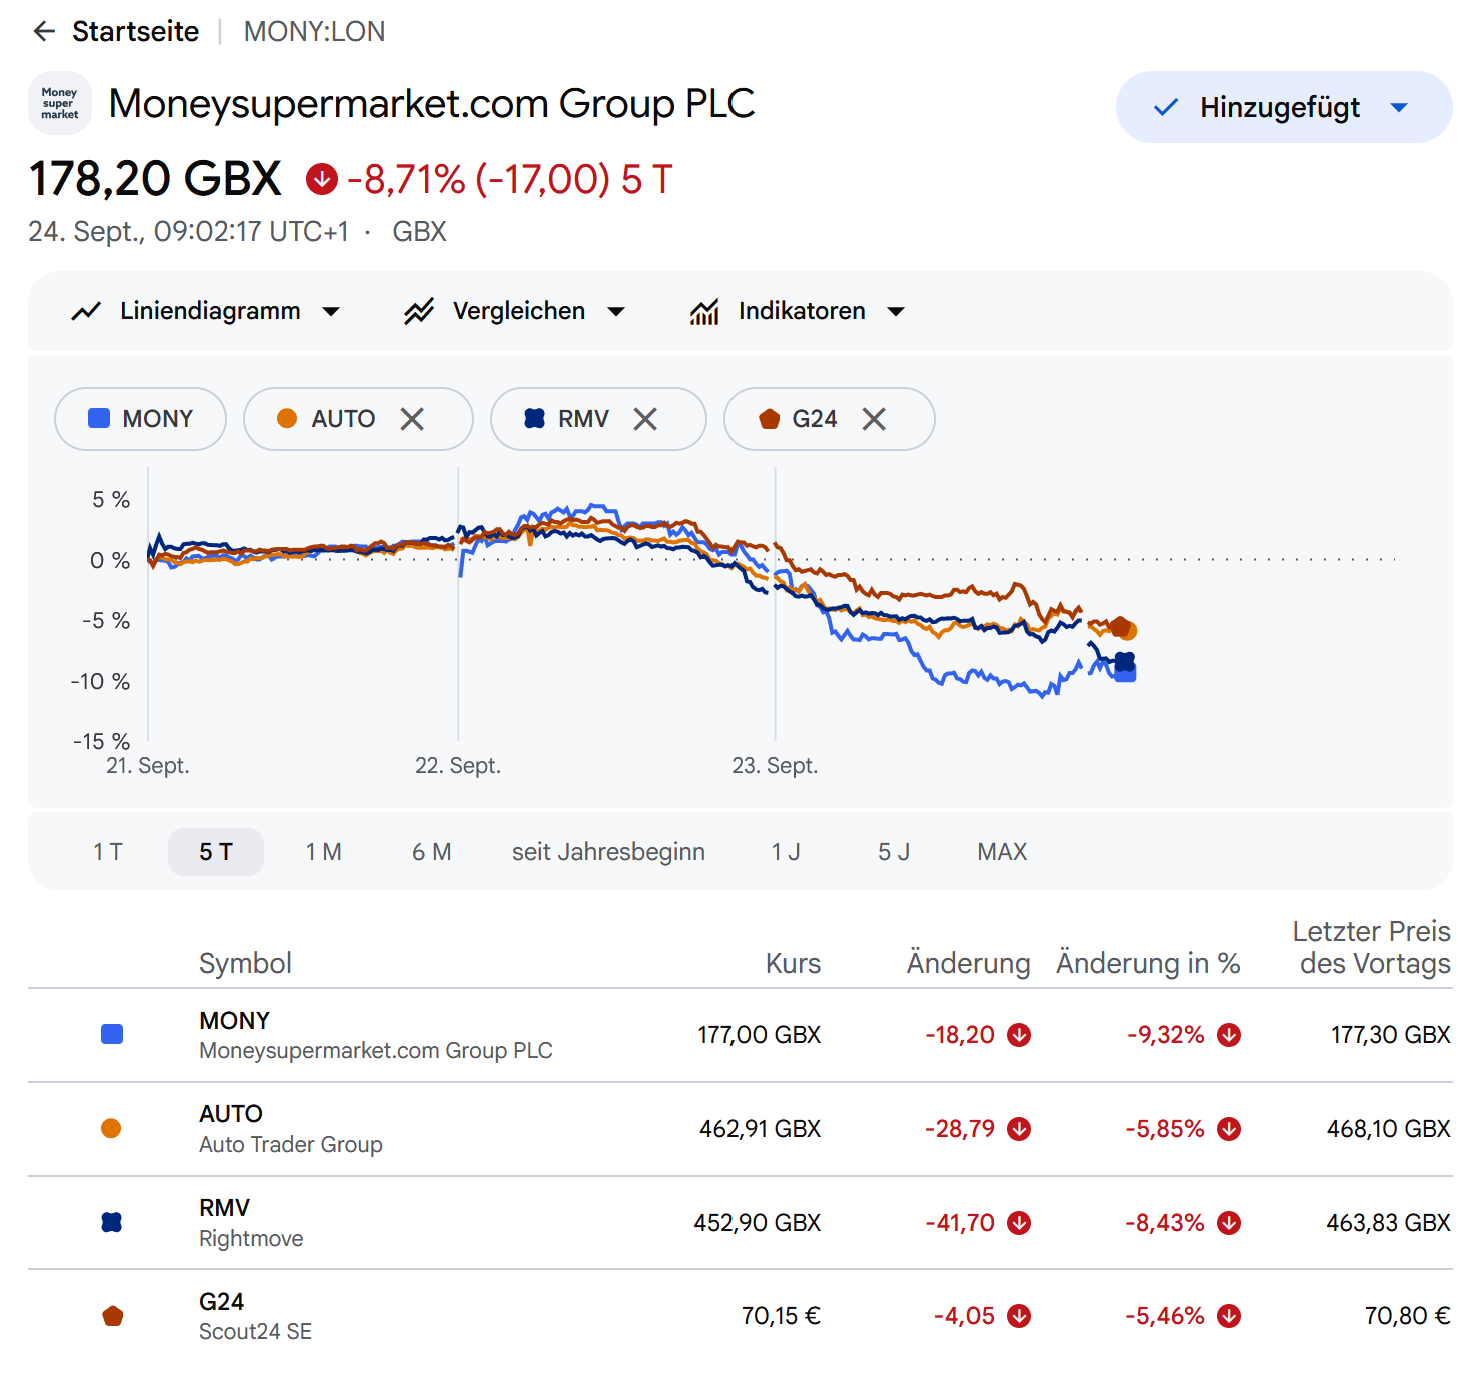
Now while I was writing the above and also starting to build my positions slowly, the share prices of all three stocks (and its peers) started to go down pretty dramatically, as this chart shows:

There was no individual news for those companies but rather the sudden “insight” that Meta’s launch and early success of its Agentic App “Muse” will be a problem for everyone who currently lives from comparing things online. 

Muse is currently only available in the US and has shot up to the number 1 downloaded App over there. 

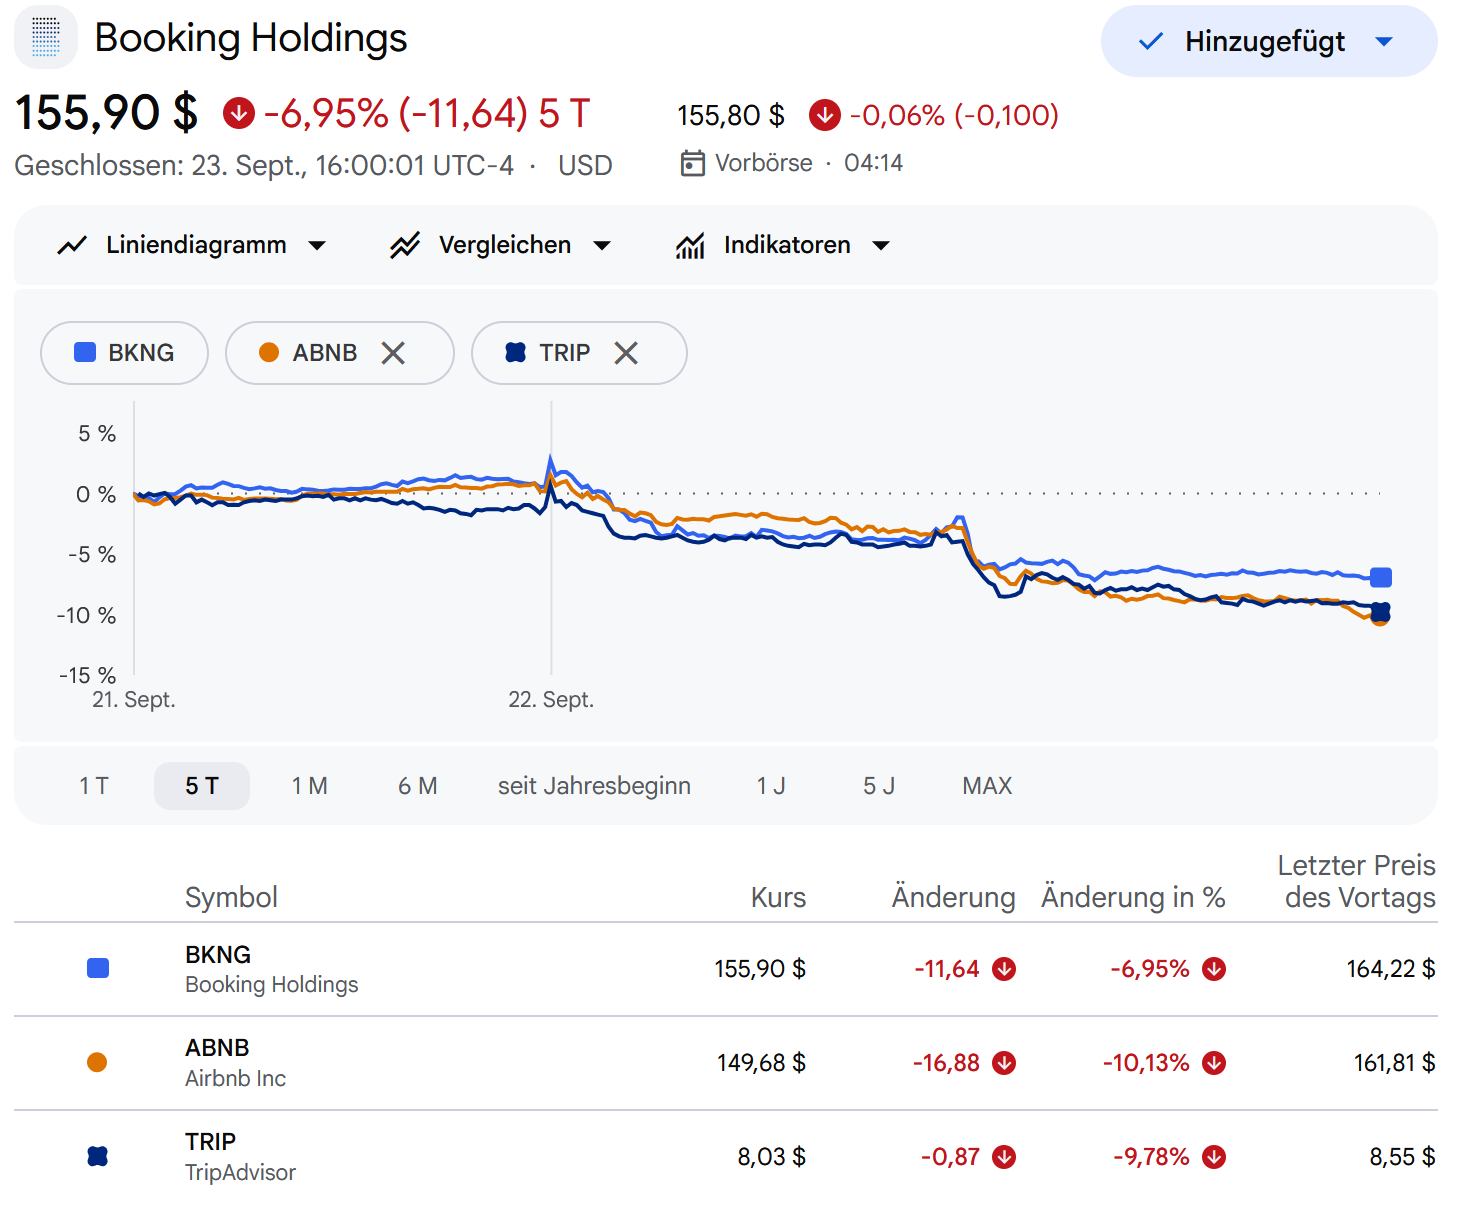
In the past few days, among other stocks, also travel related “aggregator” stocks went down significantly because of this:

The question is clearly: How real is that fear of (short term) disruption ?

I think it makes sense to look at a few “hurdles” for the agentic take-over:

  1. Consumer behaviour US vs. RoW

If we look at Mony Group for instance whose main product is insurance comparison: In the UK, more than 80% of insurance policies are closed/renewed through comparison portals. In the US, this business model is quasi non-existent.

To my understanding, Americans might maybe call one other carrier if they feel that their insurance contract is too expensive, but they would never make the effort to compare their insurance portfolio on a regular basis.

In the UK, this is normal, the same here in Germany. Normally, your favourite portal will know all your relevant details and will actively send you better offers before the old contracts expire. One click and you have cheaper insurance.

So for any active comparison portal user, there is very little to gain by using an AI agent, rather the opposite. And this is before the fact that insurance comparison is a regulated business (as insurance is).

  1. Real time capabilities of LLMs

One thing where at least I struggle a lot with LLMs is to make sure that they really use real time information and not some stale training data. Not sure how they solve it with agents, but I guess that that might still be an issue. Especially if you are looking for a used car or a flat to rent, you need to be really quick for the good deals.

Most portals already offer some kind of “alarm” function for interesting objects. I am not sure if and how AI agents can make sure to have access to the newest offers.

  1. Anti-agent measures 

The most interesting aspect in my opinion will be to see if and to what extent the existing owners of “comparison inventory” will allow AI agents onto their platform. Amazon for instance, has already blocked Muse, which is no surprise as Amaon’s Ad model would be jeopardized. 

Amazon is also smart enough, not to let Meta access its inventory and also its ship infrastructure. 

That’s maybe another point here: At least in the business world, Meta is not your partner of choice. Noone likes them, no one trusts them.

So we could go on and on, but I do not think and especially in “comparison crazy” UK, that AI Agents will be a super fast disruptive force that will make the incubents worthless over night.

But, and this is a big BUT: The stock market could act as this is the case for quite some time.

Whenever the overall AI narrative looks good and AI stocks go up, these stocks, that are perceived as AI losers will go down. No matter if the fundamentals shows something or not.

KPI overview:

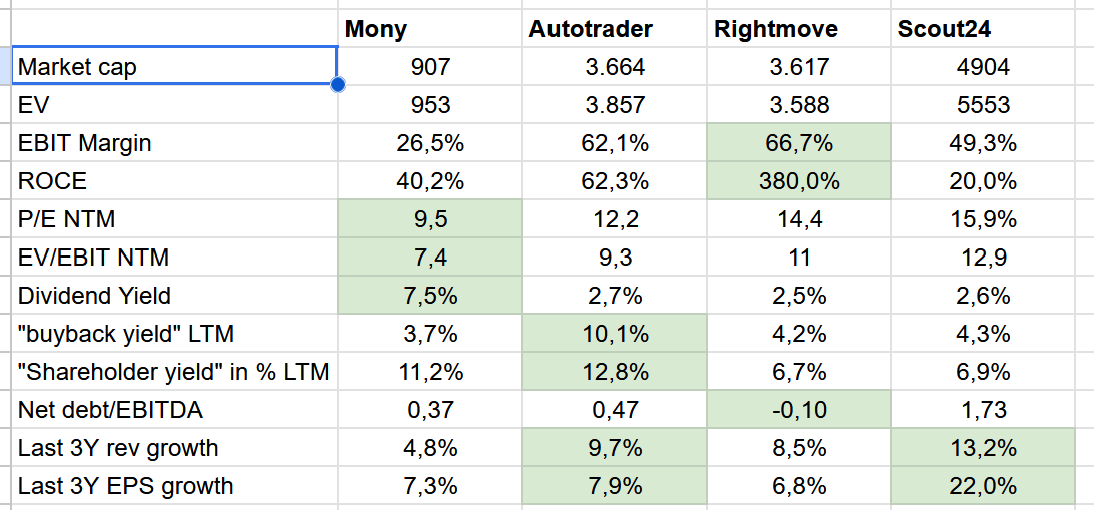
Here is a quick overview of some KPIs that I looked at, including German real estate portal Scout24 which is similar to Rightmove.

We can see that Mony is really cheap, whereas Rightmove is clearly the most profitable. Autotrader is in between with the biggest “buyback yield”.

Scout 24 is clearly more expensive, most likely because growth has been higher than for the UK players, but that is also a risk if AI Agent adoption happens faster than I assume. For this reason and because I wanted UK exposure, I didn’t include them in the basket (yet).

Multiple compression

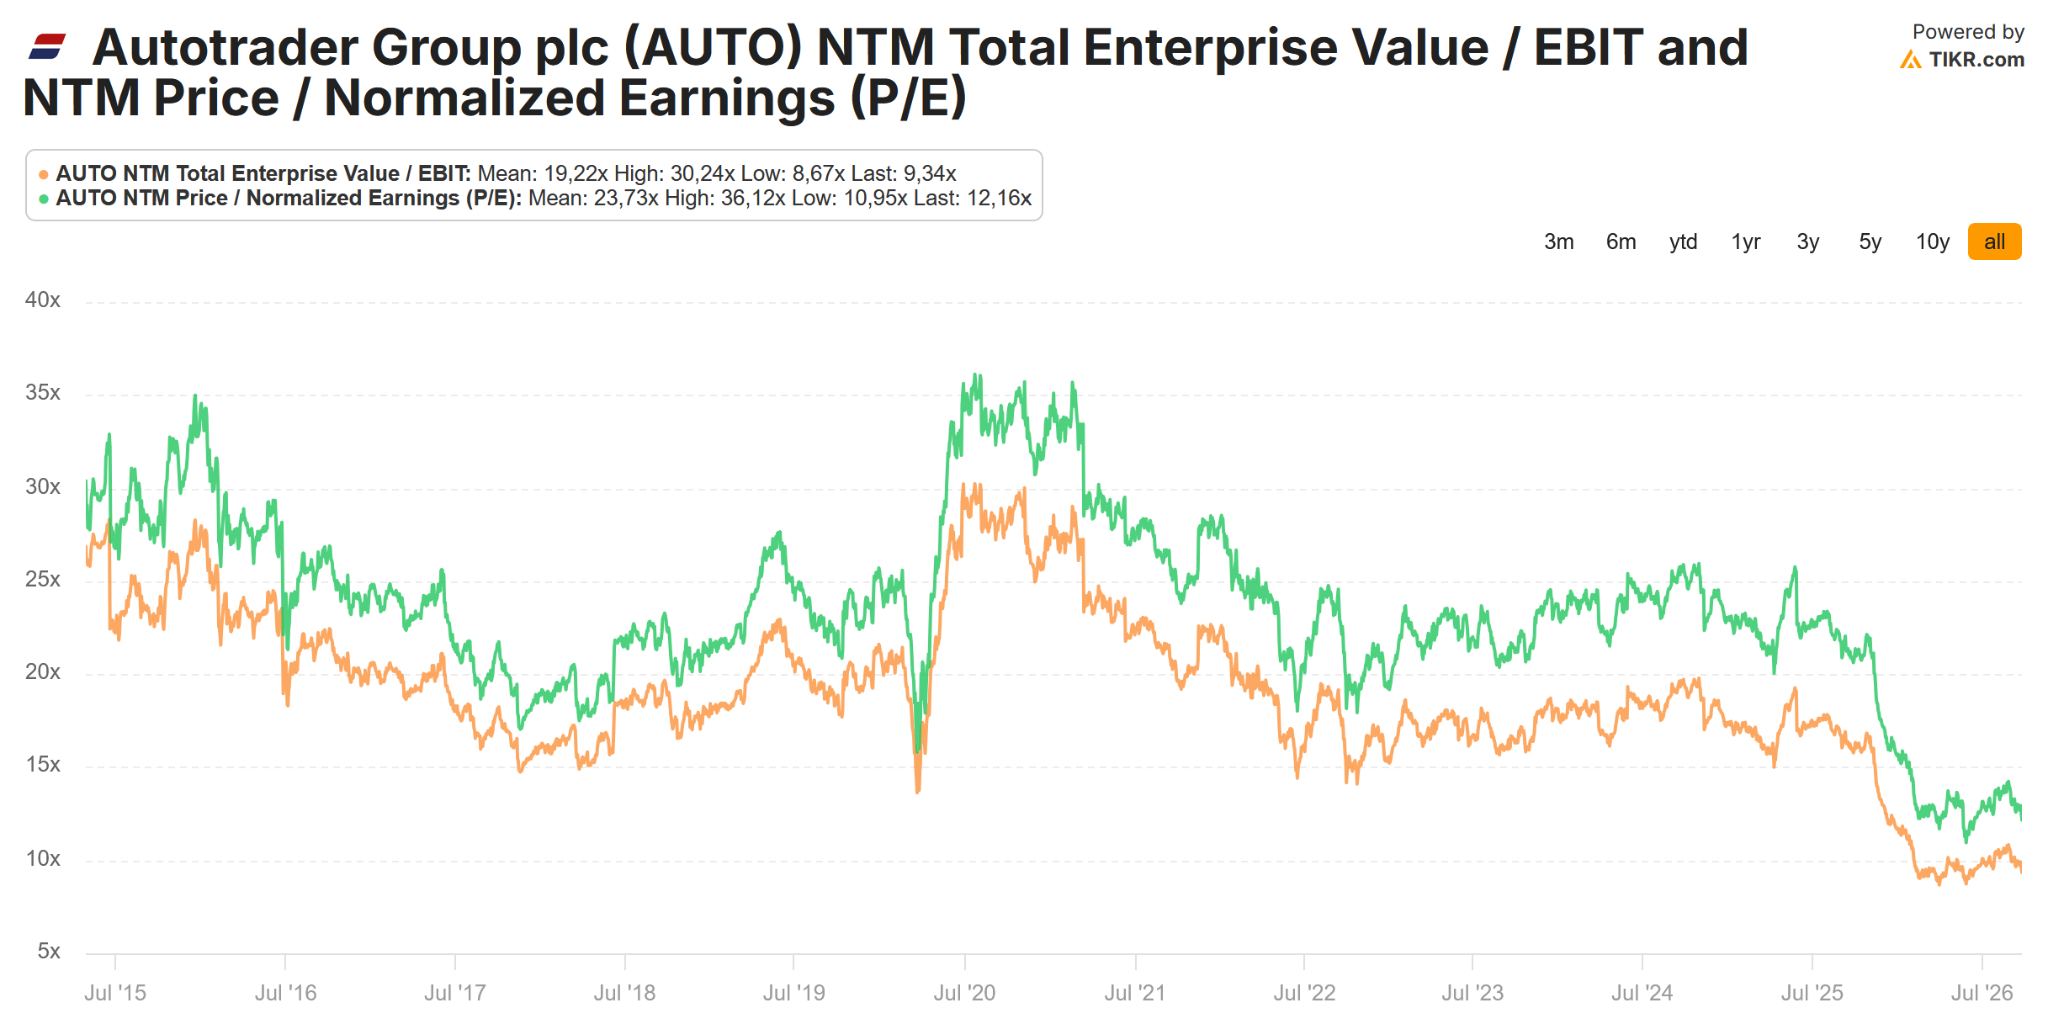
For all 3 stocks, valuation multiples have been compressed significantly. Let’s look at Autotrader first, which was only listed in 2015:

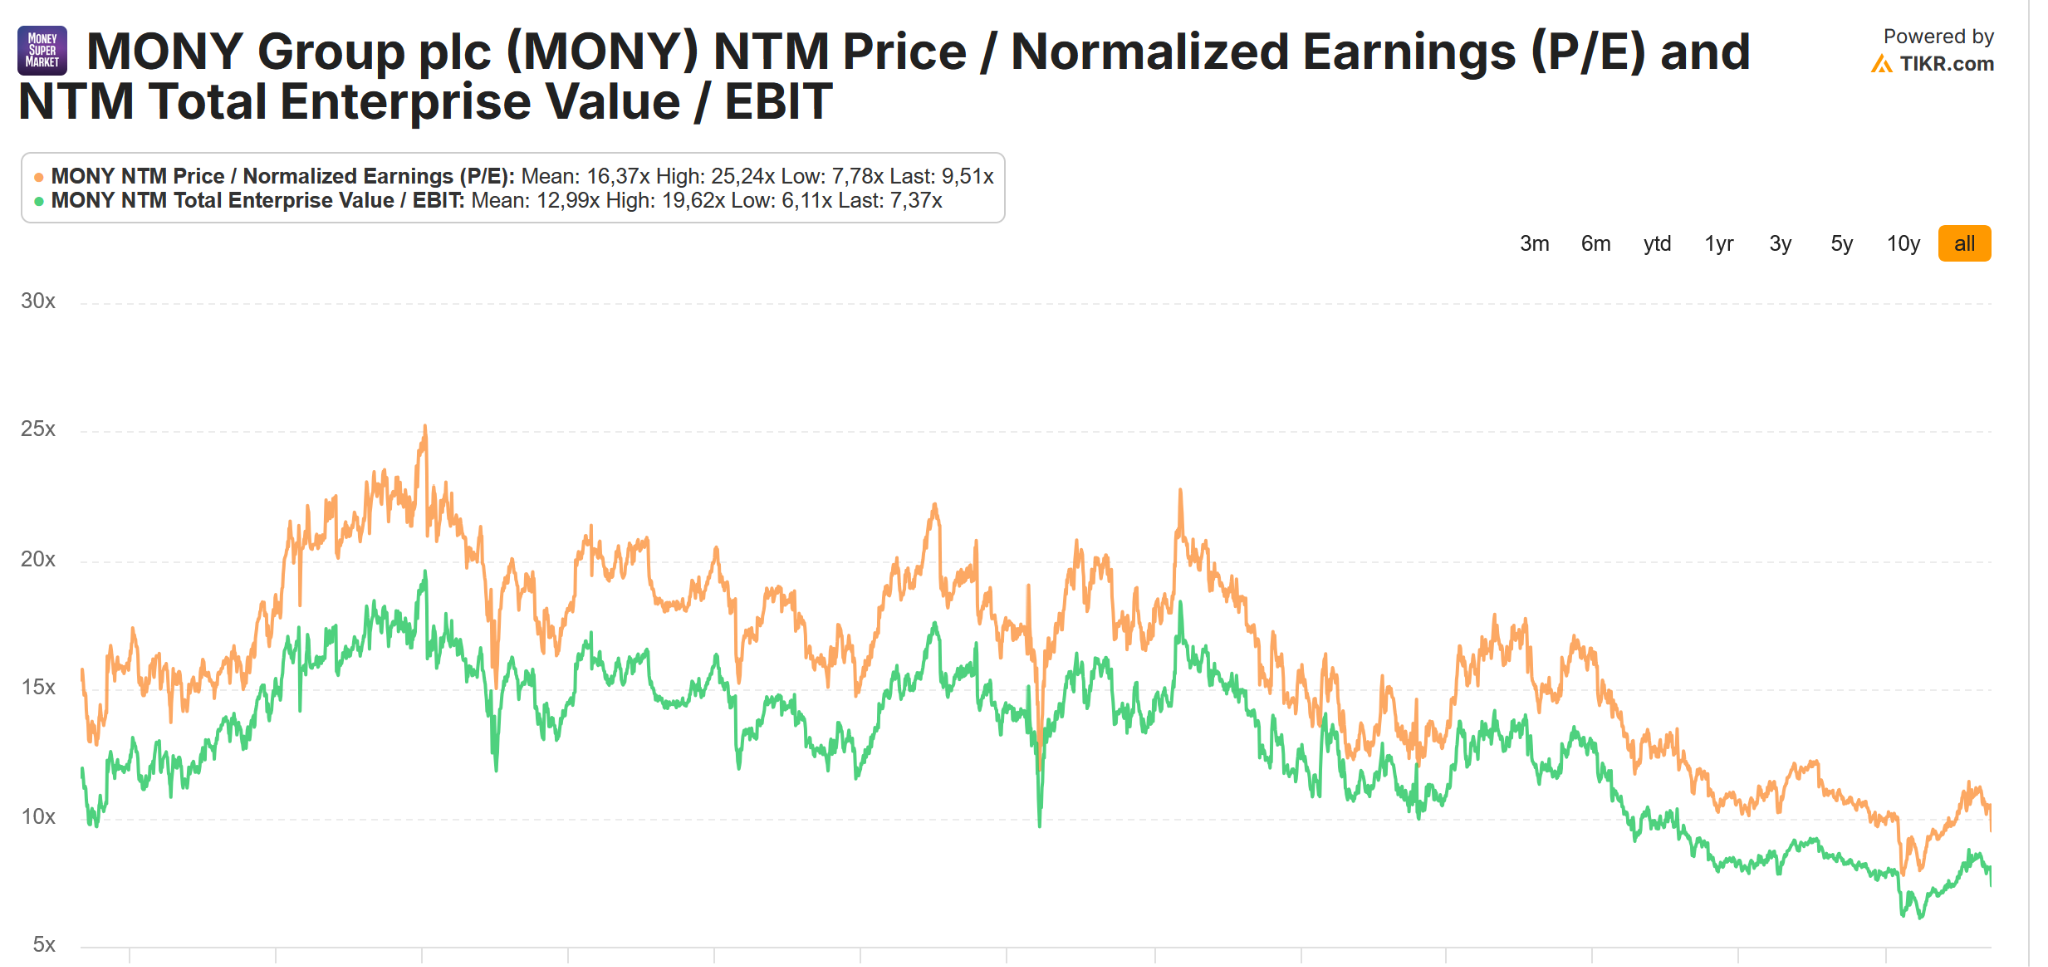
The P/E and EV/EBIT multiples are at absolute lows and at around1/2 of the historical mean.

For Rightmove, this looks very similar:

Money was never that expensive but is also now historically cheap:

While “mean reversion” is not a good investment case as such in a disruptive environment, it clearly shows that the stocks are at least cheap compared to historical valuations. Not that long ago, investors thought that a P/E of 30x is fair for Rightmove.

The Basket:

As a start, I allocated to each UK stock (Mony, Autotrader, Rightmove) 1% of the portfolio, making it a 3% position overall. As purchase price I assume an average price at ~5% above today’s closing price each.

I will need to decide going forward if I either increase the size per stock a little or add maybe a few other UK stocks to the basket. We’ll see. At the moment I might go to 1,5% per stock and have overall maybe 5 UK stocks in that basket.

My time horizon for this trade is  15-18 months and I am looking for an upside of 30-50% in total (including dividends) if some normalization kicks in.

As the performance of my “basket trades” so far was rather mixed (Freedom Energy basket was OK, freedom insulation less so), please wish me luck on this one.

Summary:

Investing into comparison portals aka 2 sided market places at the moment is clearly a “pain trade”. The risk of getting punched in the face short term is quite high.

On the other hand, many of these businesses are extremely high quality and as cheap as they have been for the last 10 or 15 years

For the UK players, based on what we have seen in other areas, the probability of M&A action is not zero and I am also convinced that especially for the UK, the fear of a quick take over through AI agents (Muse) is overblown.

Some links 23/2026

The Slow Compounding substack is “teeing up” a series on 12 less obvious, overlooked serial acquirers

The Quality Stocks Substack with a “Software is not dead” pitch

Warren Buffett now also stepped down as Chairman of Berkshire Hathaway after six decades

For the fans of “special effects accounting”: Prof Meintner on some creative IFRS accounting at Orange 

The AI hype of the Weekend is a new type of model called “Jev”. It’s not as smart as an LLM, but much cheaper, faster and doesn’t hallucinate (Youtube)

Canada has hosted an interesting “invest in Canada” summit last week. Maybe time to look deeper into the Canadian stock market in more depth.

The Bear Cave Substack points out potential problems at Jackson Financial, this time in the form of some Reinsurance Alchemy 

Update Special Situations: Norma, Paypal & NEW: Delivery Hero (No action)

Norma Buyback Tender:

The original write-up is from mid-June and can be found here. Plus a same day update here.

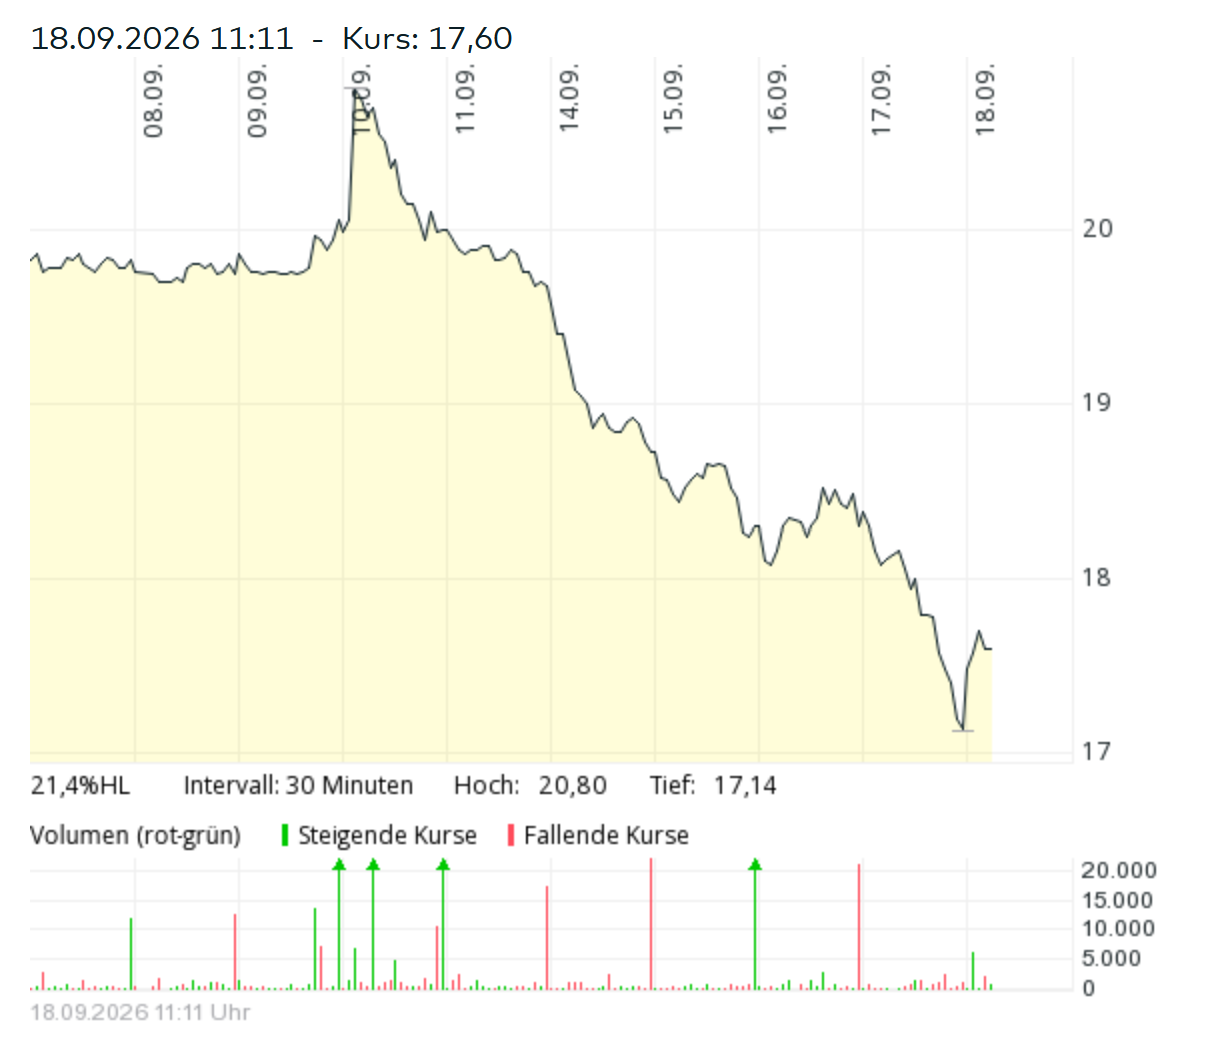
Looking at the share price development, I clearly got out too early from this one at around 18,85 EUR per share plus dividend:

Overall, I was clearly lucky with the timing of the entry. I closed the trade early because first, I could lock in my expected return and secondly, I was a little bit “off grid” and had limited ability to react during the trading period of the tender rights.

The main difference to my initial case was that the tender price had been further increased from 20,87 EUR to 22,35. Interestingly, for the remaining shareholders, this is not really positive as more cash went to selling shareholders.

I had checked a few times during the trading of the tender rights and they were trading relatively close to their intrinsic value.

What I find quite surprising is that at the time of writing, the stock is still trading pretty high above my  “undisturbed” value before the announcement. And how long it took to come down from the “inflated” tender price. I have to confess that I don’t fully understand this.

Paypal Stripe/Advent offer Special Sit:

Here clearly my expectation of a higher bid from Stripe/Advent did not materialize but they rather dropped their effort.

As mentioned in the comments of the original post, I directly sold after this became public as I have no opinion on the longer term development of Paypal. This is what I wrote back then:

However one more thing is important to mention: This is a special situation investment for me. So if for some reason, Stripe & Advent withdraw their bid, I will sell, no matter what. For a “Value investment” I still find Paypal too hard at this stage. 

Luckily for me, the stock did not drop down to the “undisturbed” price of ~45 USD. So I could get out with a relatively modest single digit loss in this case.

I have to admit that I was already feeling a little bit insecure after Stripe closed the OpenRouter acquisition for ~7,5 bn USD a few days earlier. Stripe is a great company but they don’t seem have an unlimited budget for M&A as a financial intermediary.

As in all of these cases, there is always the risk that a case doesn’t work out. In my opinion, the most important part here is to stick to the original plan (i.e. sell) and try to find out if I have made any “a priori mistakes”.

In this case, the only mistake was maybe not to reduce the position after the open router acquisition from Stripe.

For the future, any public take-over situations with Stripe need to trade at a wider discount to account for this episode.

Delivery Hero/Uber take over Special Sit

As mentioned in my weekly links post, the UBER/ Delivery Hero take over could be an interesting Merger “Arbitrage” Special Situation.

In a nutshell, Uber owns currently around 25% of DHR outright and has launched a take-over offer in late August at an offer price of 41,5 EUR.

Expected closing of the deal is in the second half of 2027 and the acceptance hurdle for this offer is only 51% which Uber seems to have in the bag already.

The main risk of the transaction is clearly a relatively complicated merger control and approval process in many countries and especially an intermediate step where part of DHER’s business needs to get carved out and sold to a Private Equity shop called SSW Partners.

At the current share price of 36,85 EUR/share, the “spread” to the 41,50 EUR offer is 12,6%.

This needs to compensate for:

  • a relative long time horizon (long stop November 2027)
  • a relative high premium to the undisturbed price (+100%)
  • and the aforementioned deal complexity

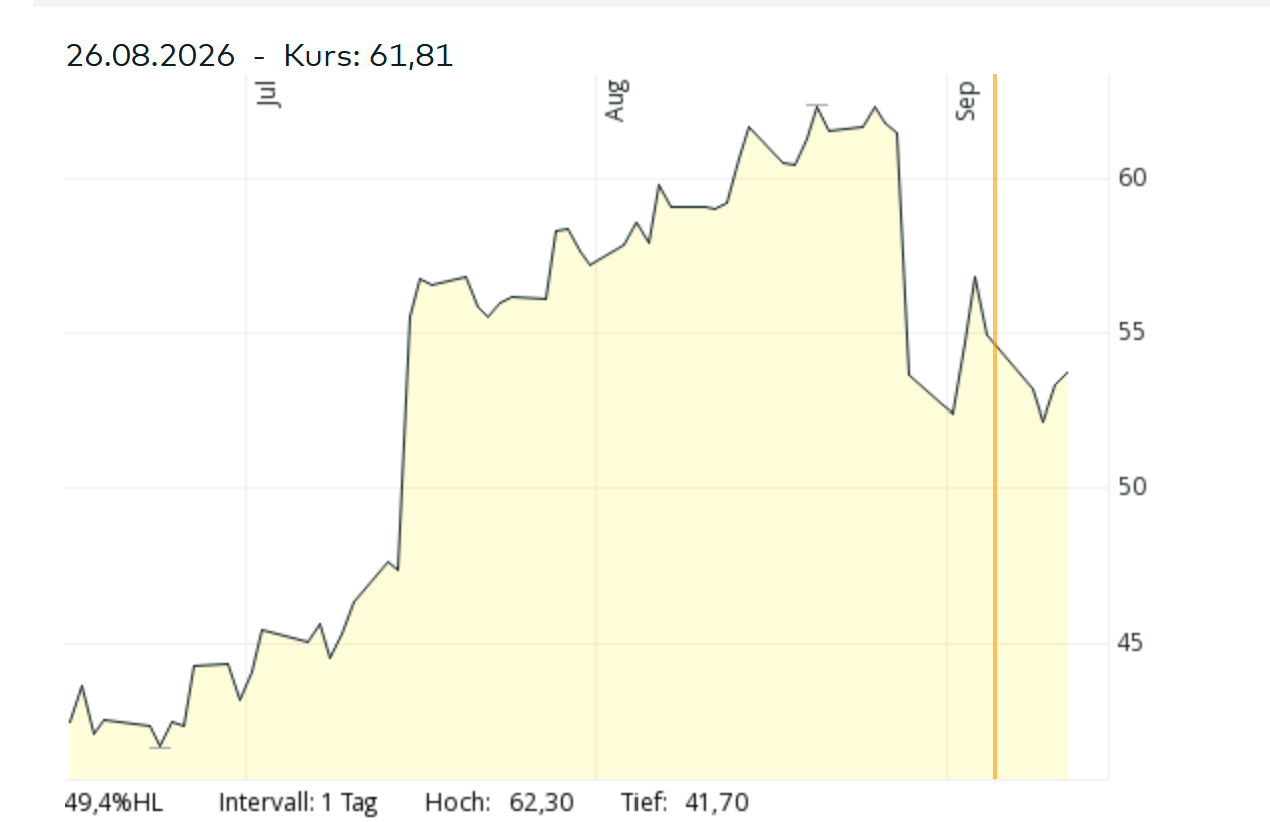
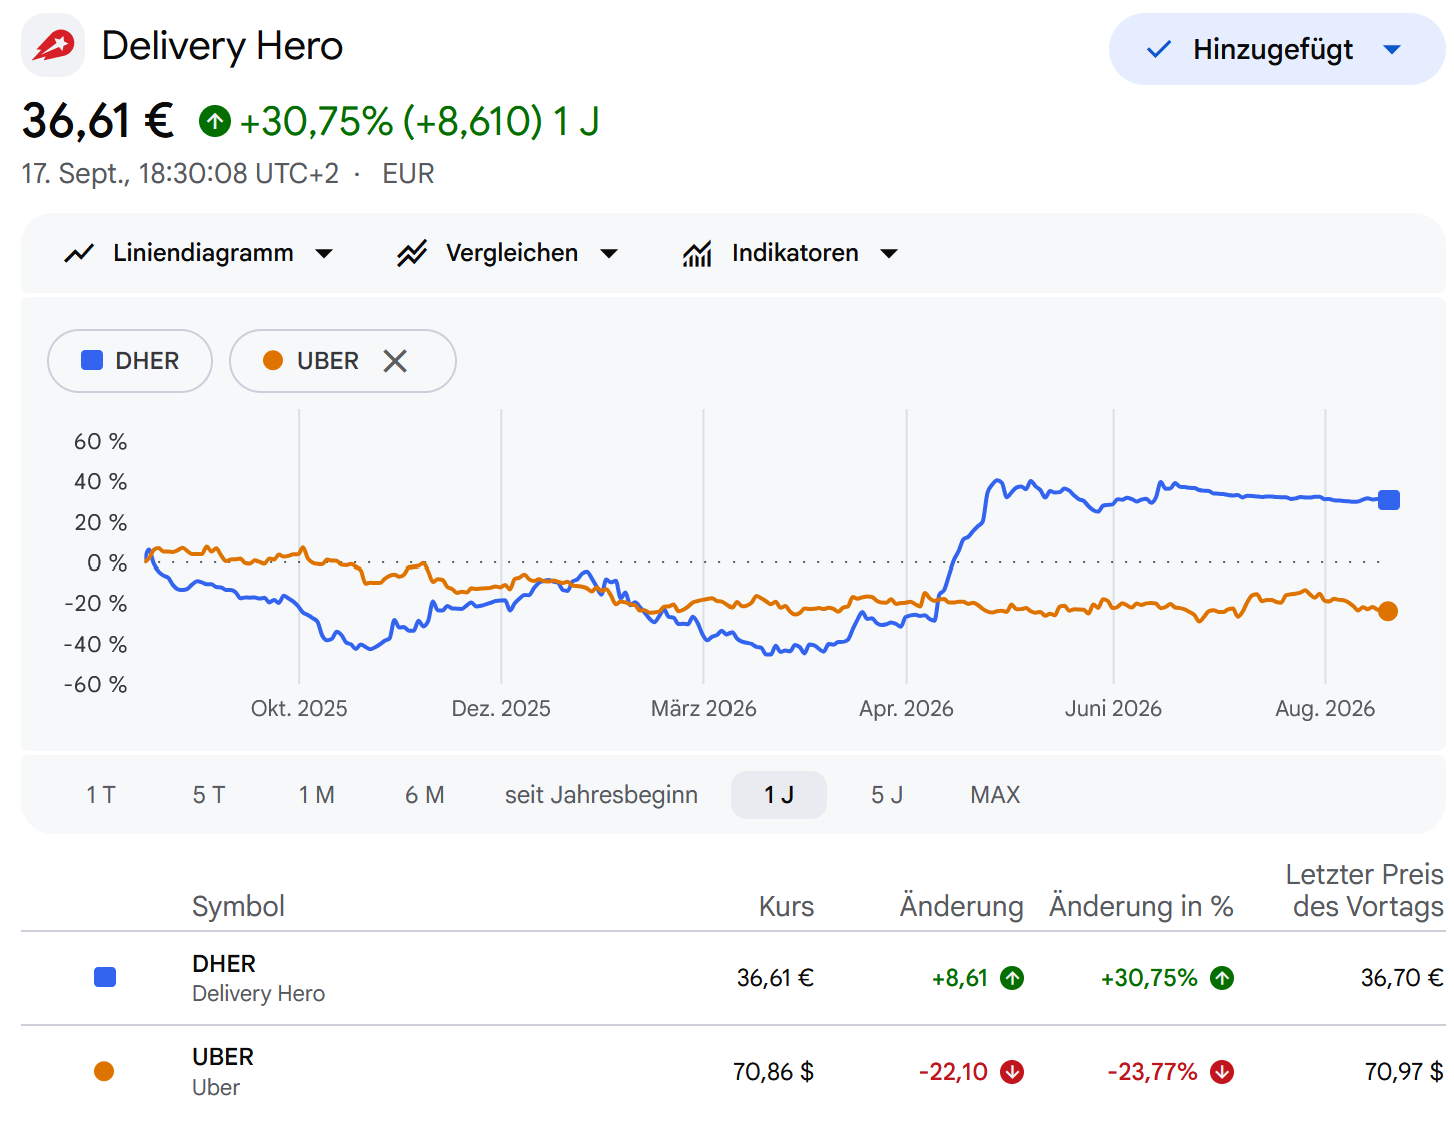
This is the stock chart from Delivery Hero which shows the significant bid premium:

All my 3 AI Tools (Claude, ChatGPT & Gemini) were recommending not to establish a position due the complexity of the deal (carve-out requirement) and the significant downside in a “no deal” scenario if the “cost of capital” is 10 to 15% p.a.

Personally, I think especially countries like UAE or Saudi Arabia could become more risky with regard to merger clearance when the war in Middle East continues to spread.

So in this case I actually follow the advice and sit on my hands. I will revisit this by end of October to see if it has become more attractive, either by a lower price or some fundamental improvements.

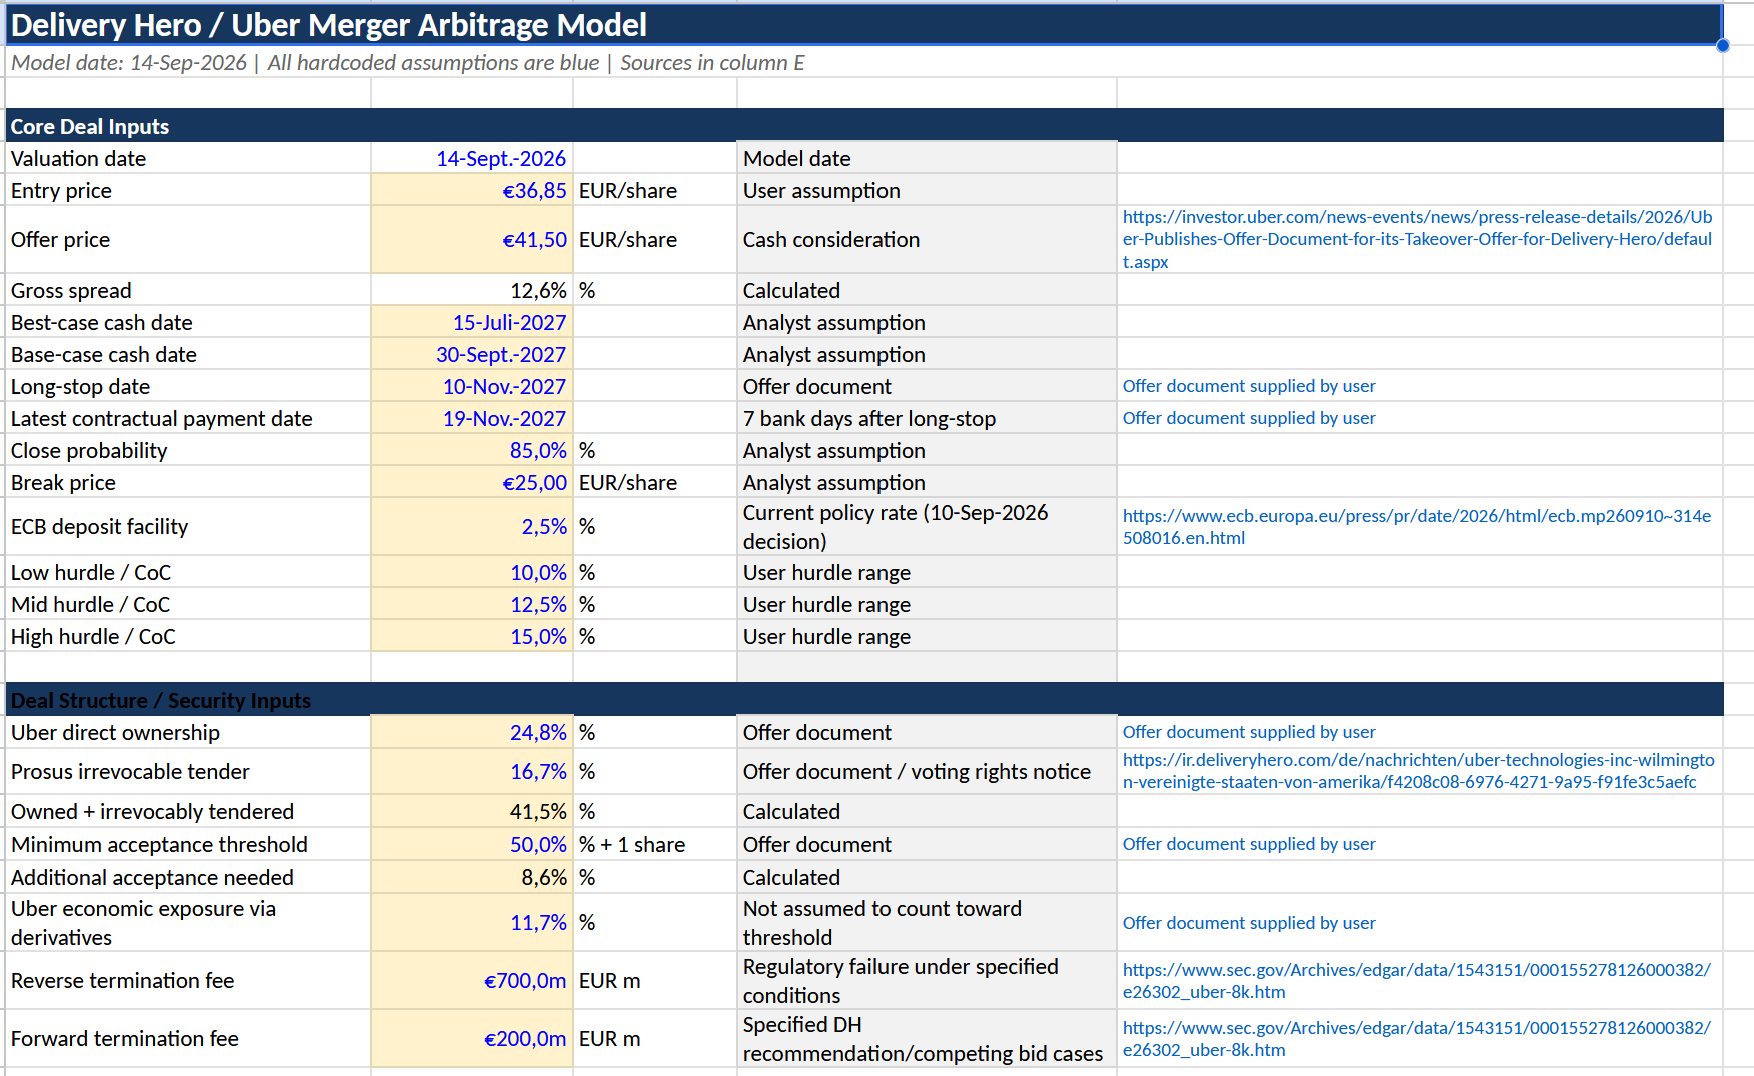
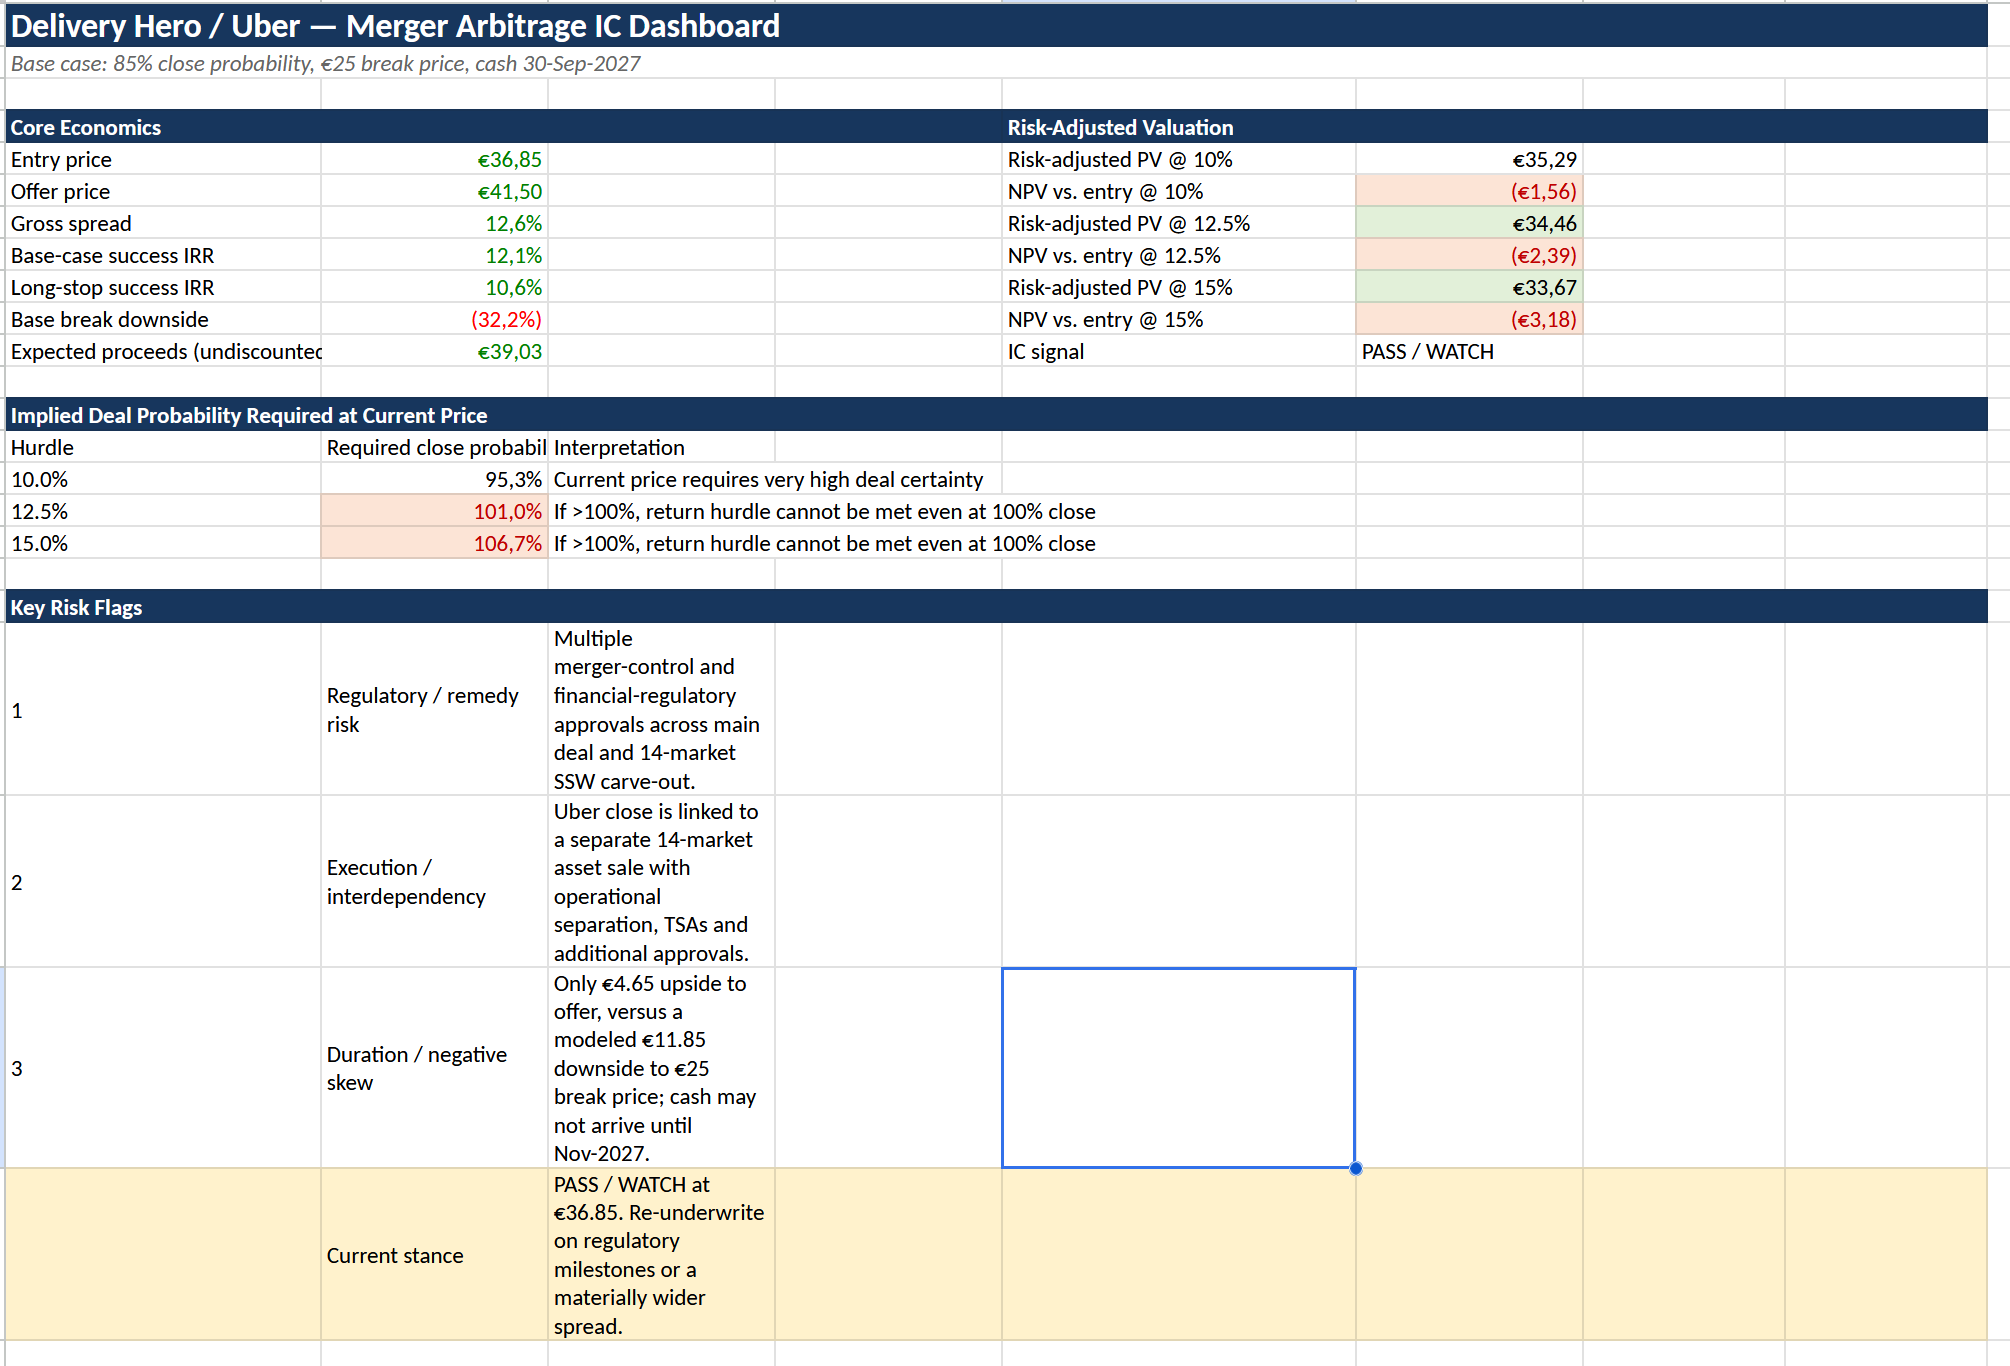
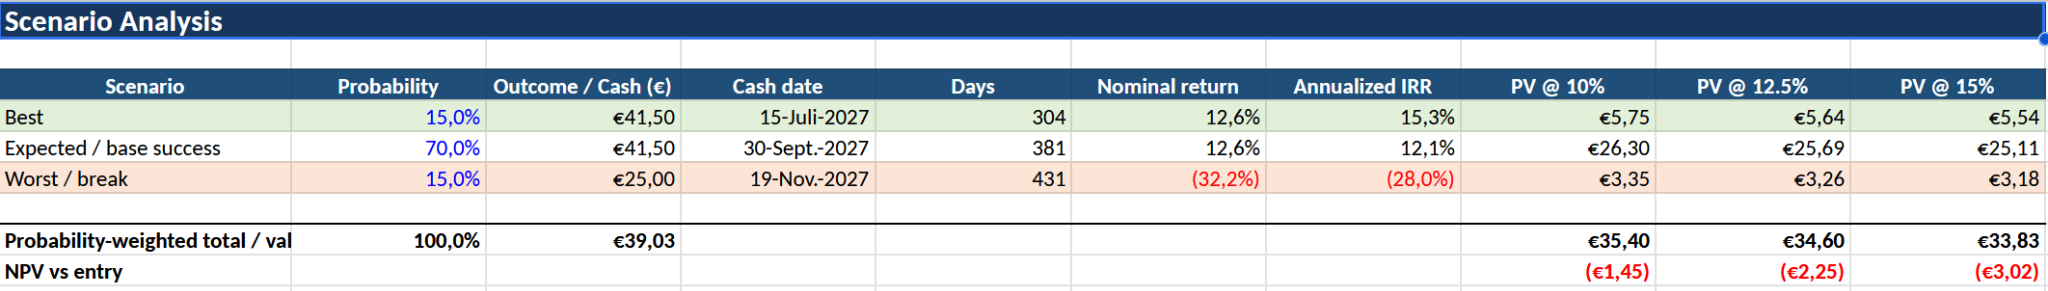
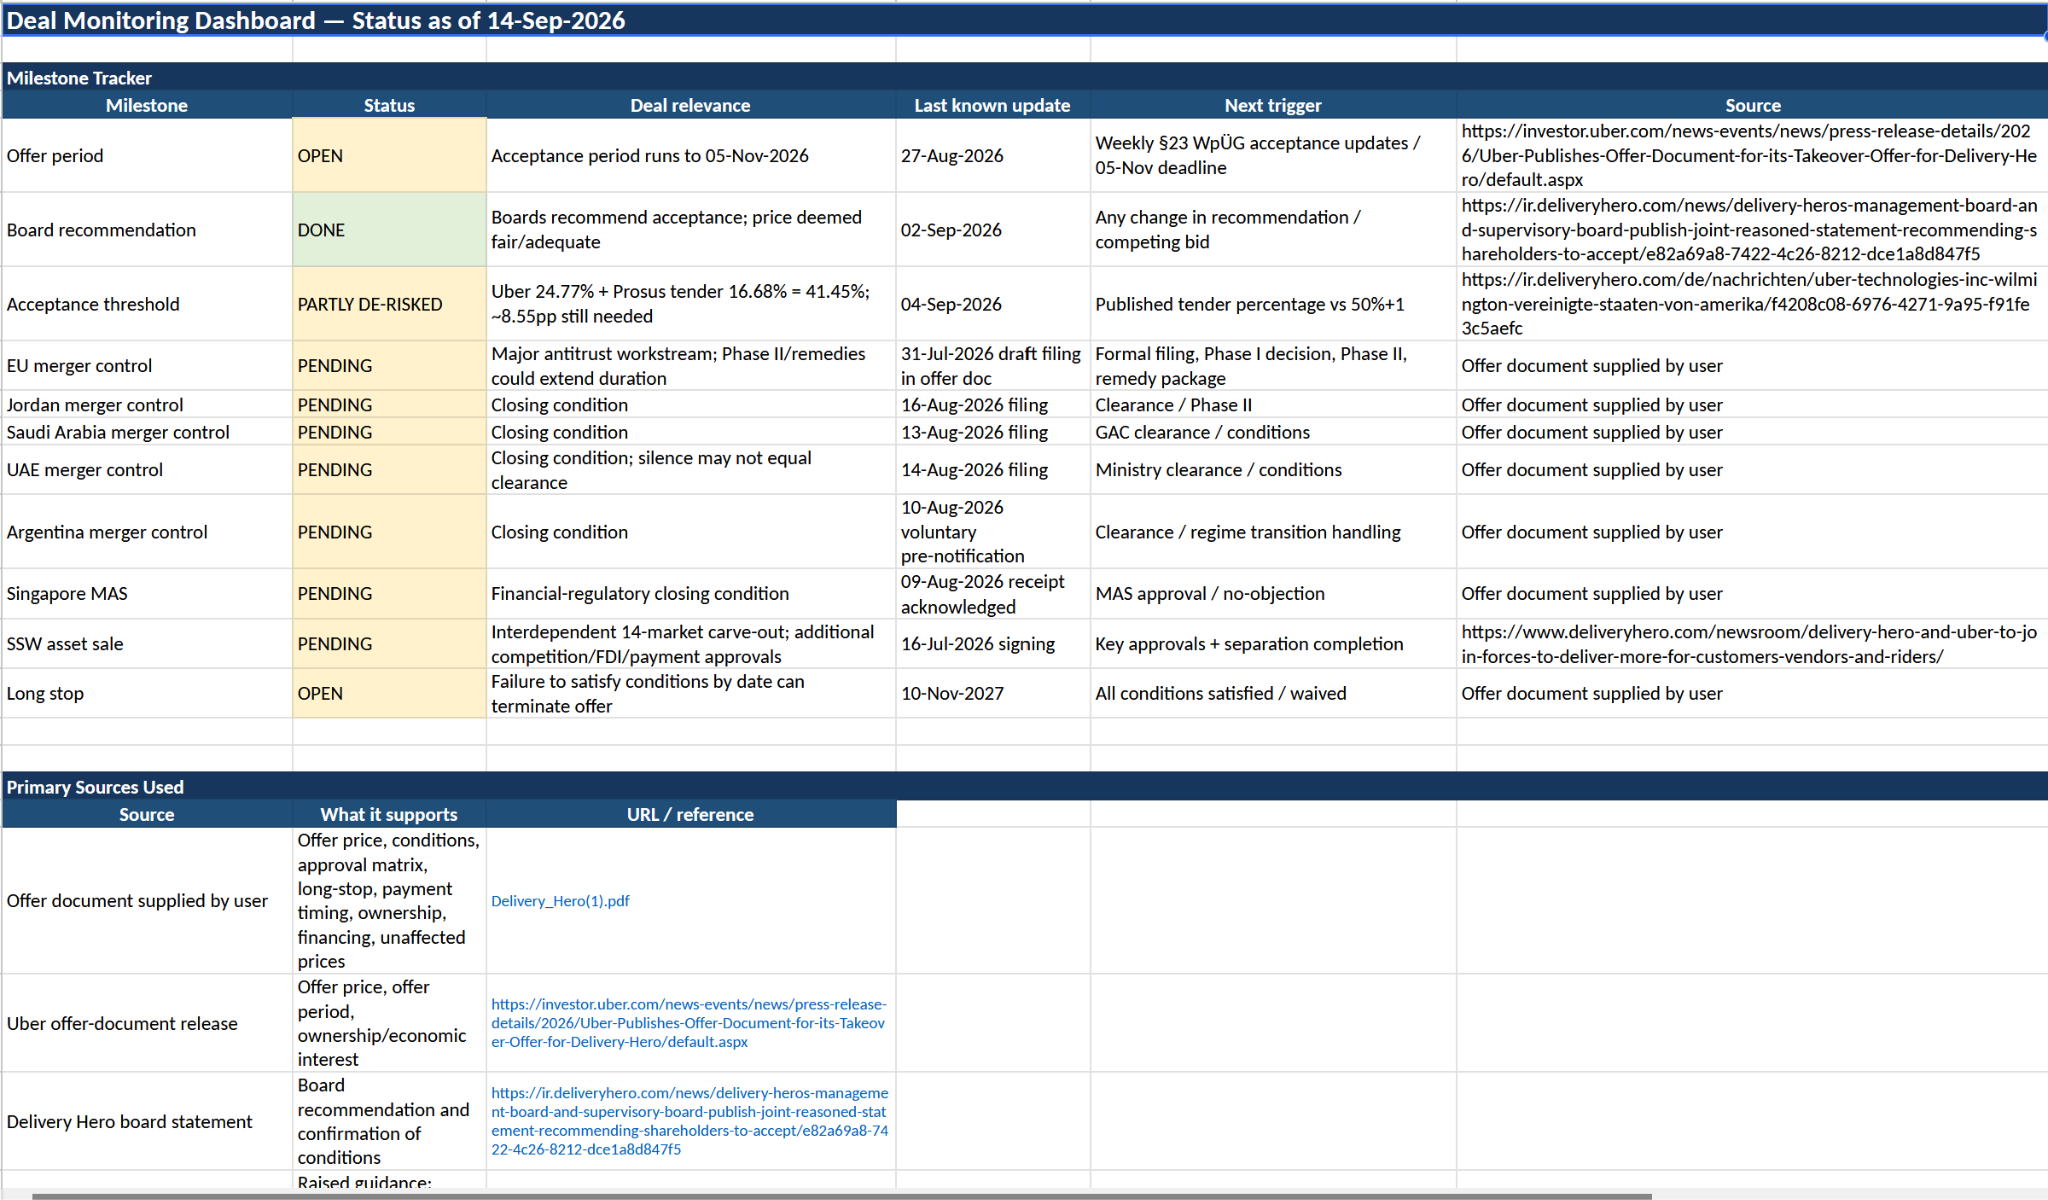
Interestingly, both ChatGPT and Claude offered to build an Excel spreadsheet. Here are some screenshots from ChatGPT which look very professional:

I didn’t check all the formulas, but it seems to be quite good.

In addition, ChatGPT also is checking now 2 times a day for updates.I guess Claude can do the same easily.

Although AI tools don’t change the Special Sit game completely, it clearly makes a more “equal playing field” as it reduces the effort to get into this.

The main risk that I see is that the motivation to actually read relevant documents goes down even more and that it is hard to see if the AI Agent makes mistakes or catches everything.

Some links 22/2026

Dario Amodei’s Essay on “pacing AI development” is worth reading

Also the independent review of the Hugging Face “Swarm attack” is a good but scary read. 

Emerging Value with an overview of interesting Argentinian stocks

Some very interesting insights from Prof Damodaran on Interest rates and stock prices

Andrew Brown (Dynasty) with an update on Belgium Holdco D’ieteren and Belron

Quality Stocks on Uber’s Delivery Hero acquisition (which could in itself be an interesting special sit)

Charlie Huggins with a decent “bucket list” of topics when assessing company culture