Category Archives: Capital Structure Arbitrage

Birkenstock – Cheap enough to be interesting or is it the next Dr. Martens “Fashion Fiasco” ?
Management Summary:

This is a more superficial look into Birkenstock, a much hyped IPO from 2023 which now trades at 12,5x NTM P/E. Despite still growing at “mid teens”, I could not build up the conviction to start a position, as it is really hard to judge for how much longer the “Birkenstock hype” will continue. I also took a quick look at Dr. Martens, which is a prime example for a broken fashion trend. Maybe not directly comparable to Birkenstock, but still a warning sign.

The 2023 IPO “flip”

Birkenstock, the famous German “health sandal” maker went public 3 years ago. The IPO price was USD 46 (upper end of the range) and already on day 1, the stock dropped to around 40 USD.

Interestingly, the PE investor L. Catterton only bought Birkenstock in 2021. Back then it was estimated that the purchase price was ~4 bn EUR. So IPOing in 2023 is a pretty “quick flip” in PE terms.

In between, things looked a little bit better and the stock reached ~60 USD in 2024. Fast forward to today, and the stock trades at around 32 USD at quite cheap multiples:
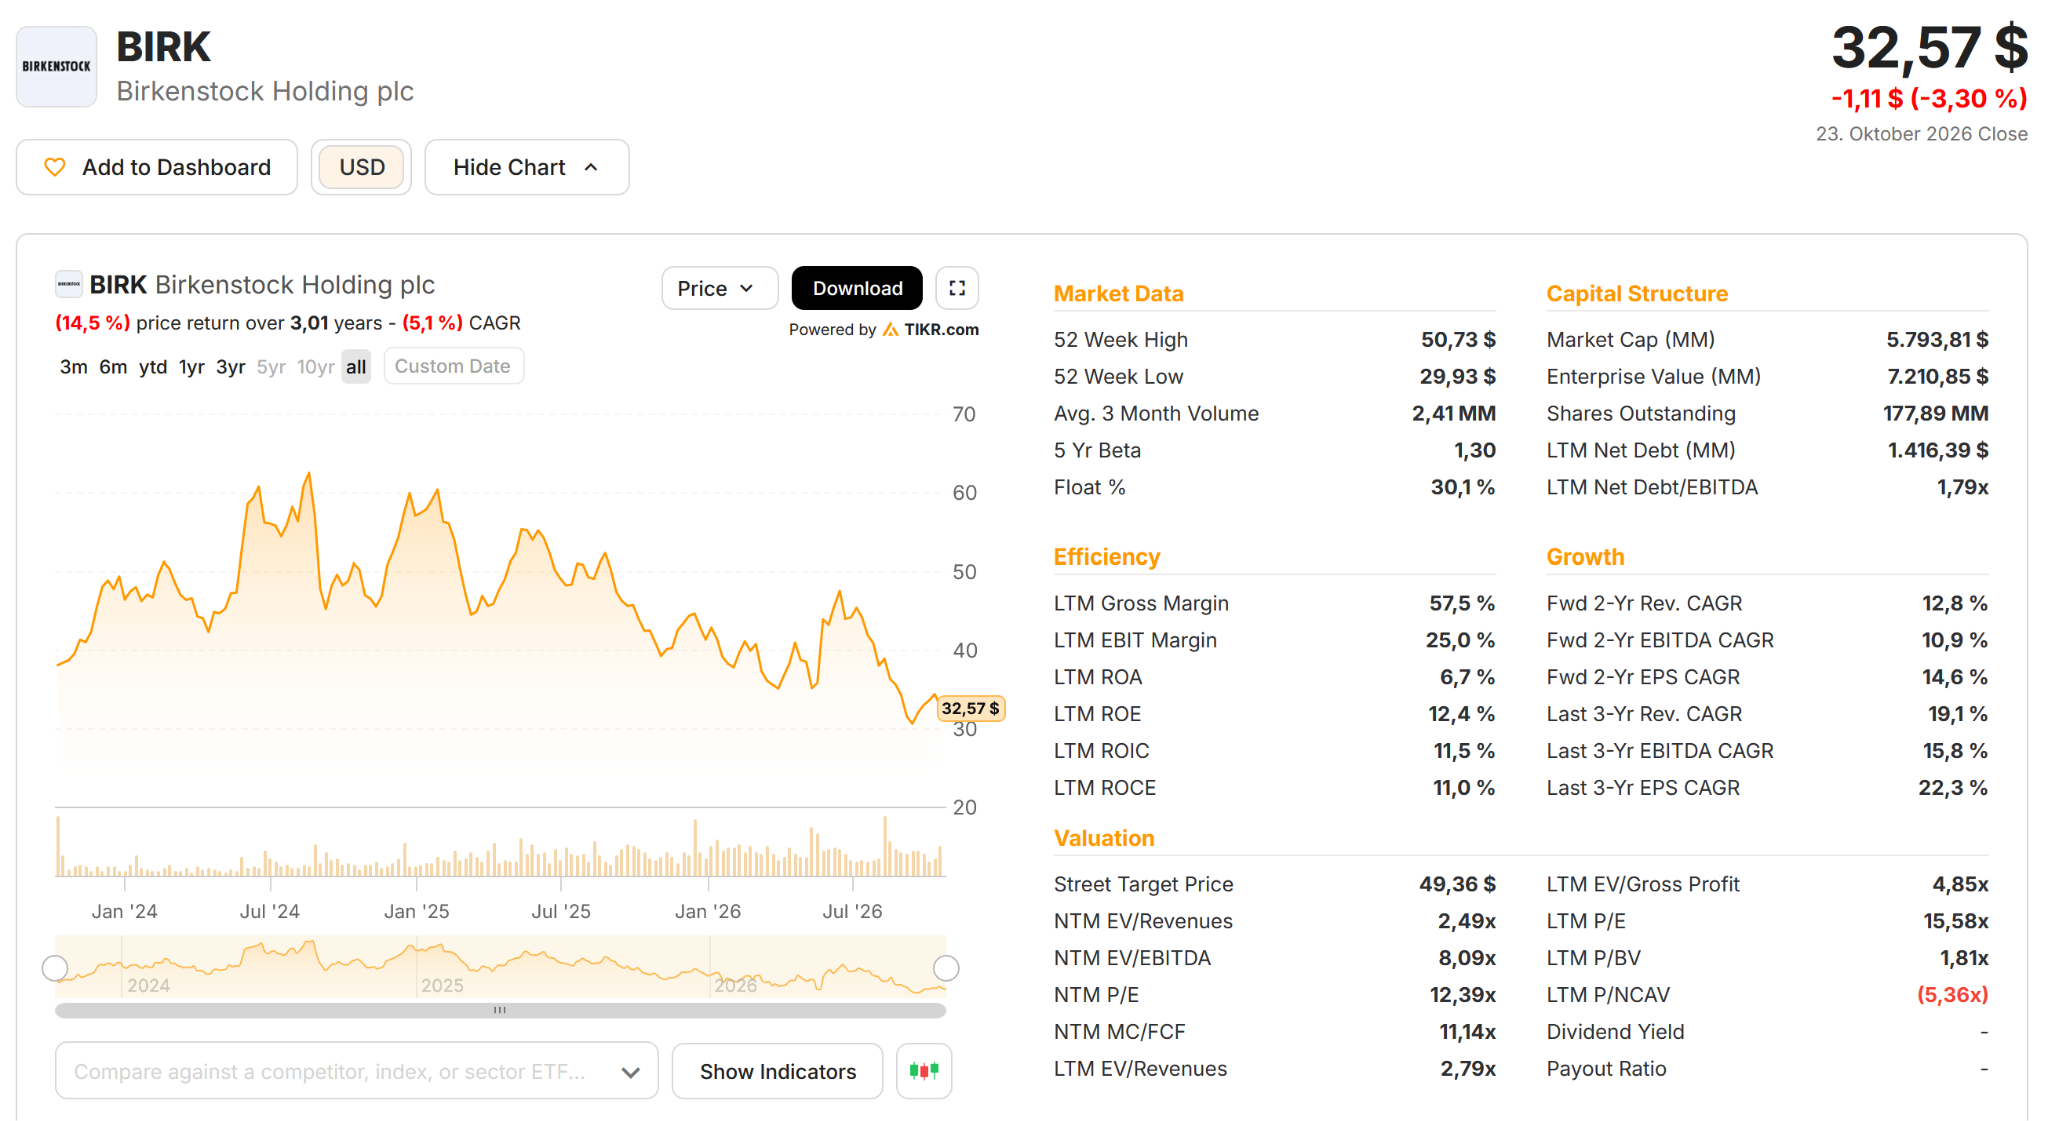
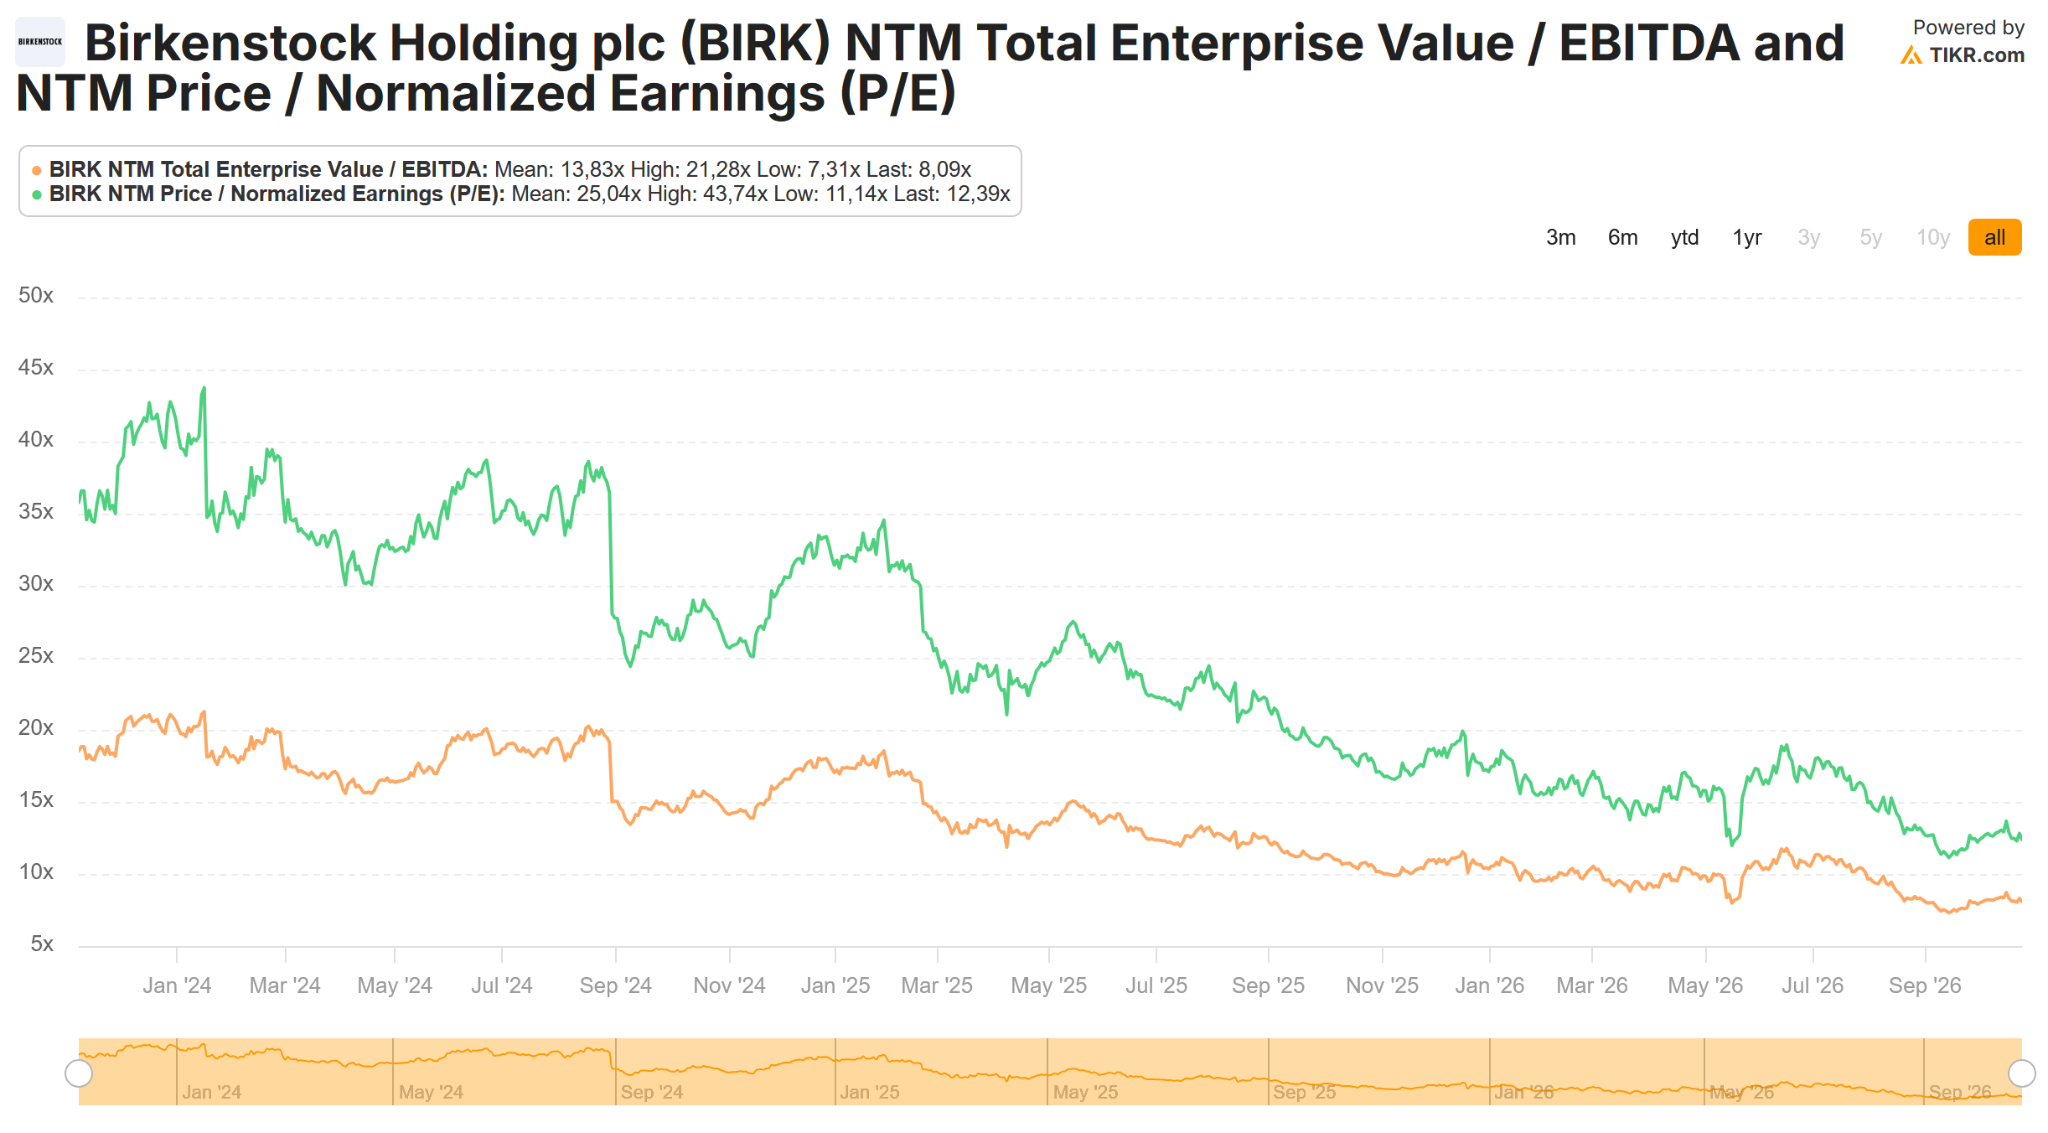
TIKR says next year’s P/E is only 12,5x. Looking at the financials, we can see that since 2023, both sales and profits increased significantly, however, things have been slowing a little bit lately.

L. Catterton, the Private Equity arm of LVMH owner Bernard Arnault still owns 43% and Arnault’s family holding, Financiere Agache another 6%, but they have been selling shares. A few weeks ago in August, L. Catterton sold shares for around 1 bn EUR, of which Birkenstock bought back a relevant amount.

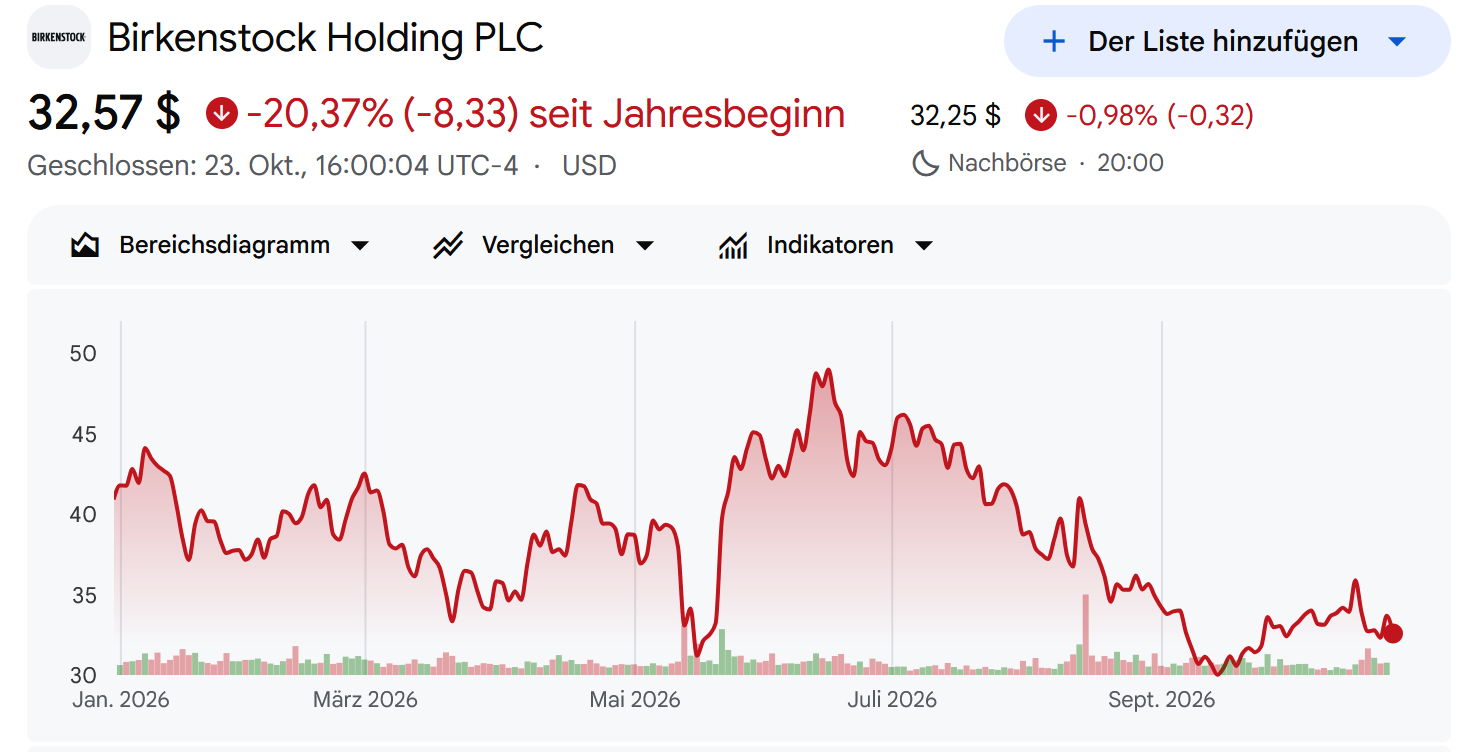
Looking at the shorter term share price, this sale by L. Catterton clearly did not infuse a lot of confidence in other Brikenstock shareholders which leaves the share price very close to all time lows:
Interestingly, according to their latest investor update, sales are still strong and growing in the “mid teens”, both in their own retail channel (DTC) and wholesale:
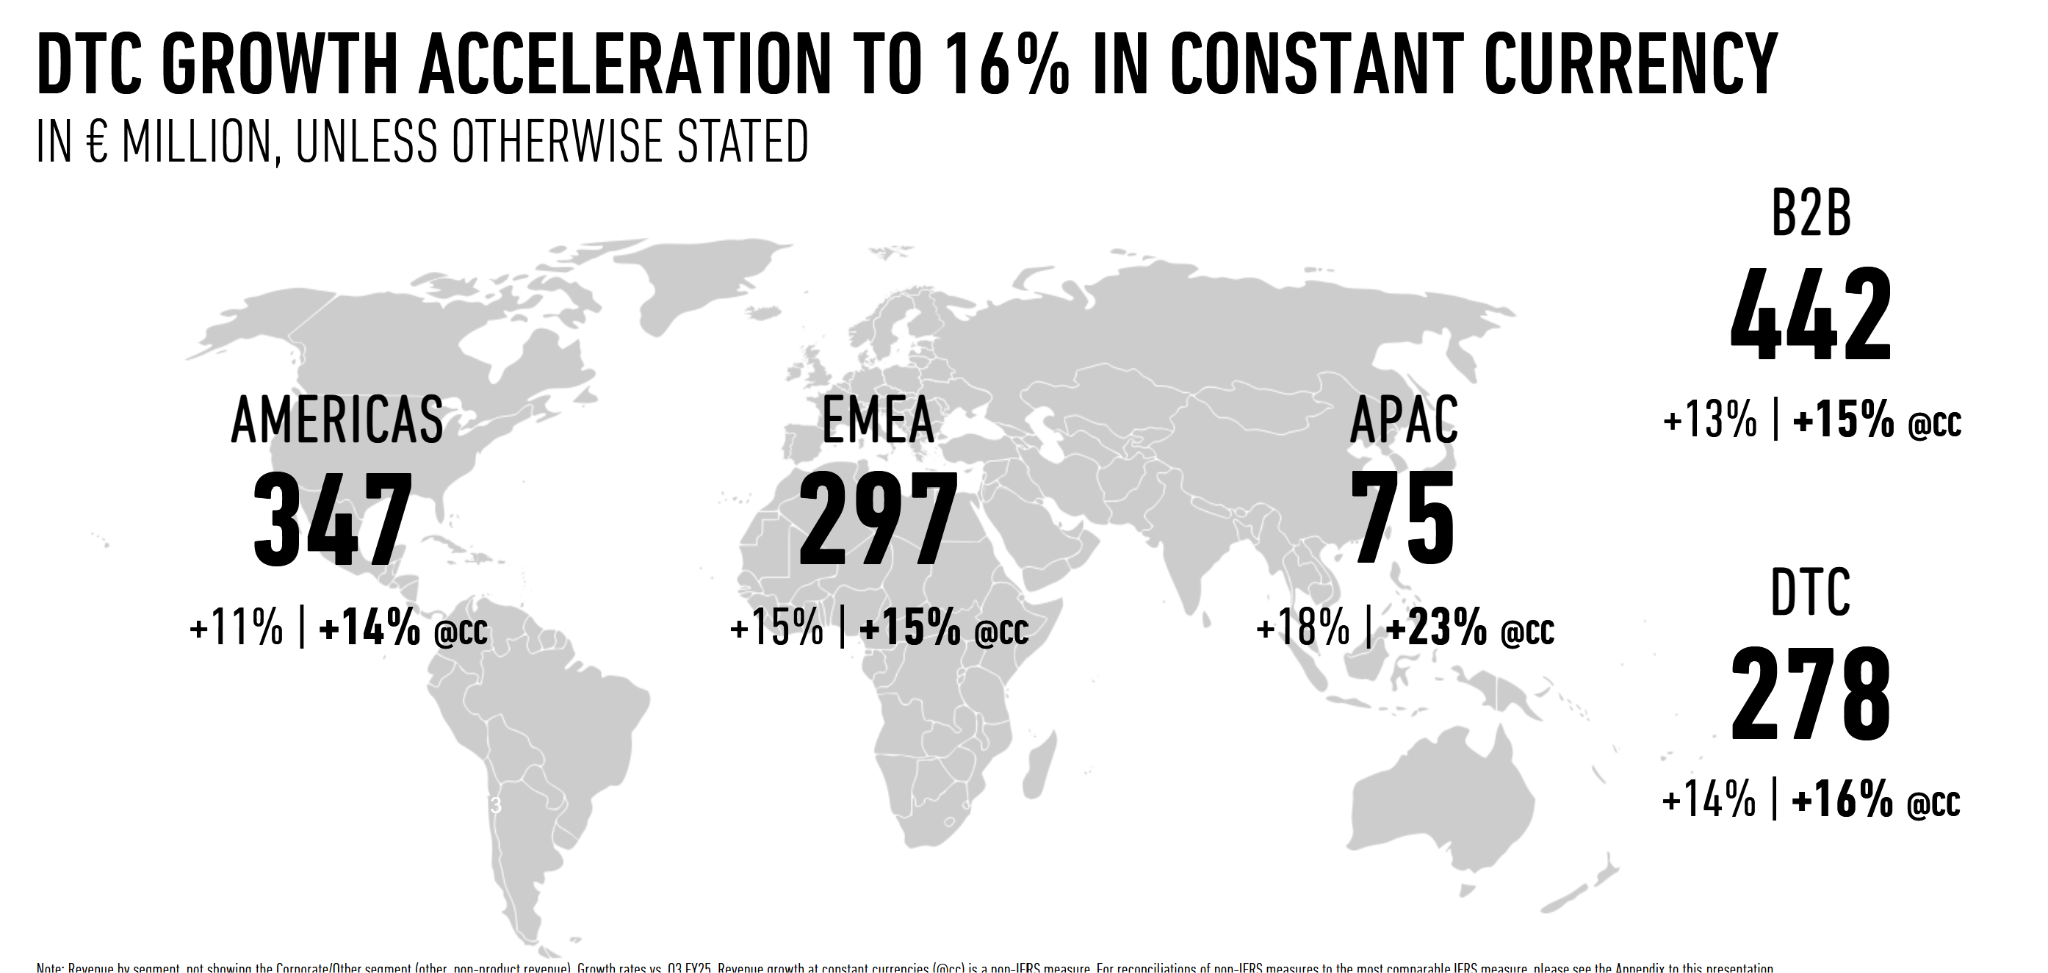
In contrast to other more high end luxury brands, the exposure to Asia and specifically China seems to be rather limited.

One point one has to give L. Catterton is that they managed to increase sales by +50% within 2 years as this chart from the IPO prospectus shows:
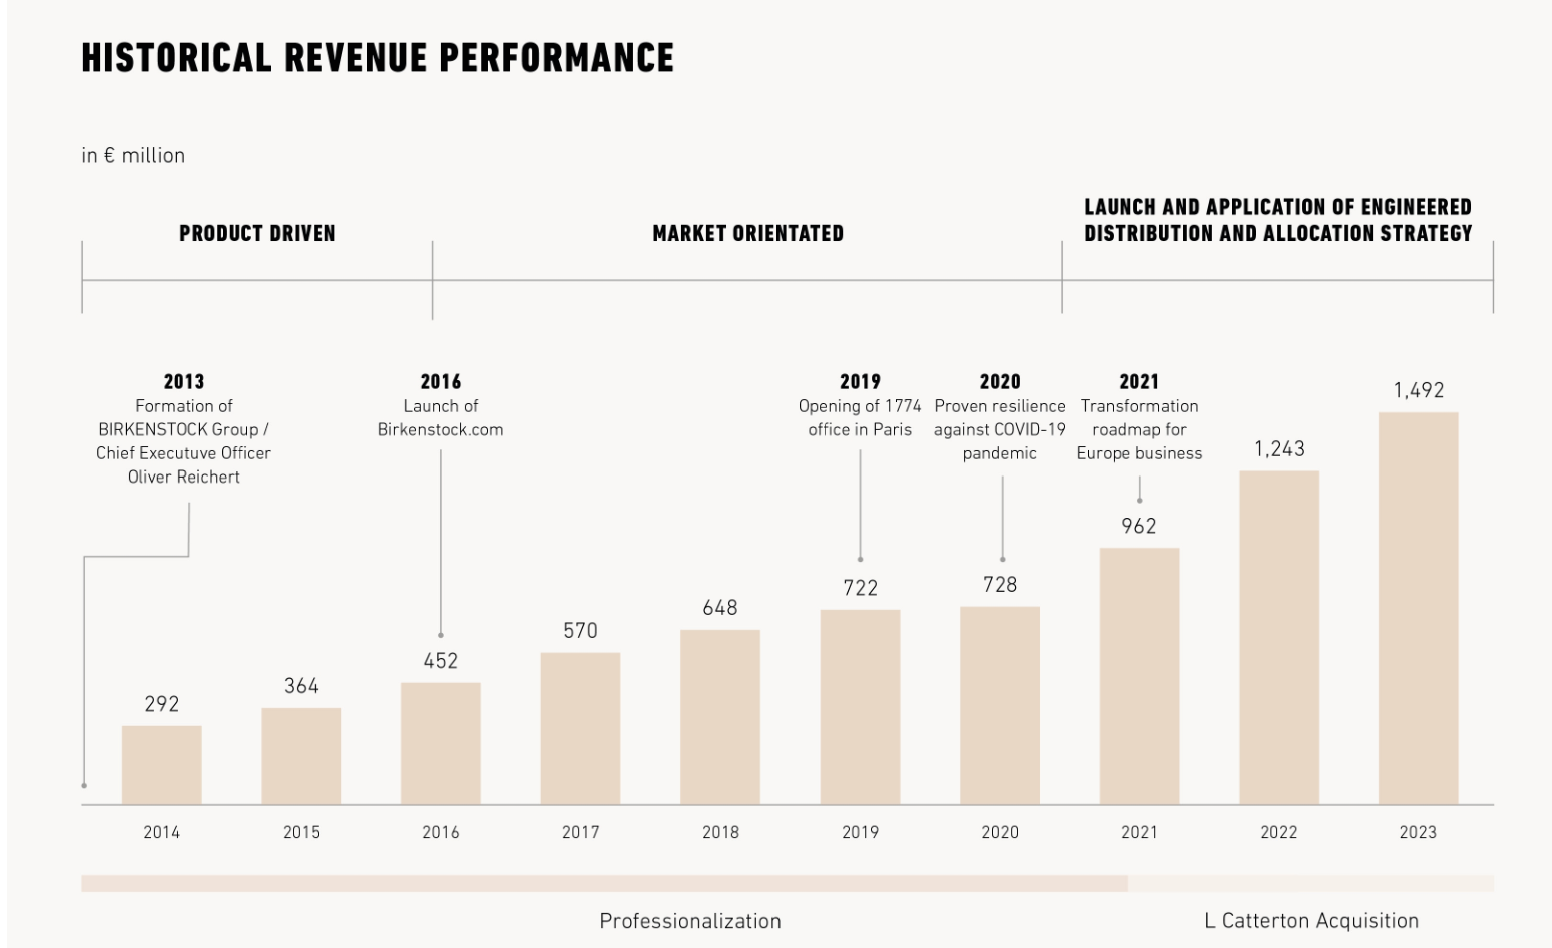
The problem of course was that the valuation at IPO which, in true PE fashion was north of 20x EV/EBITDA, was clearly too high. Now, at a much compressed 8x NTM EV/EBITDA, this looks more reasonable.

This Chart from TIKR nicely shows how multiples have been compressed since the IPO:
Will the Birkenstock “Fashion Trend” continue ?

A big issue is clearly if the “Birkenstock fashion trend” will run out of steam at some time.

Originally, Birkenstocks were nerdy “health sandals” often worn by office workers in technical professions like engineers or programmers.

When I was a student, I did an internship at Siemens and I remember that a lot of the engineers had (white) Bikenstocks at their desks in which they changed in the morning and would walk around all day in the office. That looked quite odd especially with those who actually wore a suit.

This is a picture of a classic Birkenstock sandal:
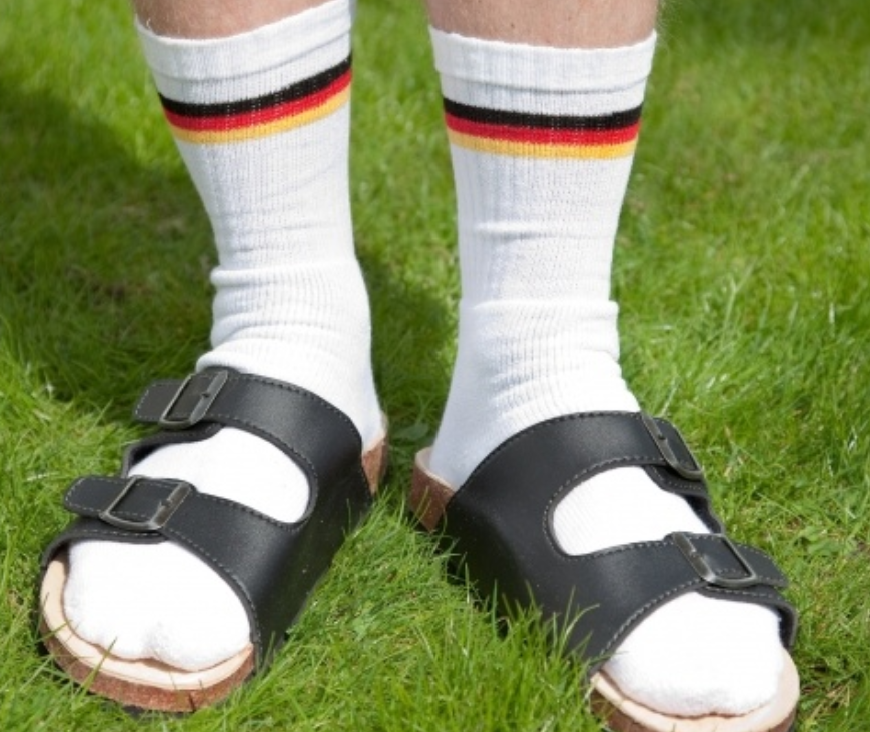
And if you ever were on vacation with a lot of Germans in the summer, this look might be familiar to you:
Birkenstock became fashionable in the Mid 2010s. Before that, especially in the US, Birkenstocks were considered “hippie style” but that changed when Birkenstock teamed up with famous design labels to create more fashionable versions.

Interlude: Dr. Martens – the famous example for a footwear fashion brand that is not so fashionable anymore

A famous example for an explosive run-up and spectacular drop of an iconic shoewear brand is UK footwear brand Dr. Martens.

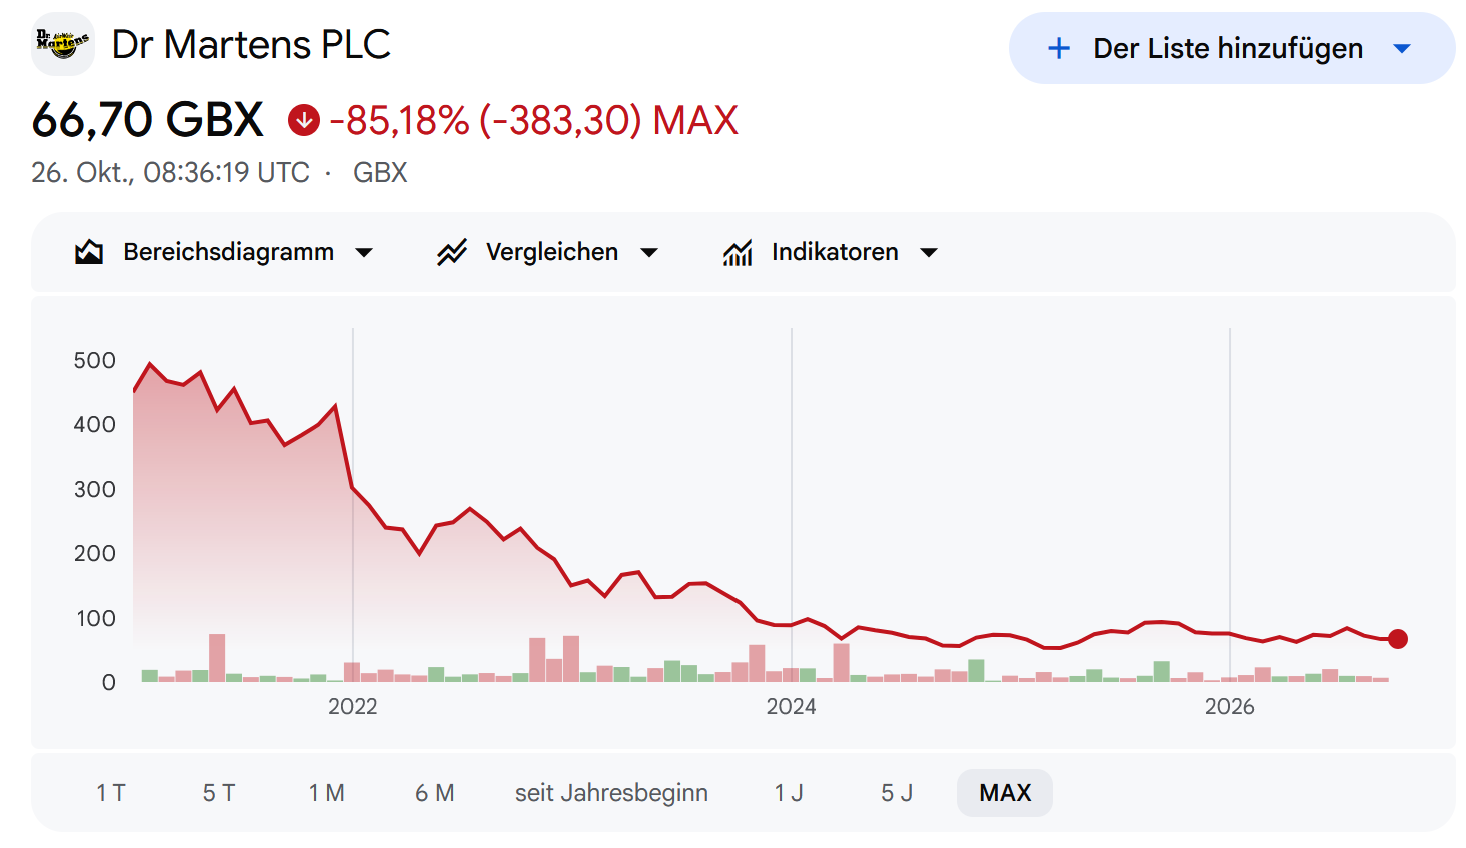
Dr. Martens was IPOed in January 2021 by PE shop Permira, which owned the company for 7 years. As we can see in the chart, after the first day “pop”, the stock went south pretty much soon thereafter and has now lost -85% from the initial IPO price:
Looking at the financials, we can see that Dr. Martens only managed to show 2 more years of double digit growth after the IPO before sales declined significantly and profits even more so:
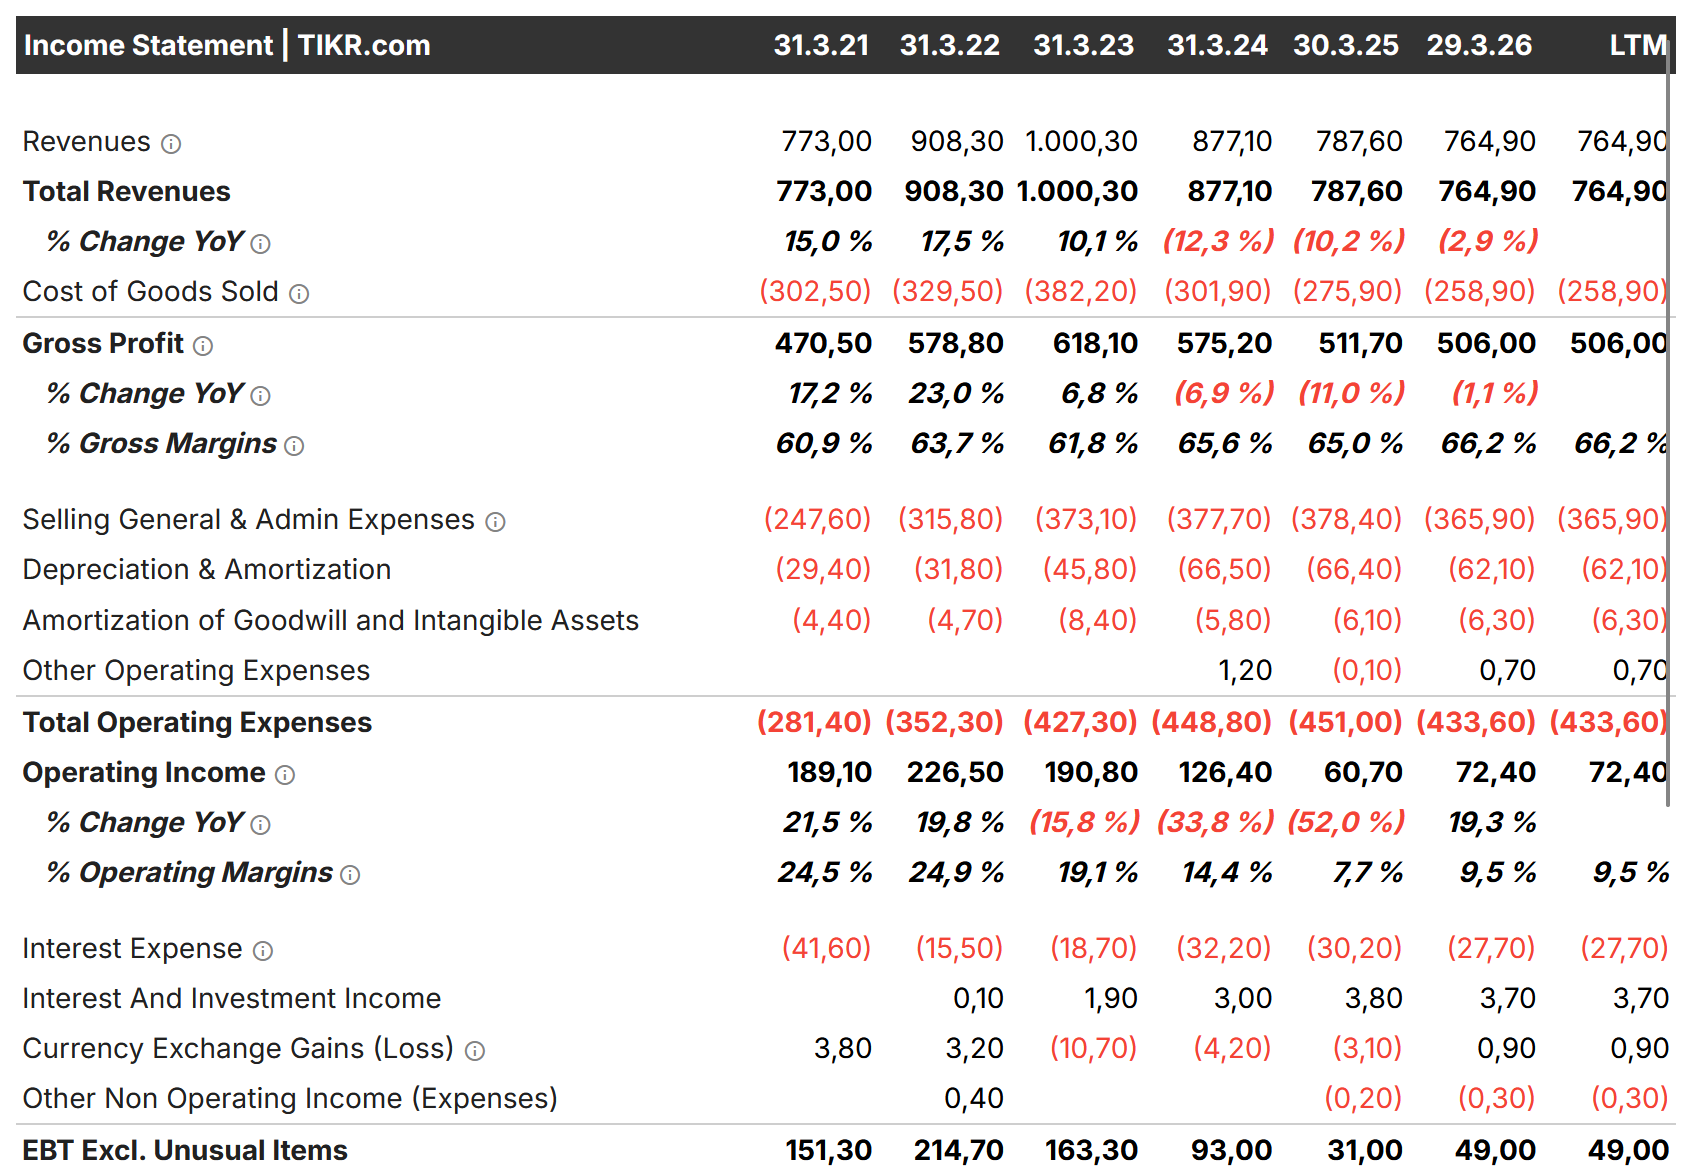
That’s clearly not enough if you IPO a company at 20x EV/EBITDA which Permira did. Interestingly, Permira still owns ~38% of the company.

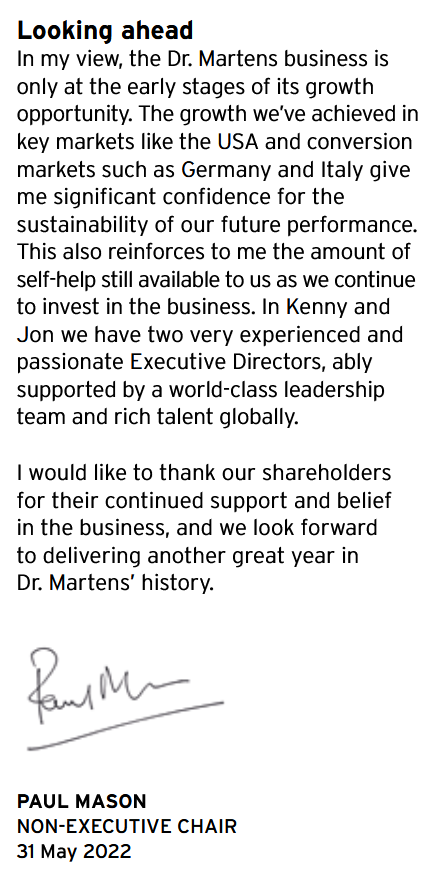
Reading the 2022 annual report, where they show 18% sales growth, the growth story still seems to be intact:
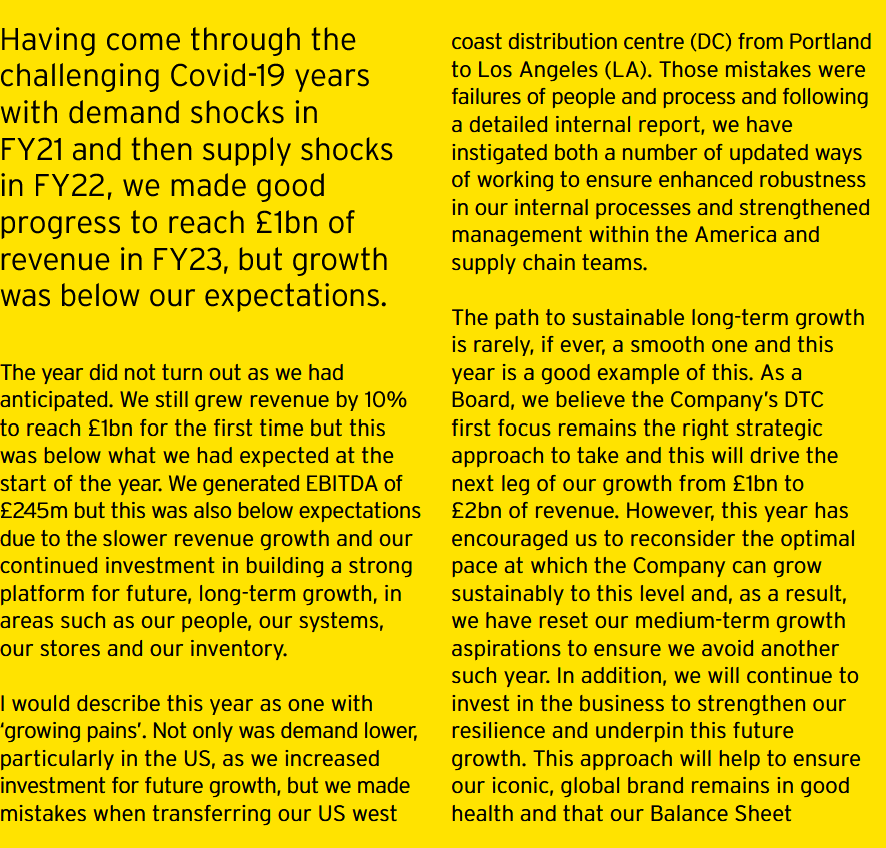
In 2023, lower than anticipated growth was blamed on the botched transfer of a US distribution center:
In 2024, the sales decline was blamed on cautious wholesale customers:
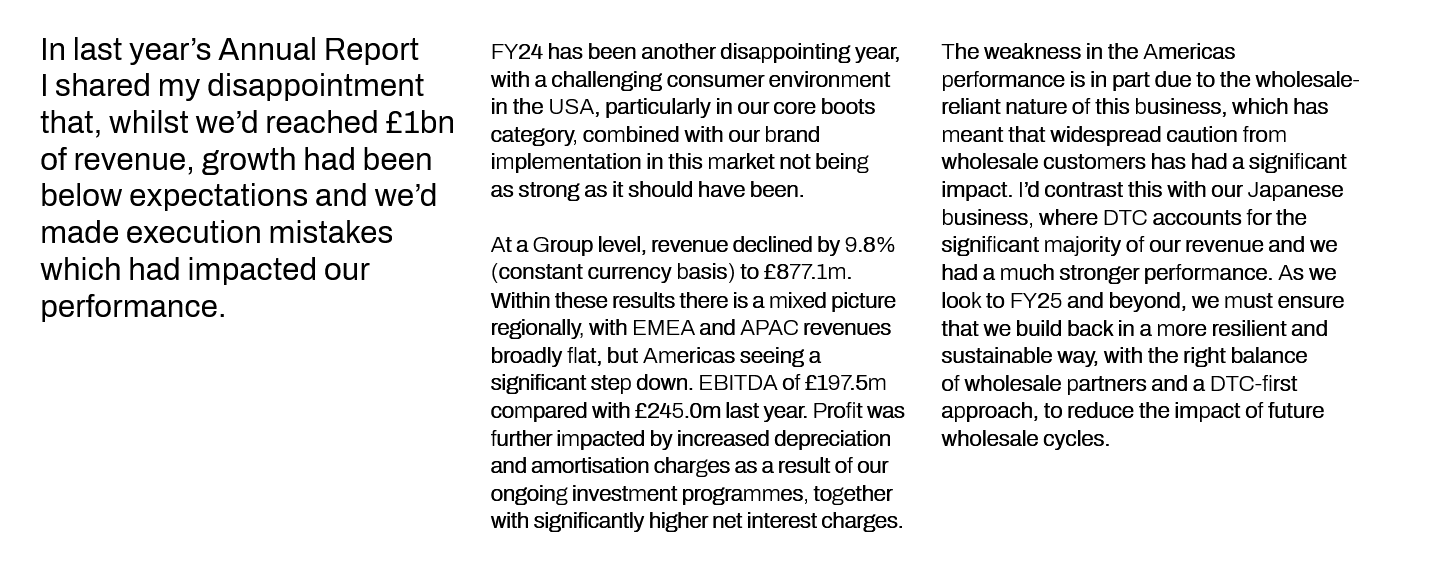
However, looking at the previous year report, one could already see that wholesale had declined and the brand only grew by opening a lot of new stores.

There are a couple of articles on why Dr. Martens became unpopular especially in the US. Overstocking after Covid and heavy discounts is one reason, but also moving the production from the UK to Asia is often mentioned (although that seemed to have happened long time ago in the early 2000s).

There seem to have been challenger brands like Solovair and Blundstone. Solovair boots interestingly seem to be manufactured in Dr. Marten’s old factory in the UK.

Their latest report from May 2026 still shows a decline in sales but a certain recovery in (adjusted) profits:
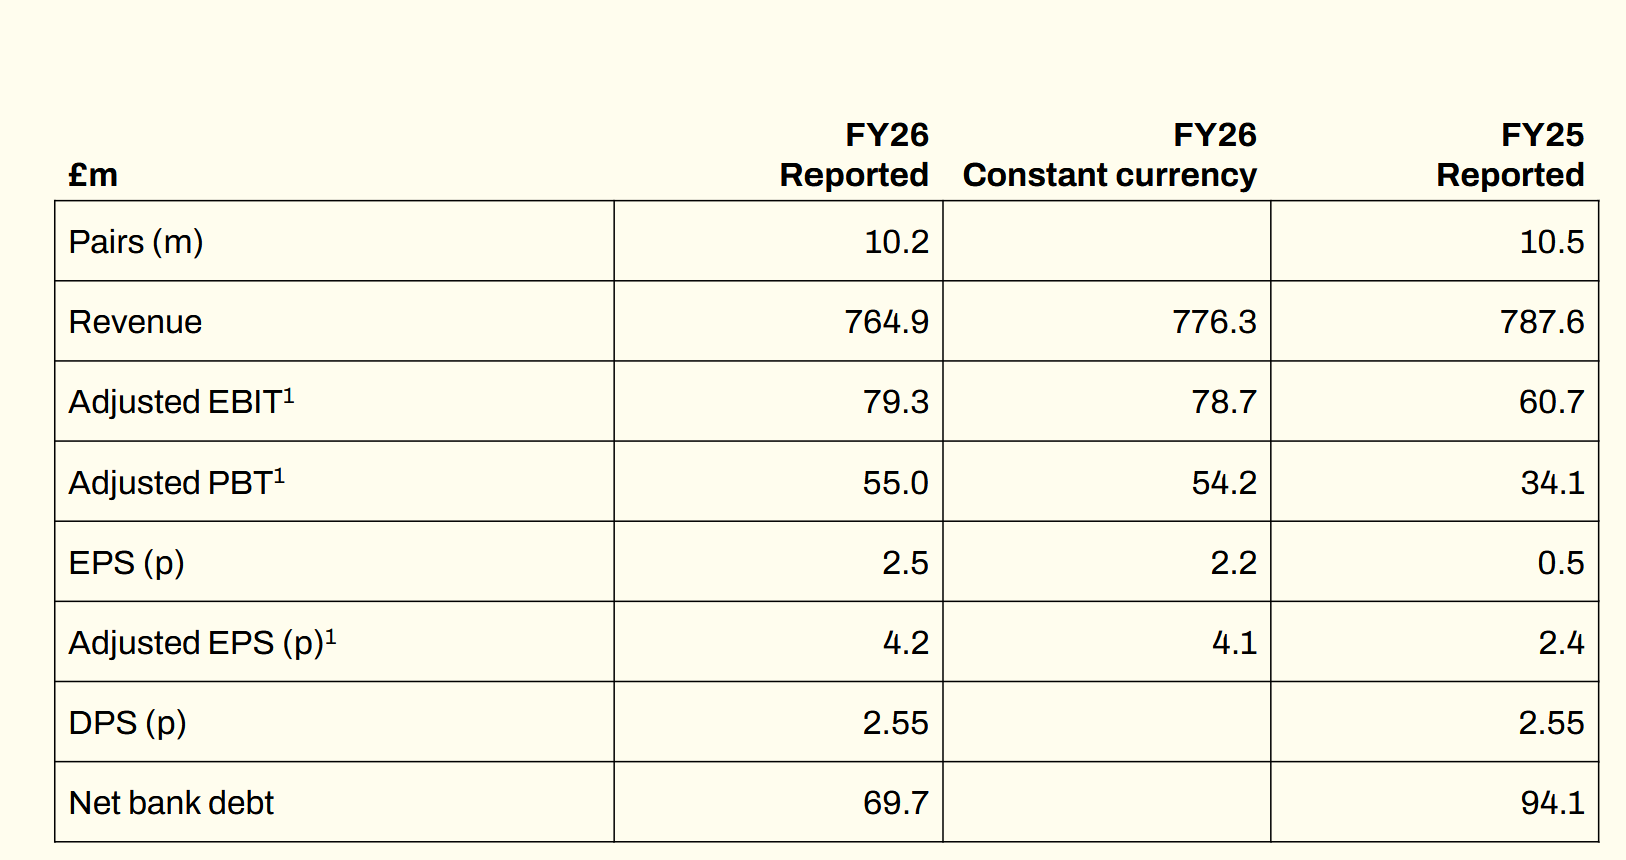
So turning around a once hyped but then struggling footwear brand is clearly not that easy.

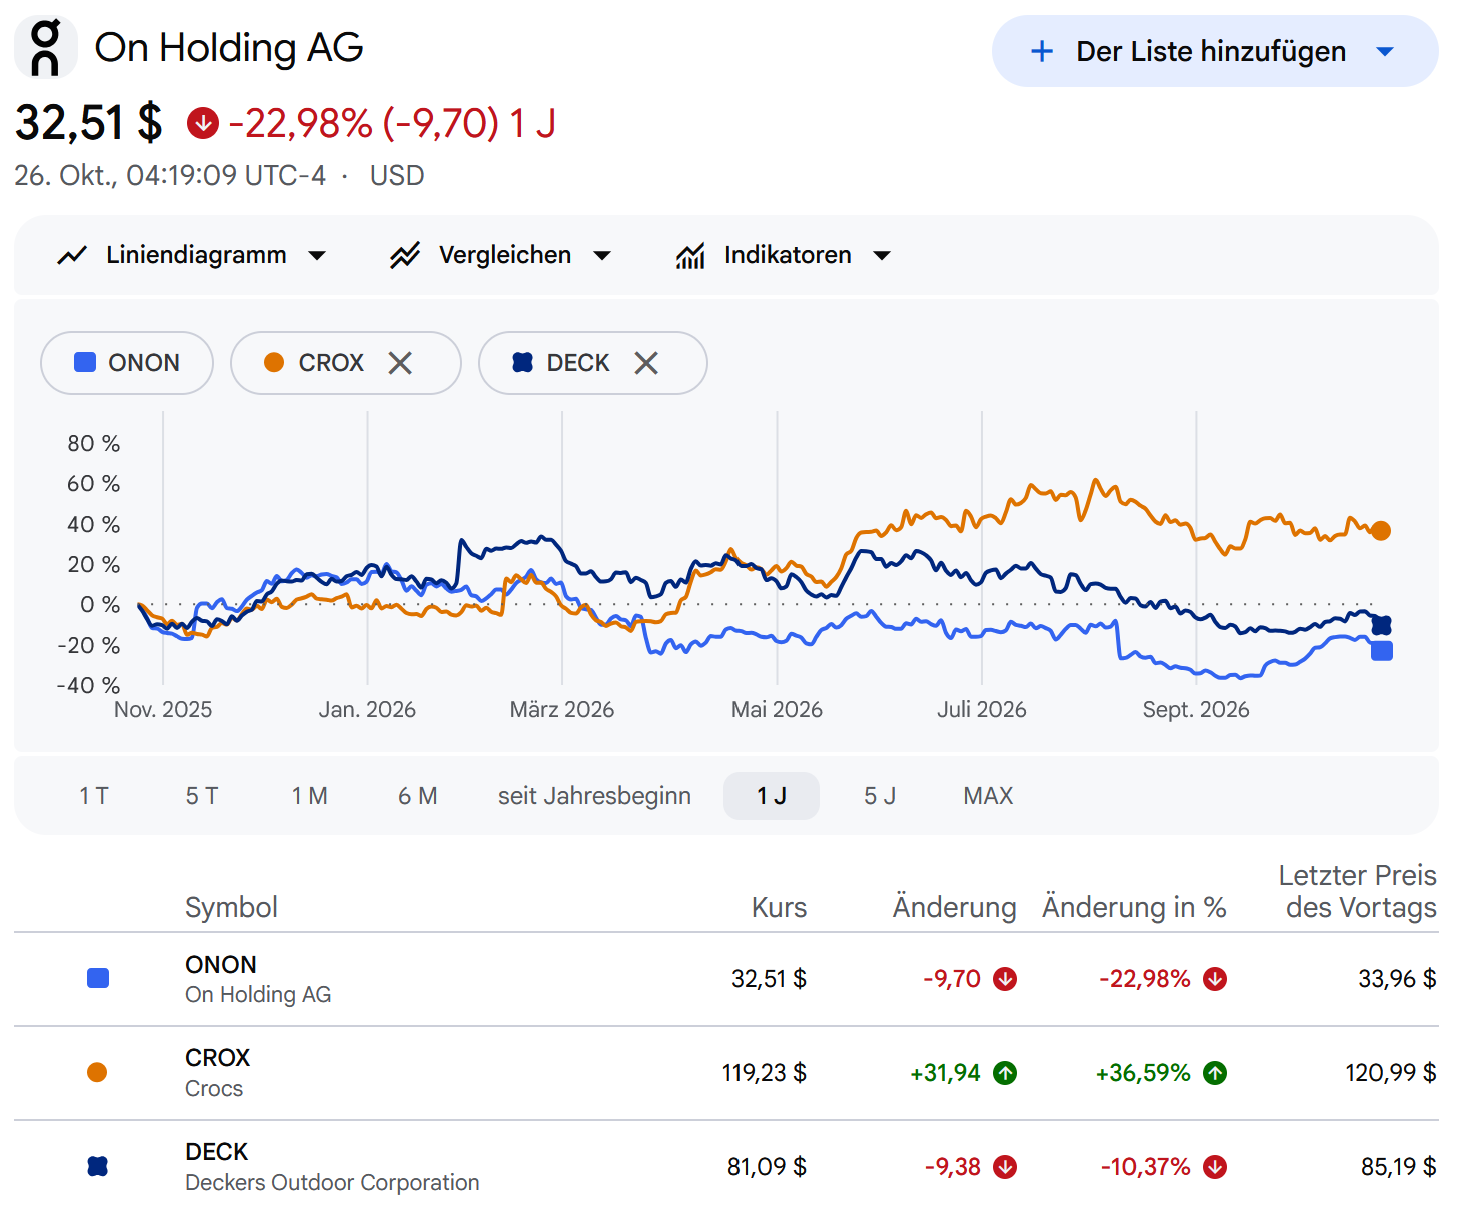
It doesn’t help that a lot of other footwear brands have very weak stock charts, too, with the exception of Crocs:
Back to Birkenstock:

Overall I find Birkenstock quite interesting but it is clearly not an easy stock. For full transparency, I am not a “Birkenstock person”, I have never owned a pair and will most likely never own one. But still, it could be a potentially interesting “broken IPO” story as long as growth remains in the mid teens.

My gut feeling tells me that Birkenstock is less “fancy” than Dr. Martens and compared to Dr. Martens for instance, Birkenstocks are still produced in Germany, not in Asia.

However, there are already a lot of similar smaller brands that sell similar shoes for much lower prices than Birkenstock, for instance this one or even Sandals that are manufactured in German prisons.

Dr. Martens clearly shows that when a trend breaks, it can take a very long time to recover, if at all.

The comparison of Dr. Martins and Birkenstock is also a great use case for an AI analysis/report. In this case, I asked Claude to research the similarities and differences between Birkenstock and Dr. Martens and I have to say that the result was quite interesting.

This is Claude’s summary:
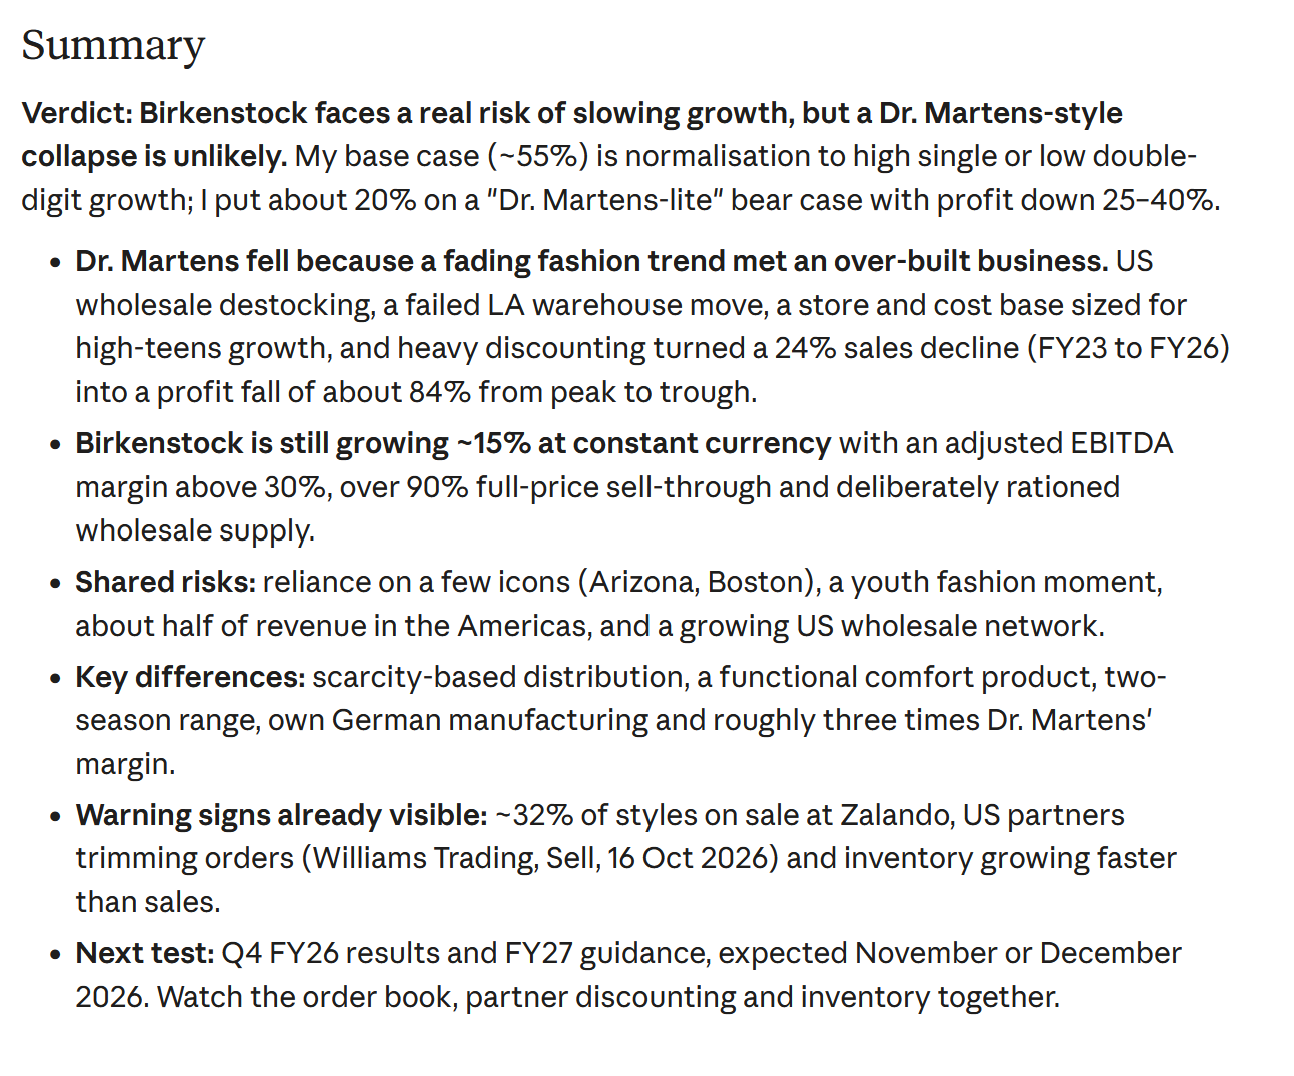
I would certainly not base any investment decision on this, but it confirms my feeling that Birkenstock is not exactly on the same trajectory as Dr. Martens a few years earlier. But clearly there is a risk that they might not grow at 15% for many more years, which the current share price seems to expect as well.

A big learning in any case is (and this is no surprise) that you should avoid investing into PE sponsored IPOs of some hot footwear brands at a valuation of 20x EV/EBITDA or more.

The PE guys definitely know when to sell and as an investor, you should not try to outsmart PE guys at an IPO. Maybe there is one out of 10 that is doing really good, but the probability is slim.

When you look at Private Equity portfolios which often have average valuations of 16-18 x EV/EBITDA, it is clearly not a surprise that IPOing or selling them at these valuations are not easy.

For Birkenstock, I will watch the company but at the time of writing, I could not build enough confidence to start a position despite the quite attractive valuation.

I think especially the massive sales of L. Catterton just a few weeks ago does not create a lot of confidence that growth will remain at mid teens levels for that long.
Rubis SCA: Interesting French listed Special Situation with a Corporate Restructuring catalyst

DISCLAIMER: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!

Management Summary:

Rubis, the French listed Fuel distribution company, represents a potentially interesting Special Situation investment, despite (or because of) the current negative sentiment towards French stocks.

On the back of strong earnings momentum (6M earnings +18%), Rubis has almost no exposure to France and has recently announced to undergo a structural transformation from a disadvantageous SCA structure (similar to a German KGaA) to an ordinary stock corporation.

For normal shareholders, this is hugely positive despite a planned compensation for the former controlling shareholders. In addition, this opens up M&A opportunities which had been rumoured about for some time.

The share price so far has not reacted, most likely because of the perceived problems in France which in my opinion creates an opportunity for the opportunistic investor. The time that will be required until a potential M&A transaction will occur, will be nicely compensated through a 6% dividend yield.

Rubis Background

Historically speaking, Rubis is a rather young company, having been founded only in 1990 by a gentlemen called Gilles Gobin and then grew rapidly through many acquisitions, often buying small subsidiaries of large international energy companies.

Rubis is  a company that I came across several times in the past. It has a very interesting mix of businesses and geographies, but due to corporate structure issues (SCA, more similar to a GP/LP structure than a normal stock corporation) I never considered investing.

Effectively, the heirs of the founder through a 2,3% share holding were controlling the board and on top of that was able to charge a significant royalty on Rubis’ profit (in 2025 this was approx. 30 mn or 10% of Rubis net profit). The formula seems to give them a percentage of the annual share price increase but capped at 10% of the net income.

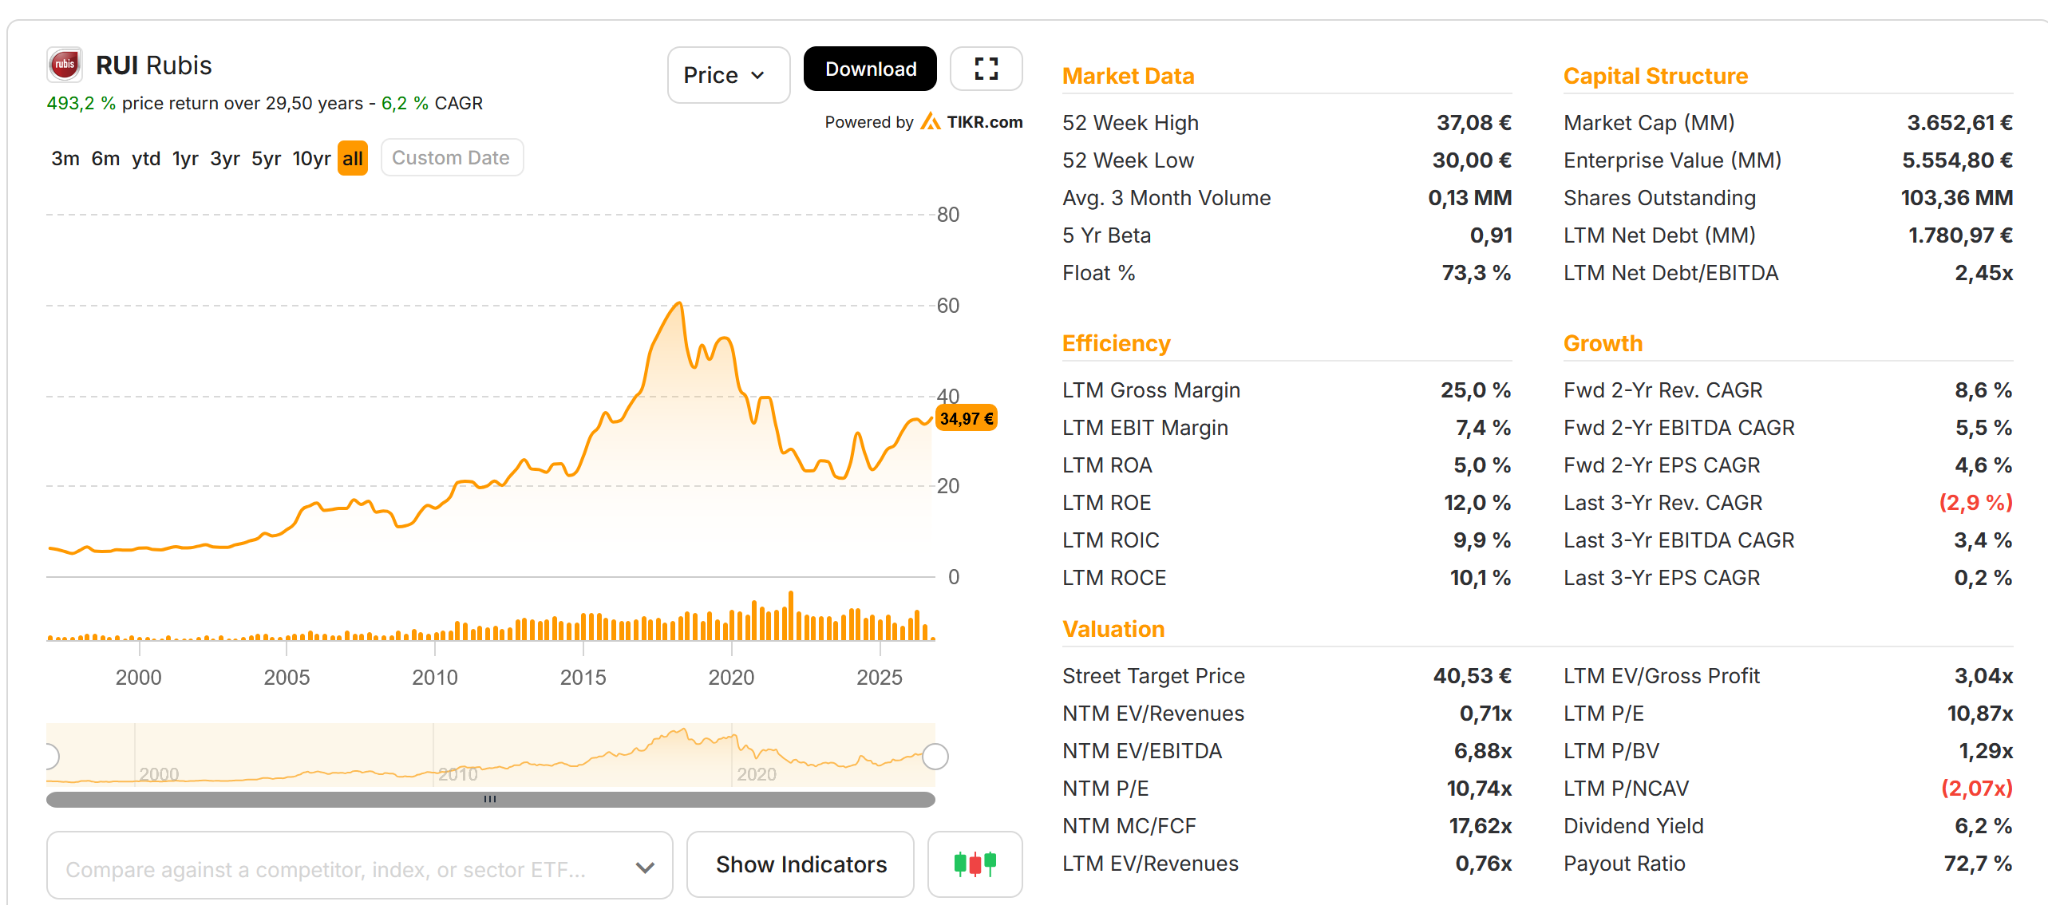
At the time of writing, Rubis is valued at around 3,6 bn market cap and trades at a relatively modest ~10,7 x NTM P/E which is clearly impacted by this unusual arrangement:

Looking at the long term chart, Rubis shareholders have done Ok including the dividend but the share price is significantly below the peak of around 60 EUR from 2018.

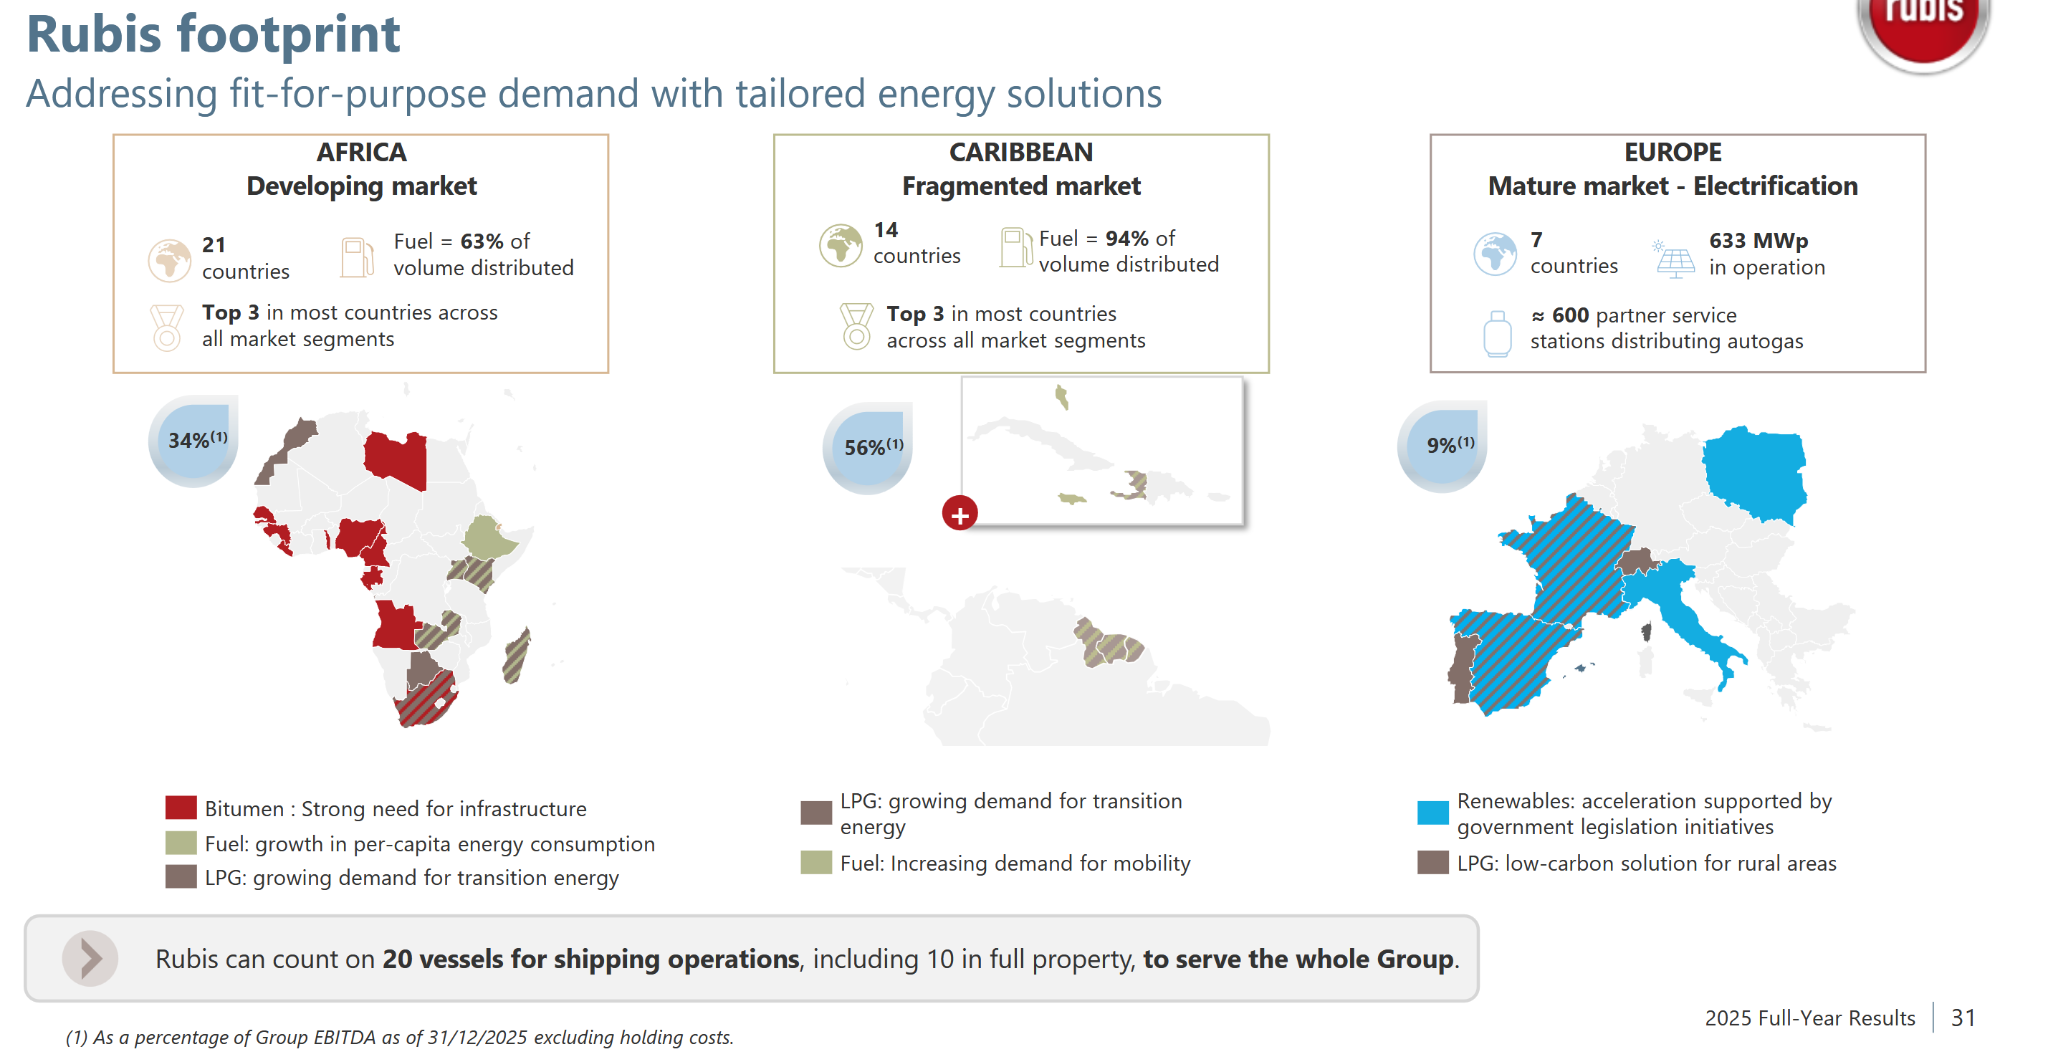
Rubis is French listed but has very little exposure to France

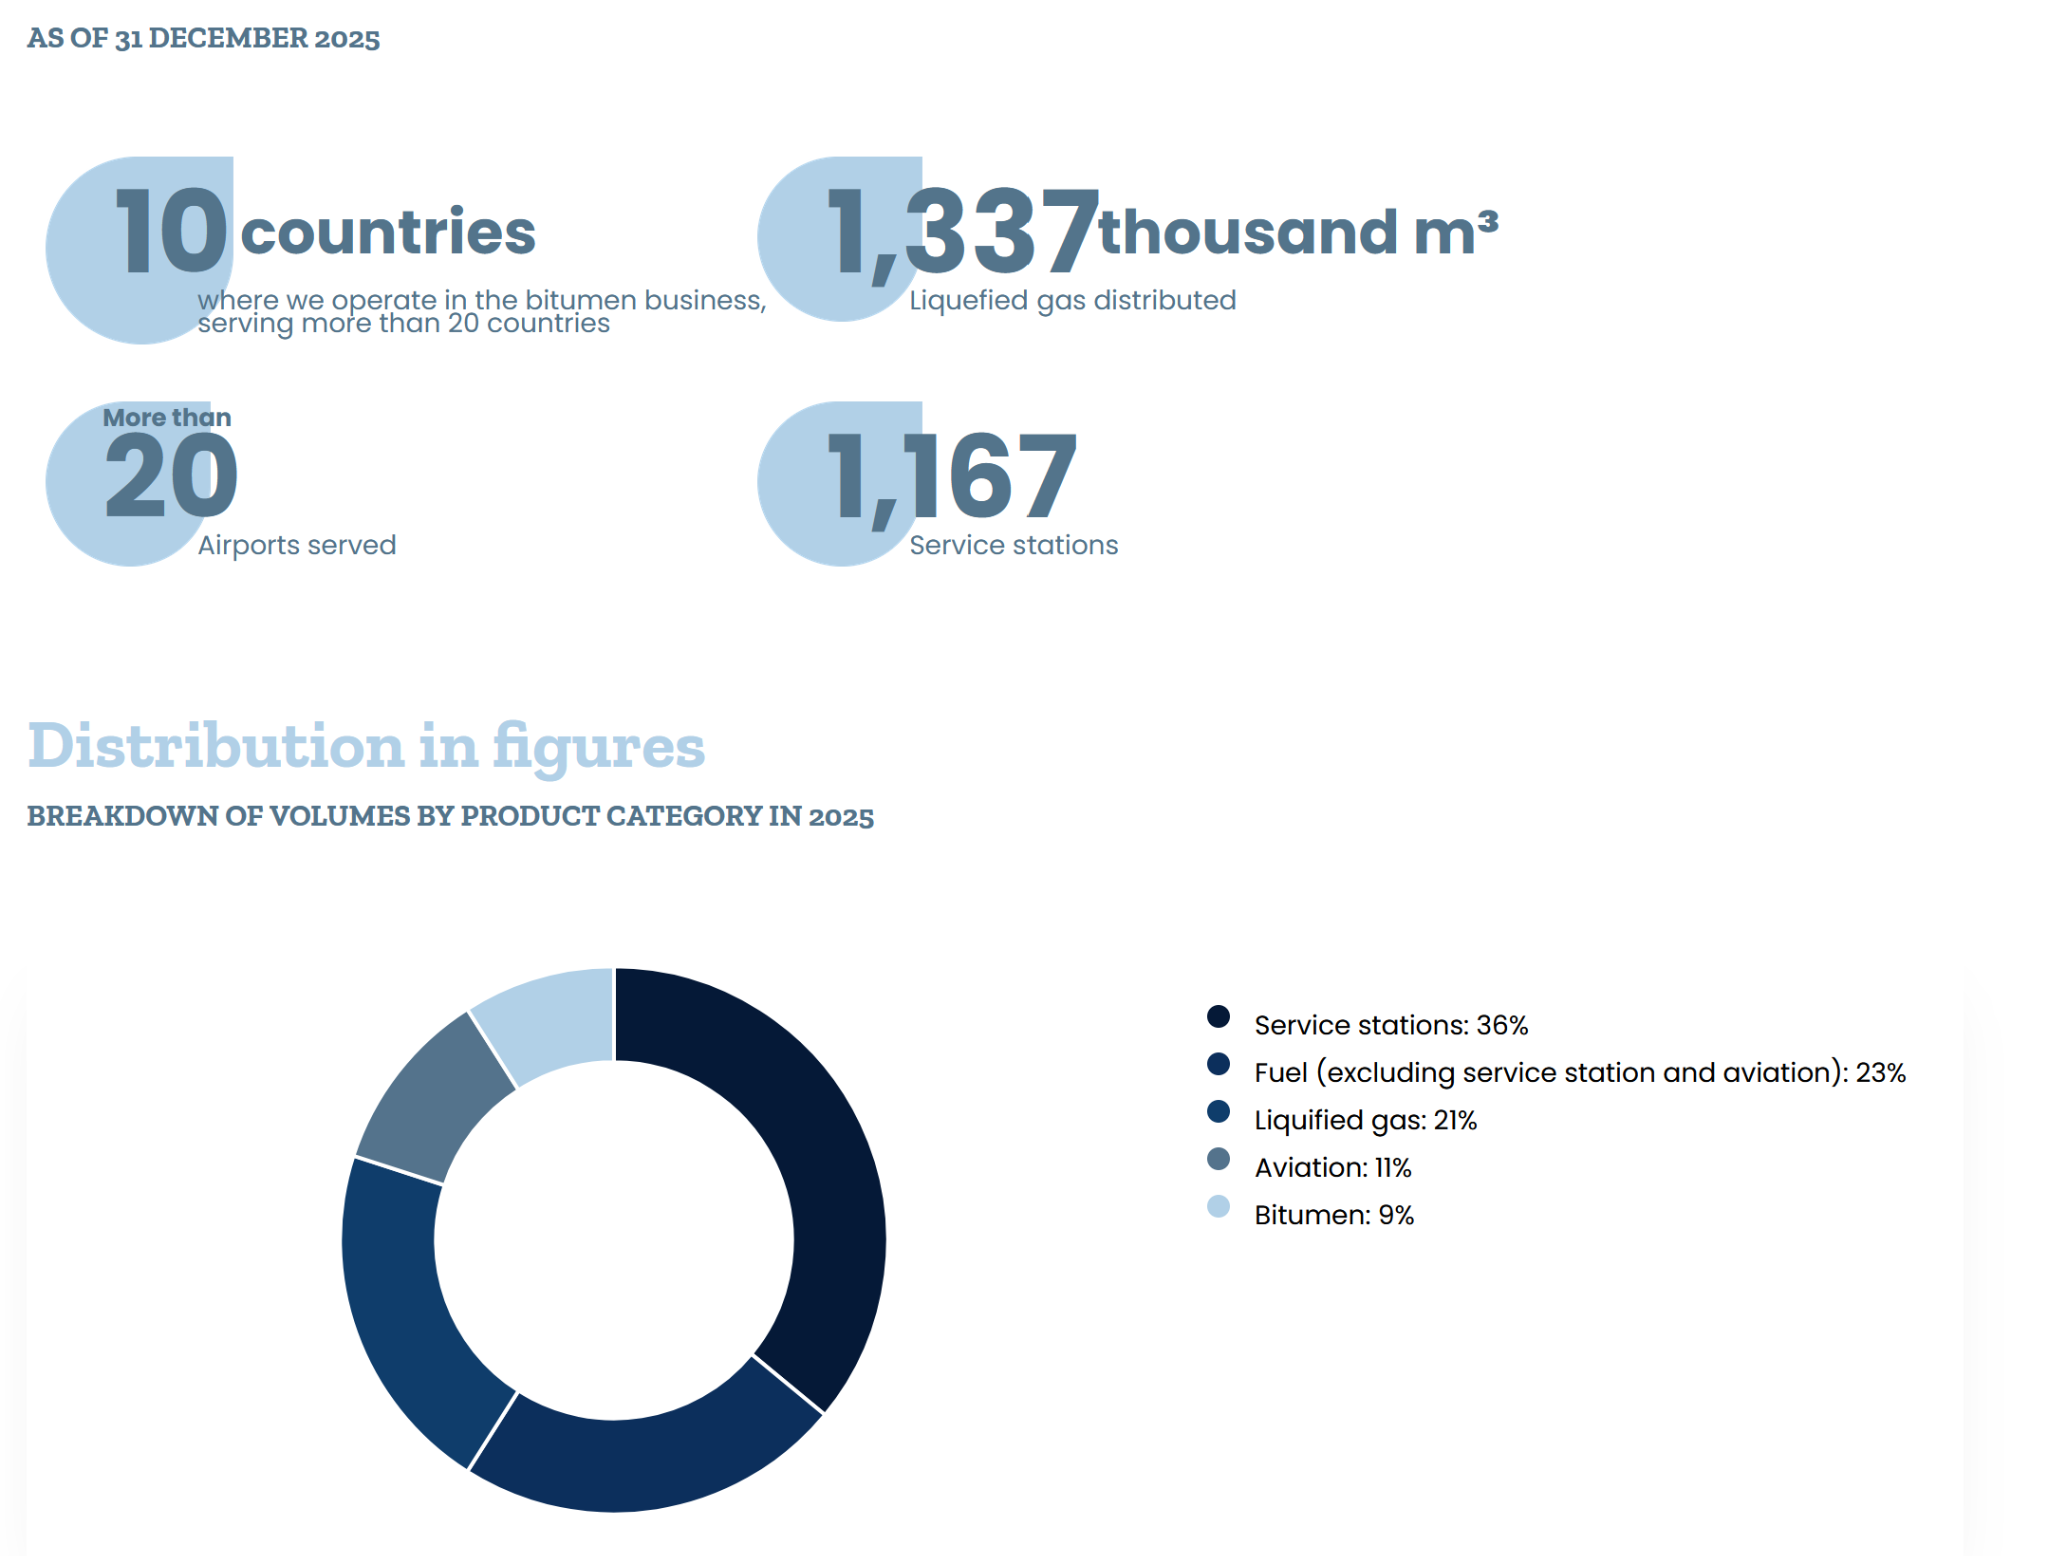
As there is “blood in the streets in Paris”, it is worth mentioning that Rubis sales have a pretty unique breakdown:

~50% of sales are in Africa

~40% in the Carribean

~0nly around 10% in Europe

The business as such is a mixture of fuel and LPG distribution, Renewable Energy and interestingly Bitumen distribution. Bitumen is a byproduct from refining oil and is used among others to create asphalt by mixing bitumen with sand and stones.

Rubis is the biggest Fuel distributor in Kenya which according to some sources is their biggest single market. This is a split of the fuel distribution business from their website:

This chart from the 2025 annual results nicely shows the extremely unique geographical  footprint of RUBIS:

The Renewables Energy business is a result of the 2022 acquisition of a French Renewables company called Photosol, which was widely criticized as too expensive.

Rubis also owned a terminal business, but sold that in 2024 to JV Partner and Infrastructure fund I Squared capital.

So in a nutshell, Rubis is not impacted much by the current situation in France.

Financing wise, they seem to have restructured their debt financing “just in time” in late 2025 with a syndicated loans facility that seems to have a 5 year term.

As the business is very cash generative, it looks like that they are also not affected by the recent widening of French spreads as they don’t have to issue debt for the next few years.

The catalyst: Corporate structure change

Now however, things seem to change and quite quickly: Rubis intends to become a “normal” company, most likely under the pressure of some prominent investors, such as the Bollore Group. My friend Graouilly has written about it here.

From a technical perspective, the former “GP” will receive an extra 12% of newly issued shares as compensation for giving up his special rights that included a royalty on Rubis’ net profit.

Rubis has scheduled an extraordinary shareholder meeting for December 9th where these changes including the capital increase shall be approved.

There seems to be some resistance among the larger shareholders that the compensation is too generous, but any lower compensation amount will be a positive for shareholders.

Share price:

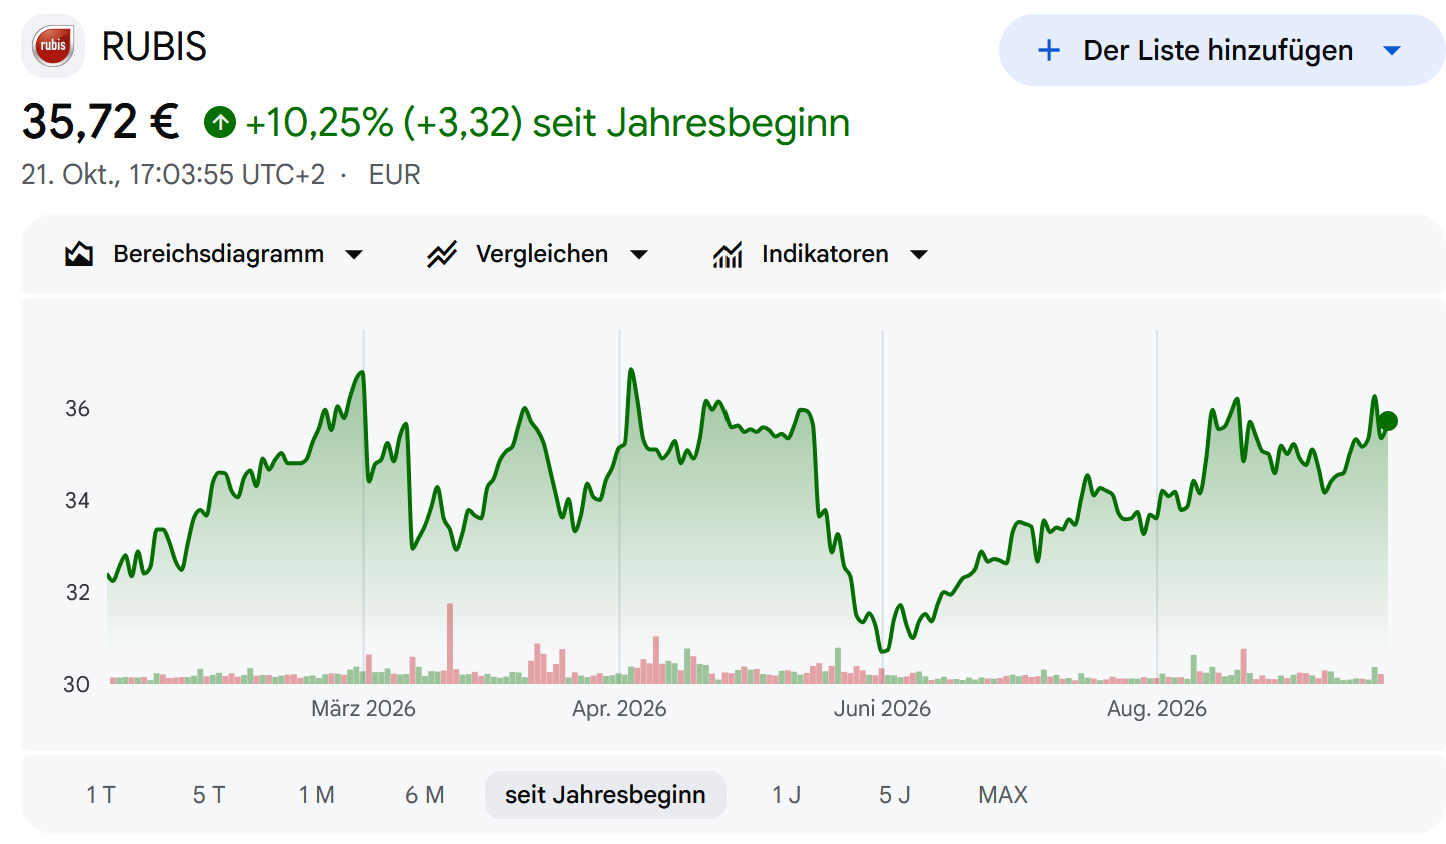
Looking at the share price, we can see that Rubis is up ~11% YTD, which is in line with earnings growth that had been +18% for the first 6 months:

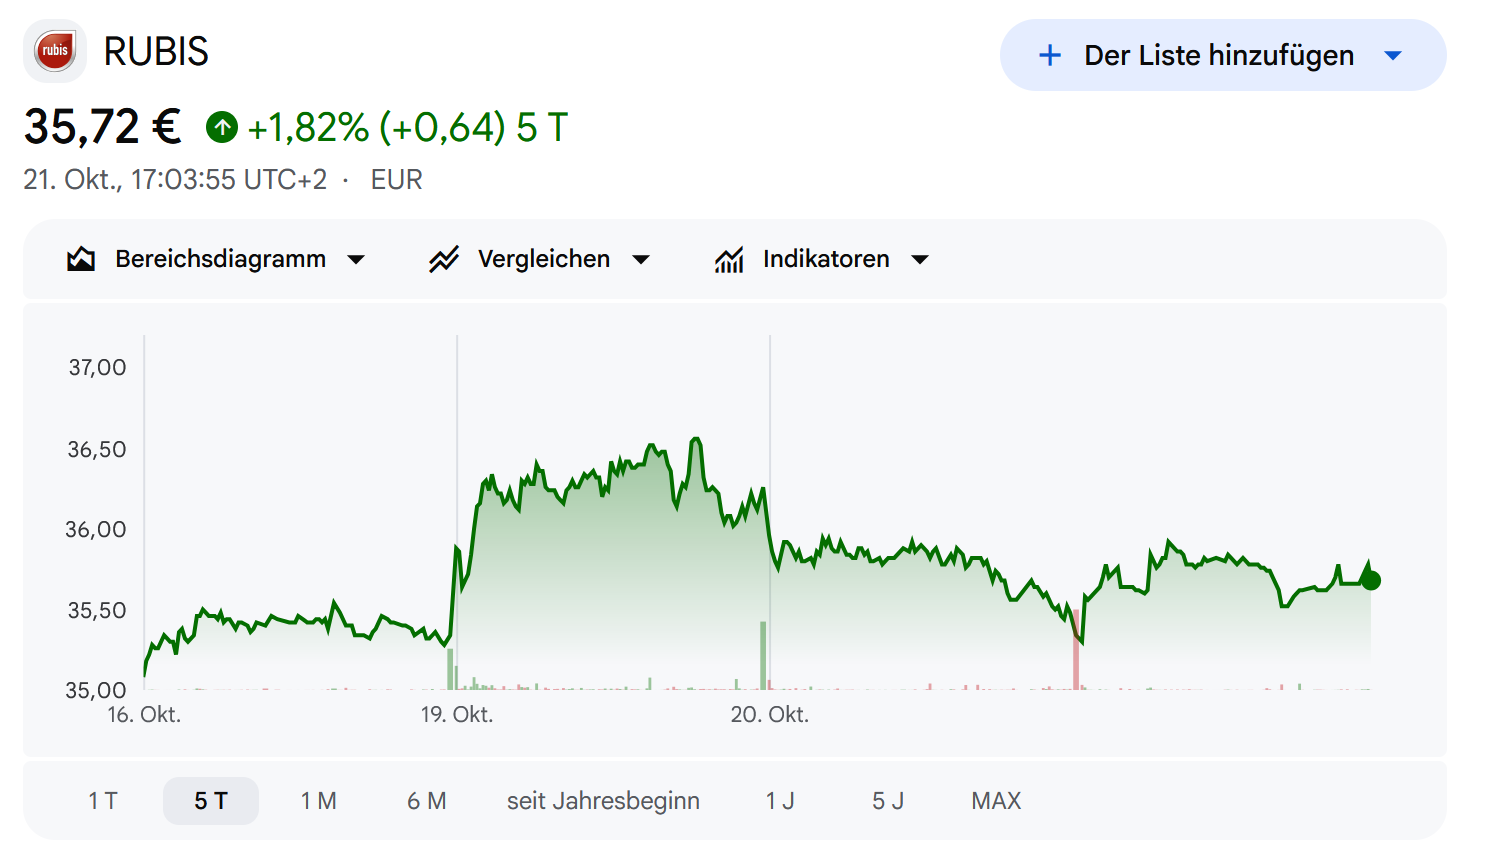
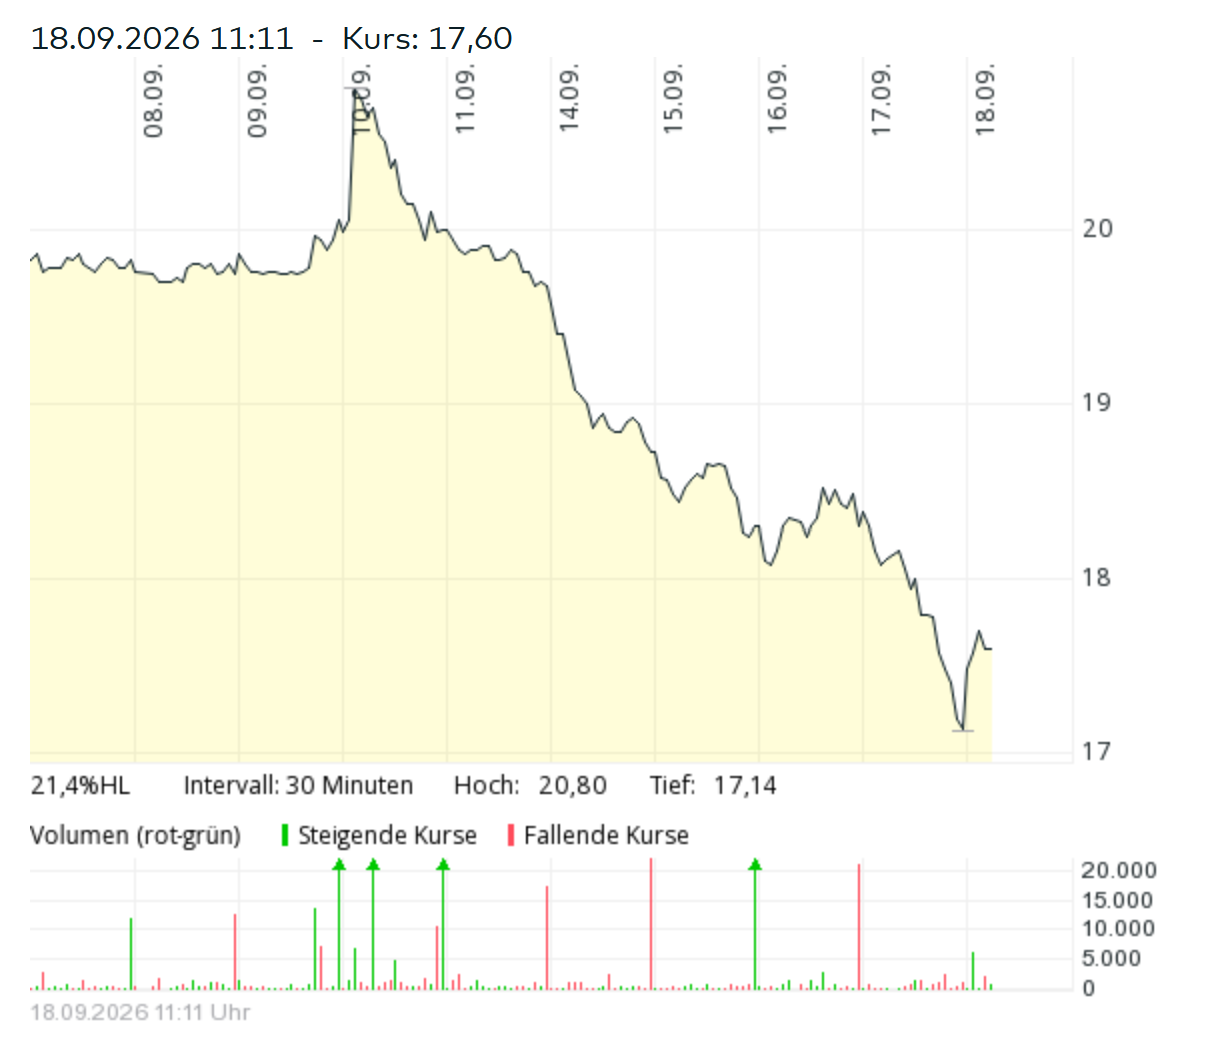
What I find interesting is that the share price didn’t react a lot on Monday’s surprise announcement, although all in all, this is quite positive for shareholders:

Similar cases in the past:

There was a very similar case in the past in France: Lagardere underwent the “same procedure”, also driven by behind the scenes activism from Boloré. The GP in that case got compensate by a share capital increase of ~8% but the shares jumped 10-15% after the announcement.

Subsequently, Lagardere was taken over by Vivendi by Vivendi and Lagardere Shareholders did quite well.

A somehow similar case was  Fresenius Medical Care, where Fresenius transformed FMC from a KGaA to a normal AG because they wanted to deconsolidate FMC and FMC subsequently performed quite well.

One can only speculate why Rubis didn’t move at all, but my guess is that the current riots in France and general Caution with regard to French stocks clearly plays a role here.

Good earnings momentum

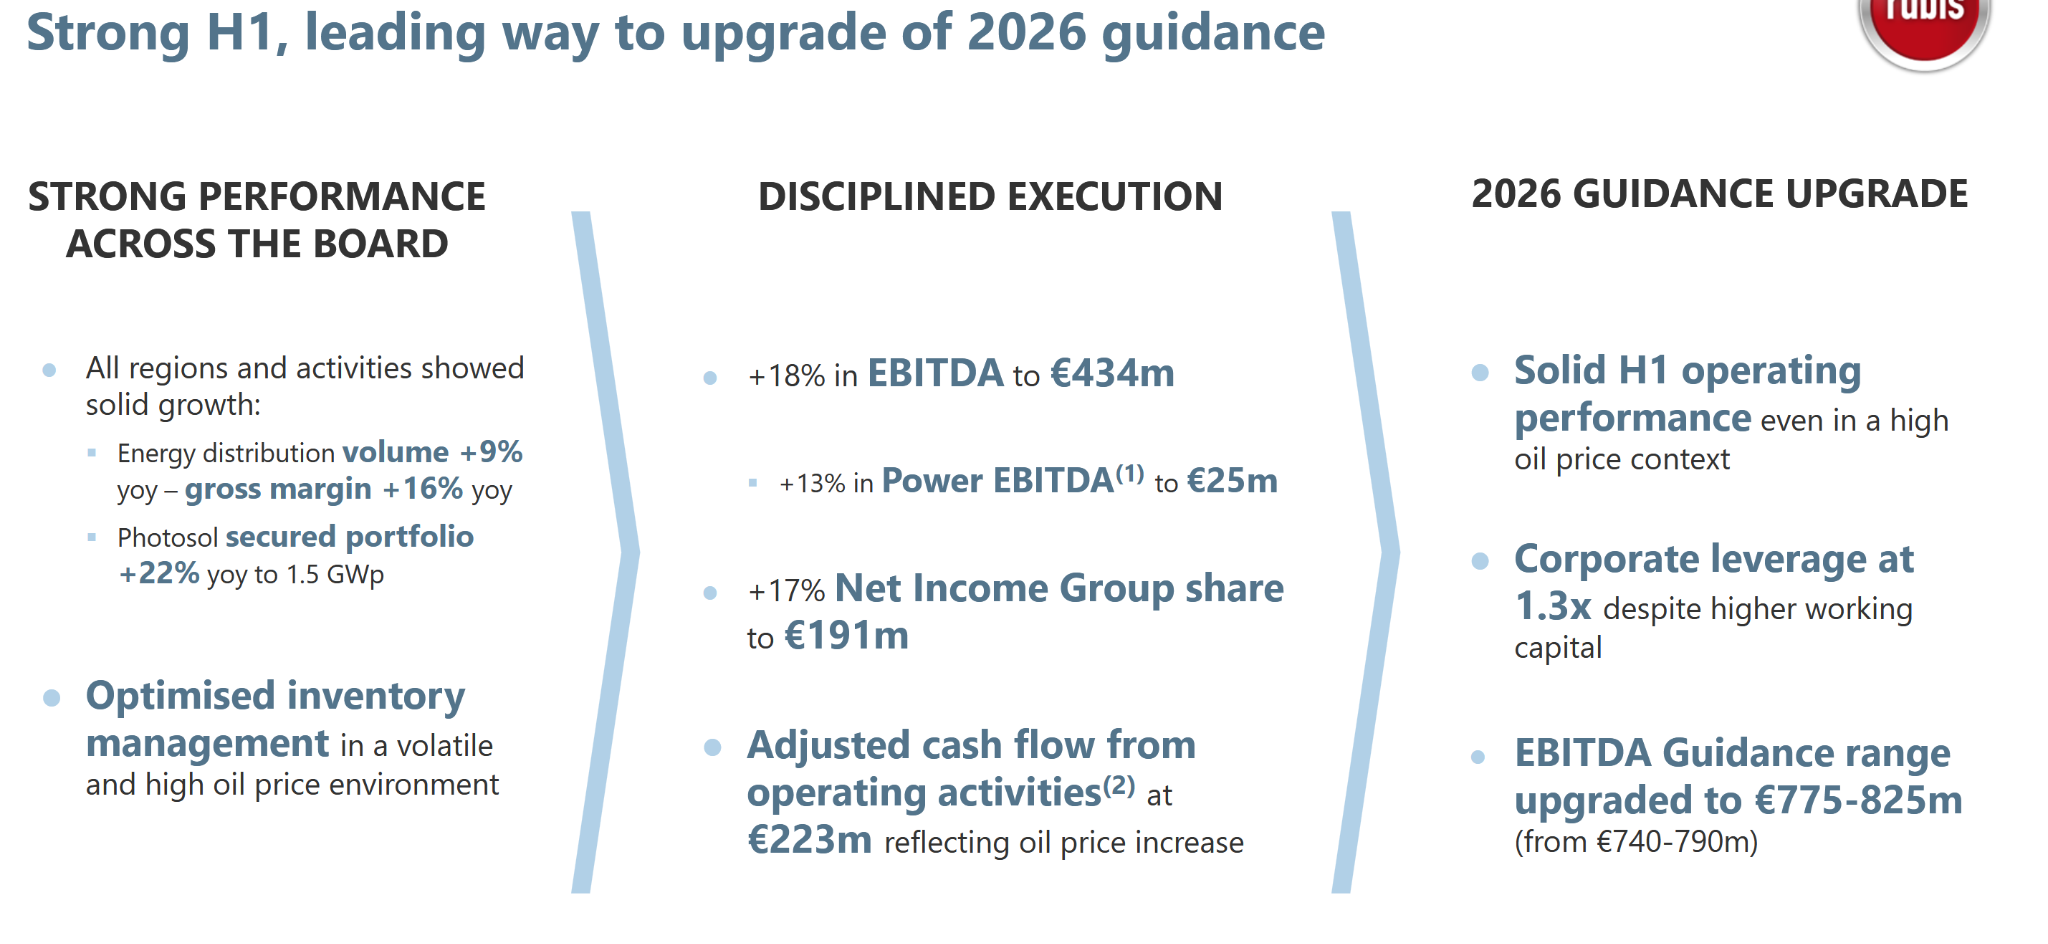
Higher fuel prices are almost always good news for distributors and Rubis is no exception here. After  decent Q1, 6M numbers looked really good an dthe increased their guidance for 2026 significantly:

Investor base

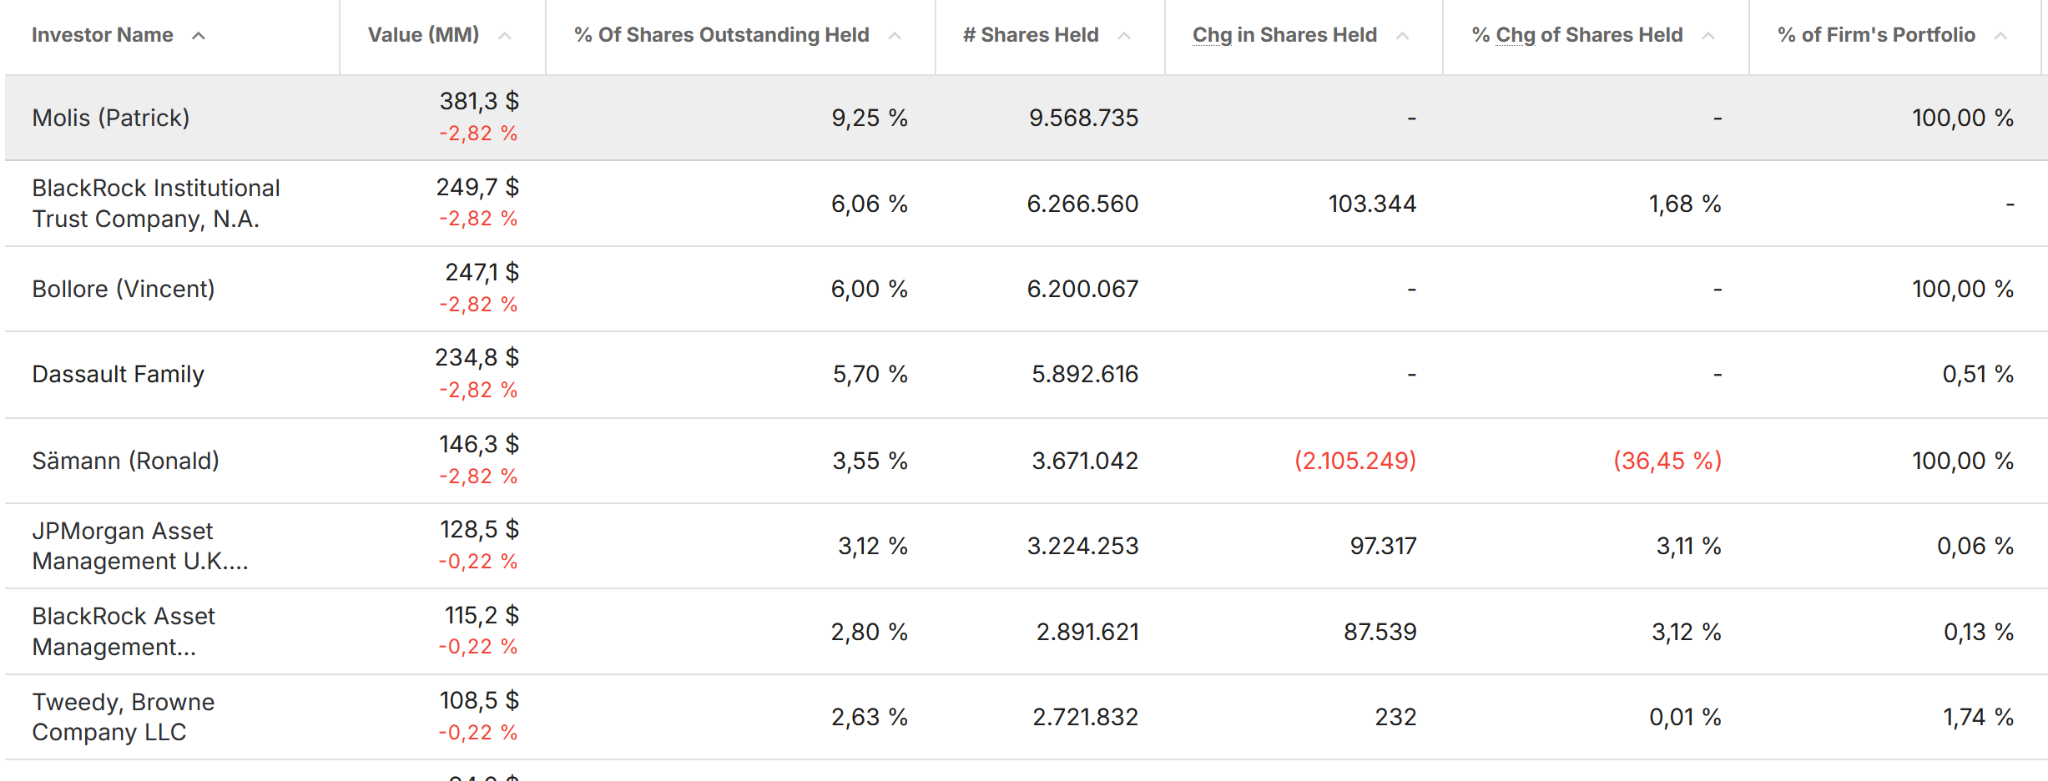
Over the past few years, some prominent investors have disclosed stakes in Rubis:

The largest shareholder, Patrick Molis is  a French Business man active in logistics who started a first position in 2023/2024. He had been openly activist in the company for some time, demanding among other things a complete overhaul of the board.

At the same time, Vincent Boloré disclosed a 6% stake. Boloré is especially experienced in African businesses. He also seemed to have been involved in Rubis in the 1990ies and seems to know Molis from a couple of previous interactions.

The billionaire Dassault family seems to own its stake already a little bit longer since 2017 or 2018. I didn’t find a lot about Ronald Sämann but he also seems on board since 2023/2024 and was actually part of the supervisory board until early this year.

Graoully has some more information on this eclectic group of shareholders in his post.

In any case, I assume that those shareholders will most likely not just sit around and be happy to collect dividends but they will continue to press for change and even more so once the structure is cleaned up.

What would a PE buyer do with Rubis

Already in September last year, there were relatively specific rumours that PE firm CVC and energy trader Trafigura were interested in taking over the company.

As we have seen with my previous portfolio company DCC, especially LPG and fuel distribution are highly attractive businesses for PE companies as these businesses are stable, can be leveraged and there is still ample room for consolidation.

In Rubis’ case, those two businesses would be clearly the main targets. The Renewable business would most likely be sold to a more specialised renewable fund or energy company, although right now, there are quite some renewable assets on the market.

That leaves us with the Bitumen business for which the natural buyers would most likely be competitors like Colas or the Swedish guys

My “sum of parts” estimate for such a scenario would be at least 50 EUR per share based on recent transaction multiples including DCC. Although one has to mention that Rubis’ geographic footprint makes this analysis a little bit more difficult. For those more exotiv locations, the number of buyers is clearly smaller, however potential growth in these countries is also much higher than in saturated markets.

A quick win of any “activist” would in my opinion be to spin off the renewables business and leave the Fuel and bitumen business together which would be a veritable cash machine. This could also lead to a decent rerating of the stock.

Return expectations

Other than a direct M&A “arbitrage” situation, the current situation at Rubis is a little bit more fluent.

My base case looks as follows: I look at a time horizon of 18-24 months. Within this time horizon I expect to:

  • receive 2 dividends of ~6% each
  • expect that the stock will reflect the structural improvement after the AGM has approved the change in december which should lift the stock price between 10-20% (average based on similar situations in the past)
  • expect at least some discussions about potential bids from either strategic players (maybe Boloré himself) or Private Equity)

My estimate for a Pivate Equity “take out value” would be around 45-50 EUR per share.

So my overall return expectation for Rubis, including dividend would be in the range of +30% to +40% in the base case including dividends.

The bull case would be a little bit higher, the bear case would be the dividend yield only.

Pro’s & Cons

So let’s summarize the Pros and Cons for this special situation quickly:

  • Operational tailwind with 18% profit increase in the first 6M 2026
  • Clear catalyst with structural change but so far not priced in at all
  • Stock is relatively cheap and offers an attractive dividend yield of 6%
  • After the restructuring, high likelihood of “value accretive” M&A activities due to the presence of strong activist investors and already existing interest
  • almost no exposure to French economy as such and French bond spreads

+/-  in general negative sentiment towards French stocks which limits short term upside

  • exposure to FX fluctuations and Hyperinflationary jurisdictions
  • PV assets are maybe not so easy to sell at a good price right now
  • some residual risk that the restructuring will not happen or be delayed because of the amount of the proposed compensation

Summary & game plan

Overall, I find the set-up quite interesting as an “early stage” special situation, despite the exotic geographical footprint of Rubis.

The relevant dates are as follows:

From an operational perspective, Rubis will announce a Q3 trading update on November 3rd. I assume that this trading update will confirm the positive trajectory of the business. The upside case would be a further upwards revision of the expected 2026 profit.

The most important  step will be clearly the formal approval of the restructuring in the special AGM on December 9th. Maybe this triggers some revaluation already, especially if maybe the compensation for the former “GPs” can be reduced a little bit.

I would then expect over the course of 2027 that we see more discussions on how to “catalyze” the value of Rubis. Either through renewed negotiations with CVC and Trafigura or some other actions.

My “long stop” date for this will be Mid 2028. If nothing happens until then, I will get out in any case.

Overall, I find this set-up attractive enough to allocate a 2,5% position of the portfolio into Rubis at the current price of ~35,50 EUR per share.

I partially financed the position with further sales of STEF, which has much more exposure to France, high French interest spreads and high fuel costs.

Update Special Situations: Norma, Paypal & NEW: Delivery Hero (No action)

Norma Buyback Tender:

The original write-up is from mid-June and can be found here. Plus a same day update here.

Looking at the share price development, I clearly got out too early from this one at around 18,85 EUR per share plus dividend:

Overall, I was clearly lucky with the timing of the entry. I closed the trade early because first, I could lock in my expected return and secondly, I was a little bit “off grid” and had limited ability to react during the trading period of the tender rights.

The main difference to my initial case was that the tender price had been further increased from 20,87 EUR to 22,35. Interestingly, for the remaining shareholders, this is not really positive as more cash went to selling shareholders.

I had checked a few times during the trading of the tender rights and they were trading relatively close to their intrinsic value.

What I find quite surprising is that at the time of writing, the stock is still trading pretty high above my  “undisturbed” value before the announcement. And how long it took to come down from the “inflated” tender price. I have to confess that I don’t fully understand this.

Paypal Stripe/Advent offer Special Sit:

Here clearly my expectation of a higher bid from Stripe/Advent did not materialize but they rather dropped their effort.

As mentioned in the comments of the original post, I directly sold after this became public as I have no opinion on the longer term development of Paypal. This is what I wrote back then:

However one more thing is important to mention: This is a special situation investment for me. So if for some reason, Stripe & Advent withdraw their bid, I will sell, no matter what. For a “Value investment” I still find Paypal too hard at this stage. 

Luckily for me, the stock did not drop down to the “undisturbed” price of ~45 USD. So I could get out with a relatively modest single digit loss in this case.

I have to admit that I was already feeling a little bit insecure after Stripe closed the OpenRouter acquisition for ~7,5 bn USD a few days earlier. Stripe is a great company but they don’t seem have an unlimited budget for M&A as a financial intermediary.

As in all of these cases, there is always the risk that a case doesn’t work out. In my opinion, the most important part here is to stick to the original plan (i.e. sell) and try to find out if I have made any “a priori mistakes”.

In this case, the only mistake was maybe not to reduce the position after the open router acquisition from Stripe.

For the future, any public take-over situations with Stripe need to trade at a wider discount to account for this episode.

Delivery Hero/Uber take over Special Sit

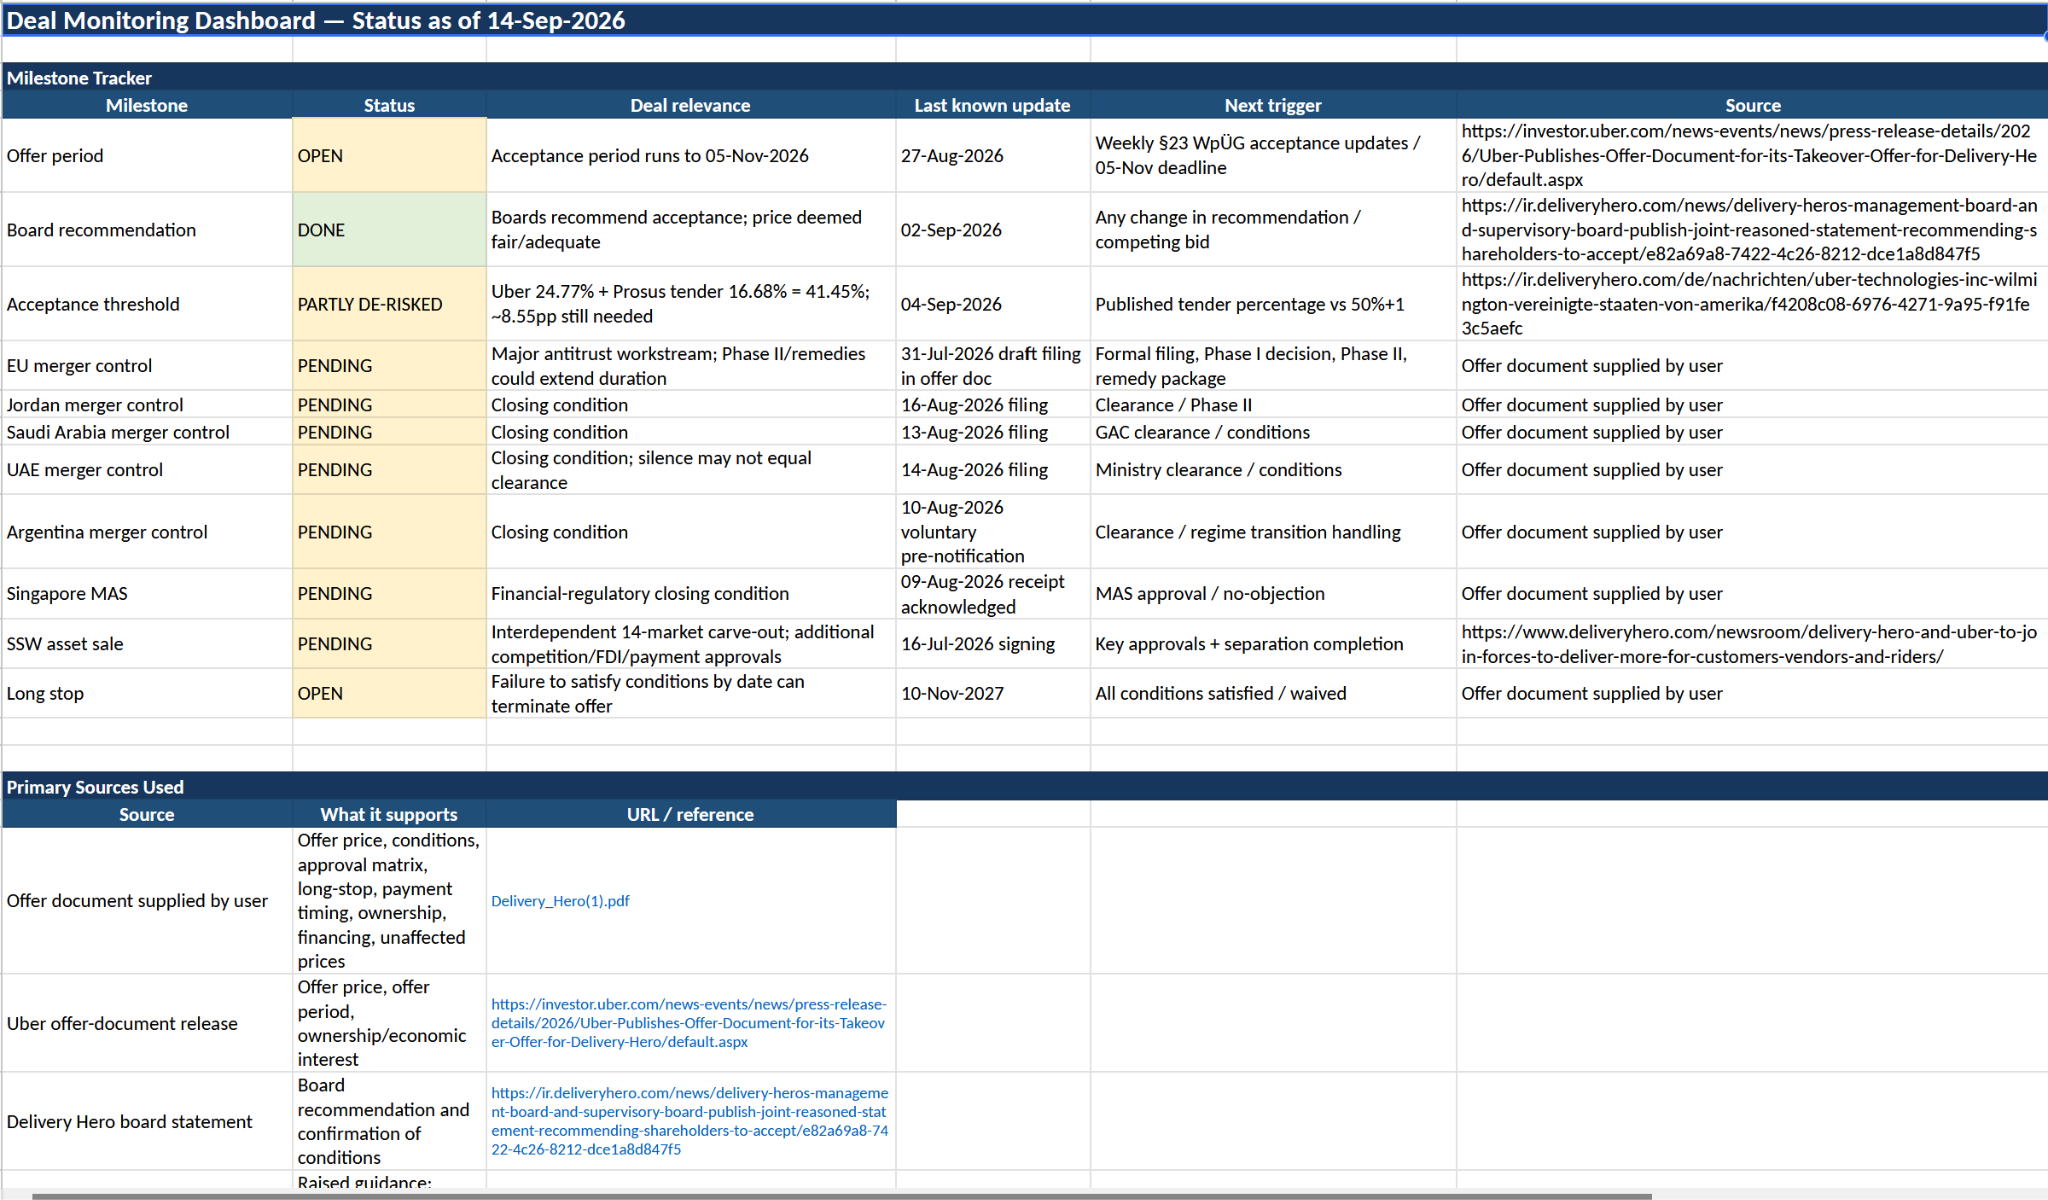
As mentioned in my weekly links post, the UBER/ Delivery Hero take over could be an interesting Merger “Arbitrage” Special Situation.

In a nutshell, Uber owns currently around 25% of DHR outright and has launched a take-over offer in late August at an offer price of 41,5 EUR.

Expected closing of the deal is in the second half of 2027 and the acceptance hurdle for this offer is only 51% which Uber seems to have in the bag already.

The main risk of the transaction is clearly a relatively complicated merger control and approval process in many countries and especially an intermediate step where part of DHER’s business needs to get carved out and sold to a Private Equity shop called SSW Partners.

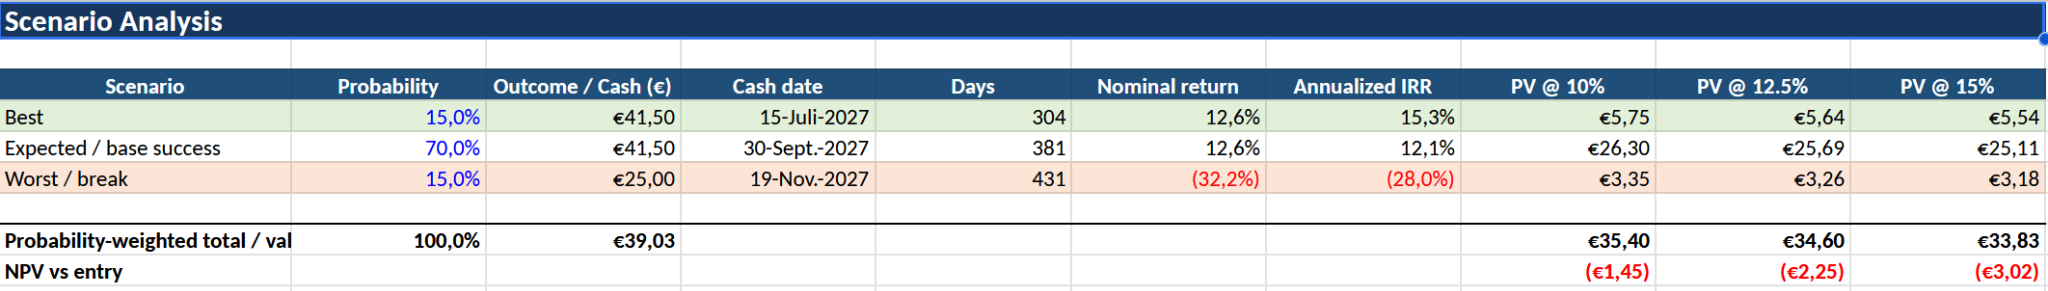
At the current share price of 36,85 EUR/share, the “spread” to the 41,50 EUR offer is 12,6%.

This needs to compensate for:

  • a relative long time horizon (long stop November 2027)
  • a relative high premium to the undisturbed price (+100%)
  • and the aforementioned deal complexity

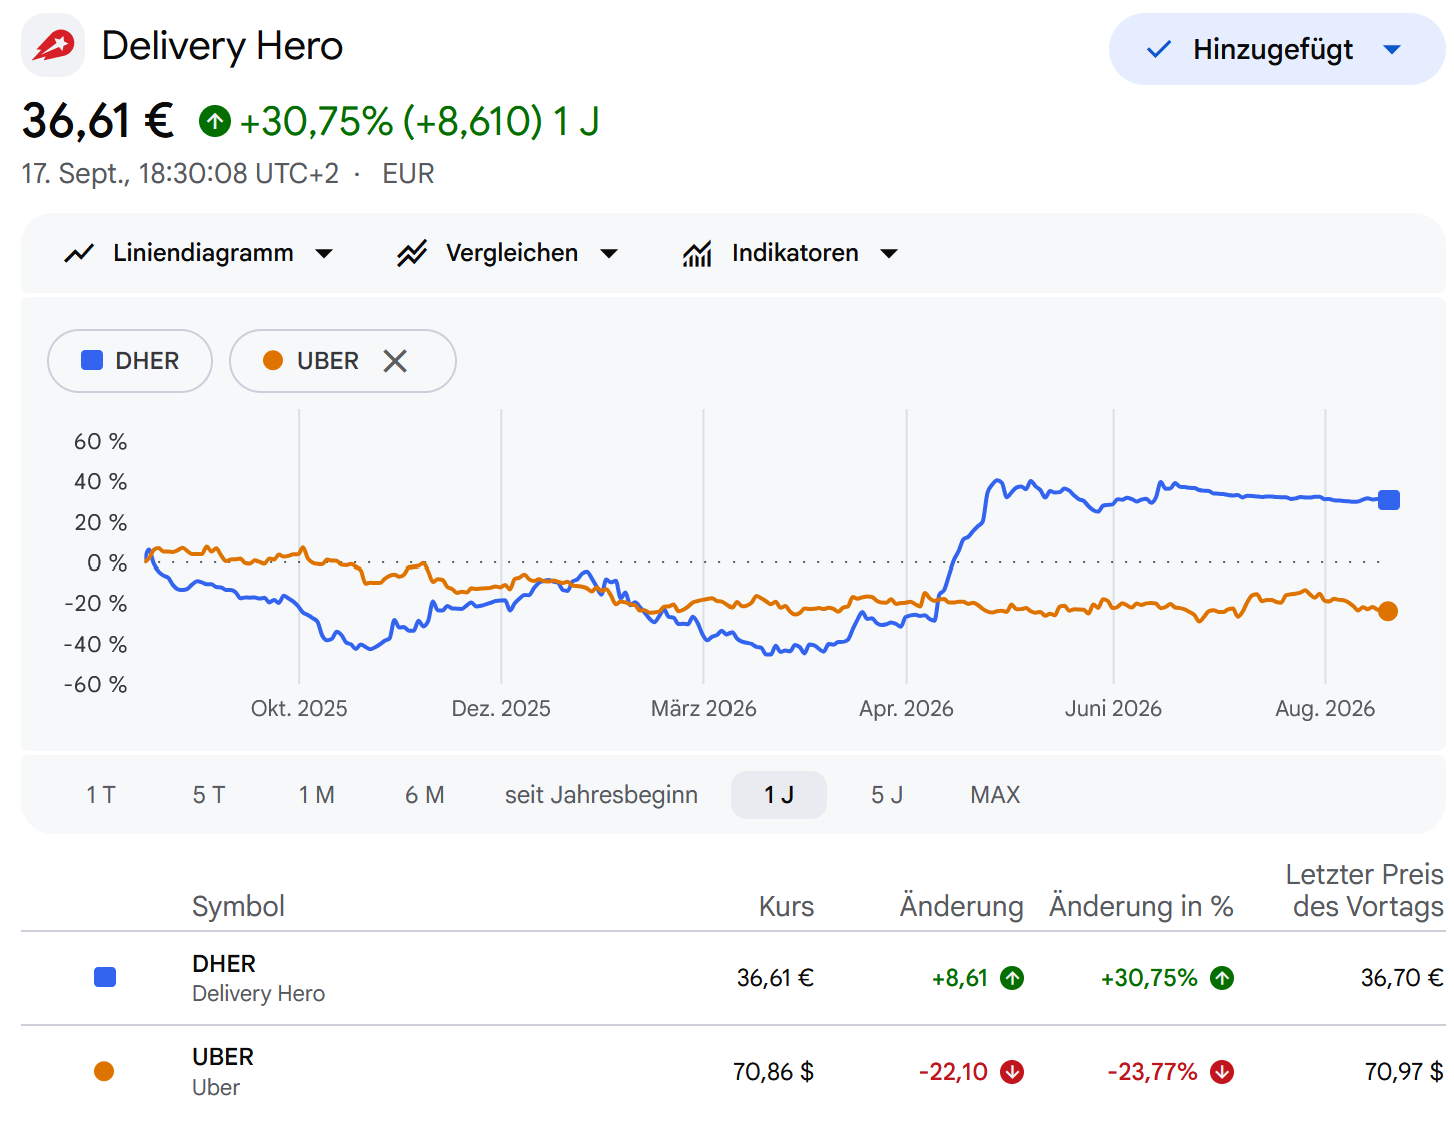
This is the stock chart from Delivery Hero which shows the significant bid premium:

All my 3 AI Tools (Claude, ChatGPT & Gemini) were recommending not to establish a position due the complexity of the deal (carve-out requirement) and the significant downside in a “no deal” scenario if the “cost of capital” is 10 to 15% p.a.

Personally, I think especially countries like UAE or Saudi Arabia could become more risky with regard to merger clearance when the war in Middle East continues to spread.

So in this case I actually follow the advice and sit on my hands. I will revisit this by end of October to see if it has become more attractive, either by a lower price or some fundamental improvements.

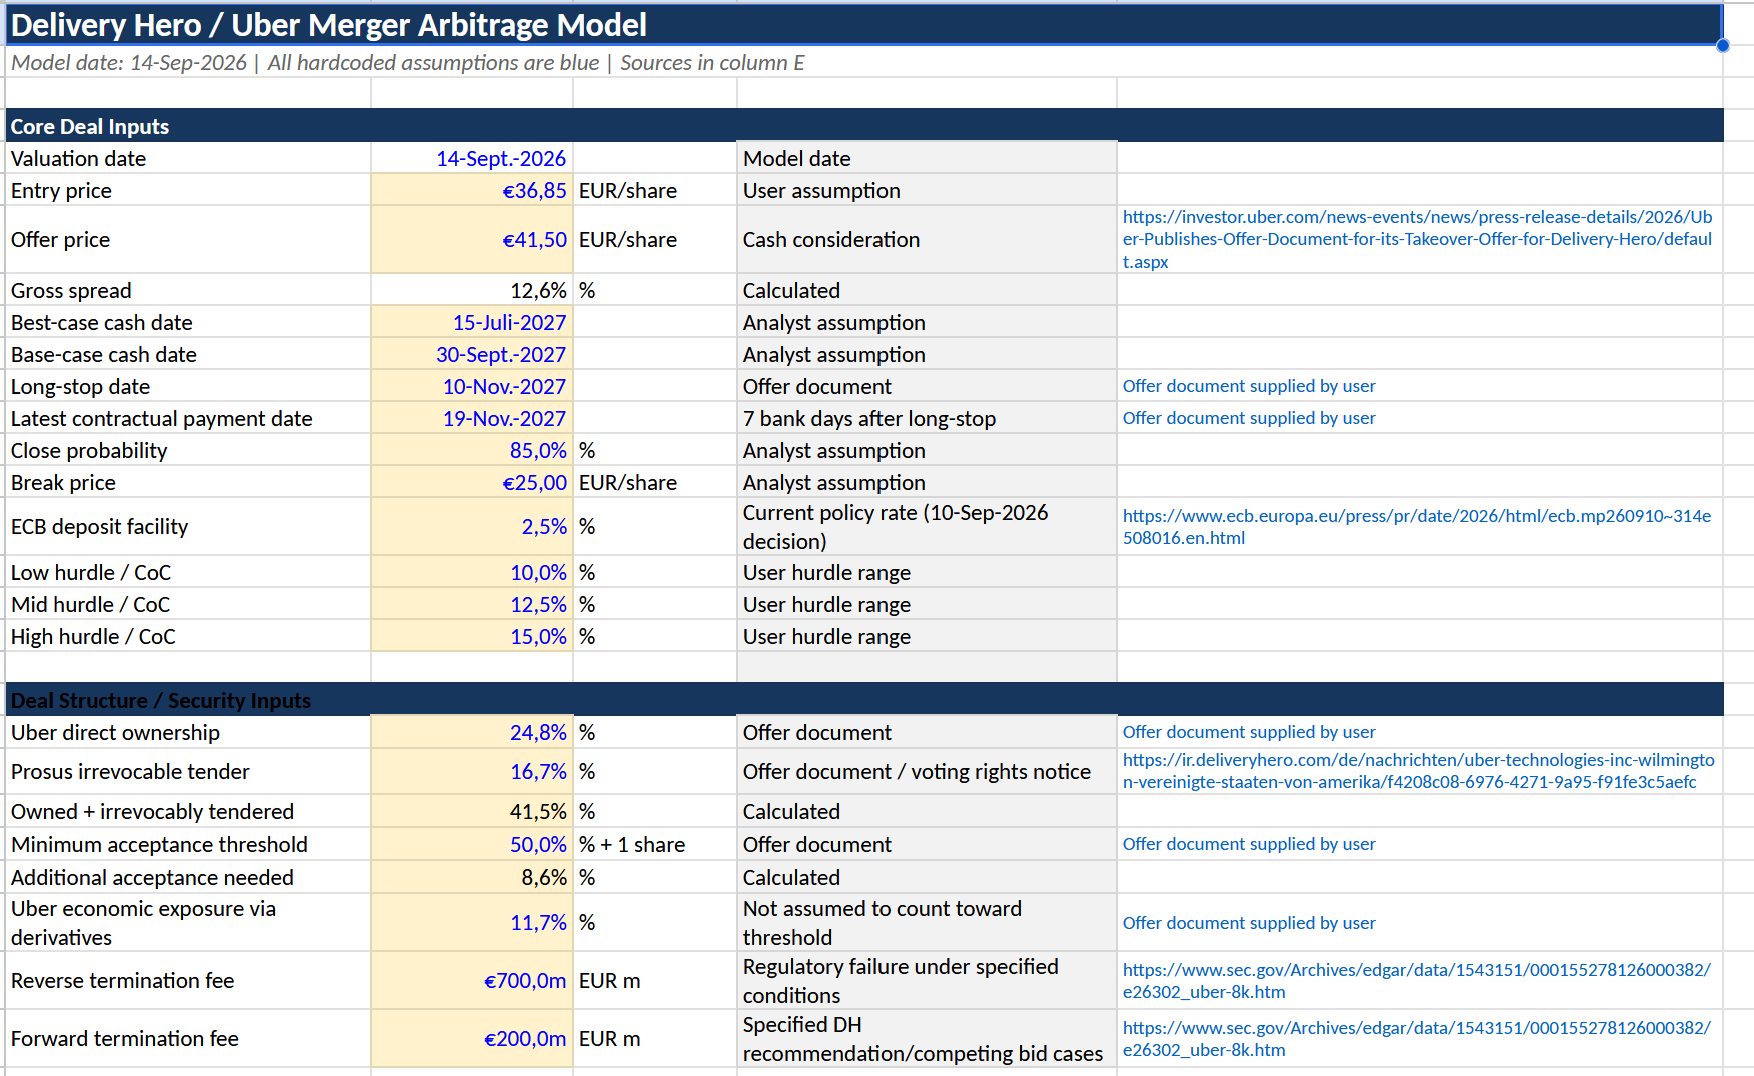
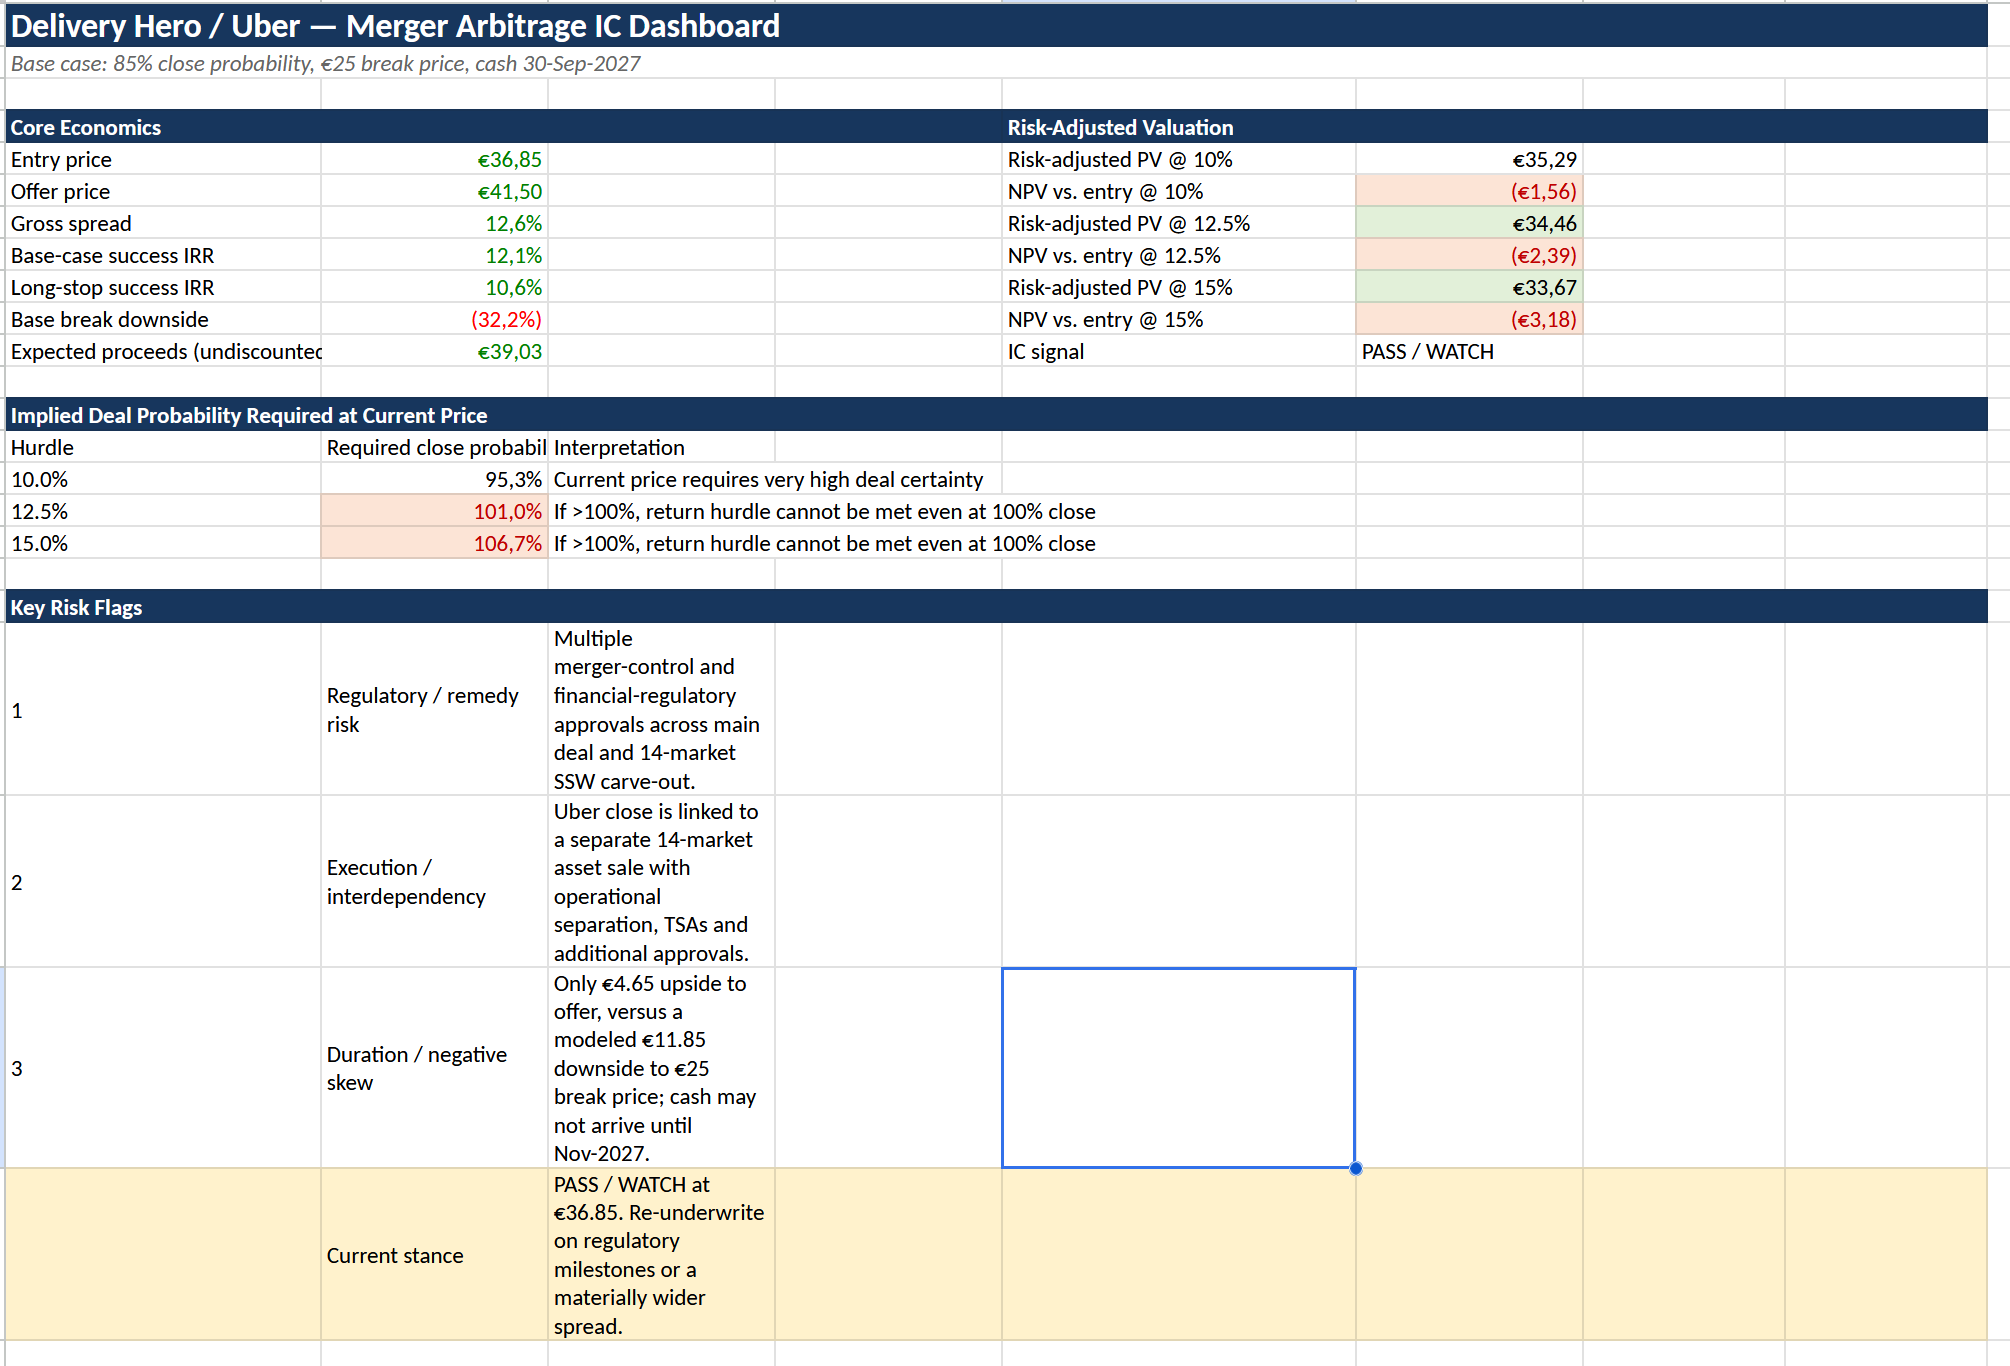
Interestingly, both ChatGPT and Claude offered to build an Excel spreadsheet. Here are some screenshots from ChatGPT which look very professional:

I didn’t check all the formulas, but it seems to be quite good.

In addition, ChatGPT also is checking now 2 times a day for updates.I guess Claude can do the same easily.

Although AI tools don’t change the Special Sit game completely, it clearly makes a more “equal playing field” as it reduces the effort to get into this.

The main risk that I see is that the motivation to actually read relevant documents goes down even more and that it is hard to see if the AI Agent makes mistakes or catches everything.

Metro take over – quick assesment

After reading “Merger Masters” I decided to practice my new found knowledge a little bit and apply it to Metro. My long time readers know that I bought Metro as a spin-off and exited with a pretty painful loss.

The Czech billionaire Daniel Kretinsky, who became Metro shareholder a year ago, made a voluntary offer of 16 EUR per Metro common share and 13,80 EUR per pref share. Little is known how Kretinsky actually became a bilionaire, as he is now only 45 years old. Maybe it helped that he married the daughter of another Czech billionaire, Petr Keller. Some call him a Czech “oligarch”. Up until now, he mostly invested in the energy space, most notably buying coal assets in Germany.


Metro Management has already rejected the offer as too low, so the deal is clearly a “hostile” one.

From the Merger Masters book, I use the initial checklist to quickly assess the opportunity:

  1. What is the srpead ? What is the annualized return ?
    –> 0%, stock price trades at offer price at the time of writingm the pref share even above the offer price
  2. What are the regulatory issues/hurdles
    –> Most likely no big hurdles. Acquirer is not active in this industryy
  3. What are the conditions of the agreement
    –> unlcear. Unspecified “Minimum acceptance” level
  4. What is the strategic rational of the deal
    –> unclear. Buyer has no experience in retail. Most likely “opportunistic” and/or real estate driven
  5. What is the downside if the deal breaks ?
    –> – 10 to -15% (my estimate)

So based on this first assesment, the situation doesn’t look very interesting. For a hostile deal one should expect some sort of premium which doesn’t exist. The major issue is clearly that there is little information about the acquirer and his motives.

On the other side, the market seems to expect clearly a higher bid, otherwise the current price makes no sense. However I cannot think of any other bidder for Metro but maybe I am wrong.

So my assesment here is clear: At this price the risk/return profile for Metro is not worth it and I’ll pass.

P.S.: Does any reader know how the current legal situation is for German Prefs ? WIll an acquirer need to pay the same price as for the common shares


Special situation: Innogy Tendered Shares (IGYB) -(very) Cheap Optionality ?

Background:
The guys from Paladin AM have outlined the Innogy case very nicely on their blog (in German): Intro & Update

I’ll try to summarize it in my own words:

Innogy, the renewable energy spin-off of RWE is in the process of being taken over by competitor E.ON. E.ON in 2018 had announced to purchase the 77% stake of RWE and has offered on a voluntary basis 36.74 EUR per share which, plus the upcoming dividend adds up to a total consideration of 38,14 EUR per share before tax. The closing of the transaction is subject to a relatively complex regulatory approval process which is already facing some delays. Most experts however think that the transaction will be ultimately approved.

Read more

April SA – Potential buyout offer from CVC: Interesting Special Situation ?

Disclaimer: This is not investment advice. Please do your own research. 

April SA is an “Old friend” on this blog. I owned the stock in the past and last time I looked at them when a rumour came up that the company is for sale in late October.

This is what I said back then:

April had shown actually pretty decent growth in Q3 and I actually considered buying some shares but maybe this is not so sustainable and the founder wants to sell before it is getting worse again ? Who knows…

My fundamental assessment of April is that they have a strong core business (French Broker) but have over extended themselves internationally and the founder, Bruno Rousset, who stepped down in 2014, does not have the energy anymore to turn this around himself.

Well, things have progressed. There had been a “beauty contest” with PE bidders and it looks now that PE shop CVC is highly interested in buying the stake of the founder and majority owner. This is from a piece of news released by April SA and  CVC end of December:

Read more

Contingent Value Rights (CVRs) – The case of the Sanofi/Genzyme CVR

As I was trying to research a little bit how to value a pipeline of drugs still in development (Actelion spin-off), I stumbled across the so-called “Contingent Value Rights” (CVRs) which are often used in Pharma takeovers.

A CVR is somehow similar to a tracking stock with the exception that the CVR often tracks a more specific item such as a single product or in case of many Pharma M&A transactions, the outcome of a certain drug development project.

Acquirers and sellers sometimes use this instrument if they cannot agree on the value of an under development drug. The idea behind is that the seller keeps the upside and the buyer doesn’t need to pay upfront for some very risky future cashflows.

Sanofi/Genzyme Lemtrada CVR

When Sanofi took over Gynzme in 2011 such a situation crystalized. This is from a 2015 NYT story:

Read more

Actelion (CH0010532478) – Merger arbitrage with a potential Spin-off “Gold Nugget” ?

Yesterday, Johnson and Johnson announced that they intend to acquire Actelion, the Swiss Biotech company for 280 USD per share.

The stock price jumped to around 272 CHF/USD right after the announcement indicating a relatively high probability of closing. J&J has enough money on their bank account and according to the press, most Actelion shareholders should be happy.

Closing date is targeted as June 30th. So if everything goes according to plan, this would mean ~2,9% yield for 5 months which is not bad but not that great either (as there are always risks) , so why bother ?

However there is an interesting specialty in this case which I didn’t see when I first looked into it. The official announcement contained this potential “golden nugget”:

Read more

Exor SpA: Buying a Reinsurance company doesn’t mean that you’re the “next Bershire”

Following my Old Mutual “sum of parts” valuation I saw the following Ira Sohn presentation of Exor Spa, the Agnelli family holding (FiatChysler, CNH etc.) as a potential  “Sum of part” value investment.

exor_logo_dec_2013

To summarize the presentation  in my own words:

  • Exor Spa is basically a “Berkshire like” company at a “Graham” valuation
  • Exor is managed by a “great capital allocator” and trades at a discount as people see it as an Italian company
  • After the acquisition of Reinsurance Partner Re Exor should trade at similar valuations as Berkshire or Markel
  • Big upside potential as FiatChrysler, Ferrari (and CNH) are severely undervalued (“Coiled springs”)

The study sees a potential upside of several times the current share price. They forecast a 150 EUR NAV per share (vs. ~50 EUR now and 30 EUR share prices), driven by a quadrupling in value of the FCA and the CNH stakes.

Read more

Old Mutual Plc (ISIN GB00B77J0862): Buy one, get four ?

In the blog I looked in the past at a couple of “sum of parts” situations (Alstom, Viel, CIR SpA but I never invested in one. Why ? Because if nothing happens, a perceived discount can remain for a long time. So for a sum-of-part investment, a “catalyst” has to be on the horizon.

Old Mutual

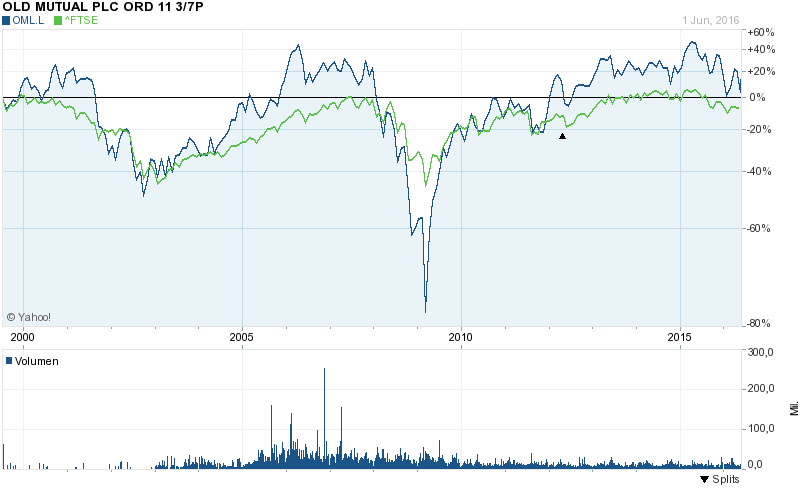
As many other Emerging Market exposed financial companies, Old Mutual did not create a lot of shareholder value over the last couple of years as the chart clearly shows, although they performed better than the overall index:

old.

Read more

« Older Entries