Category Archives: Short

Quick updates: Rubis, Fielmann, Auto Trader & Rightmove

As I was on vacation last week, here is a quick summary of some quarterly updates that were released last week for companies in my portfolio:

Rubis:

Rubis reported a Q3 trading update early last week. As to be expected, the numbers continued to be quite good.
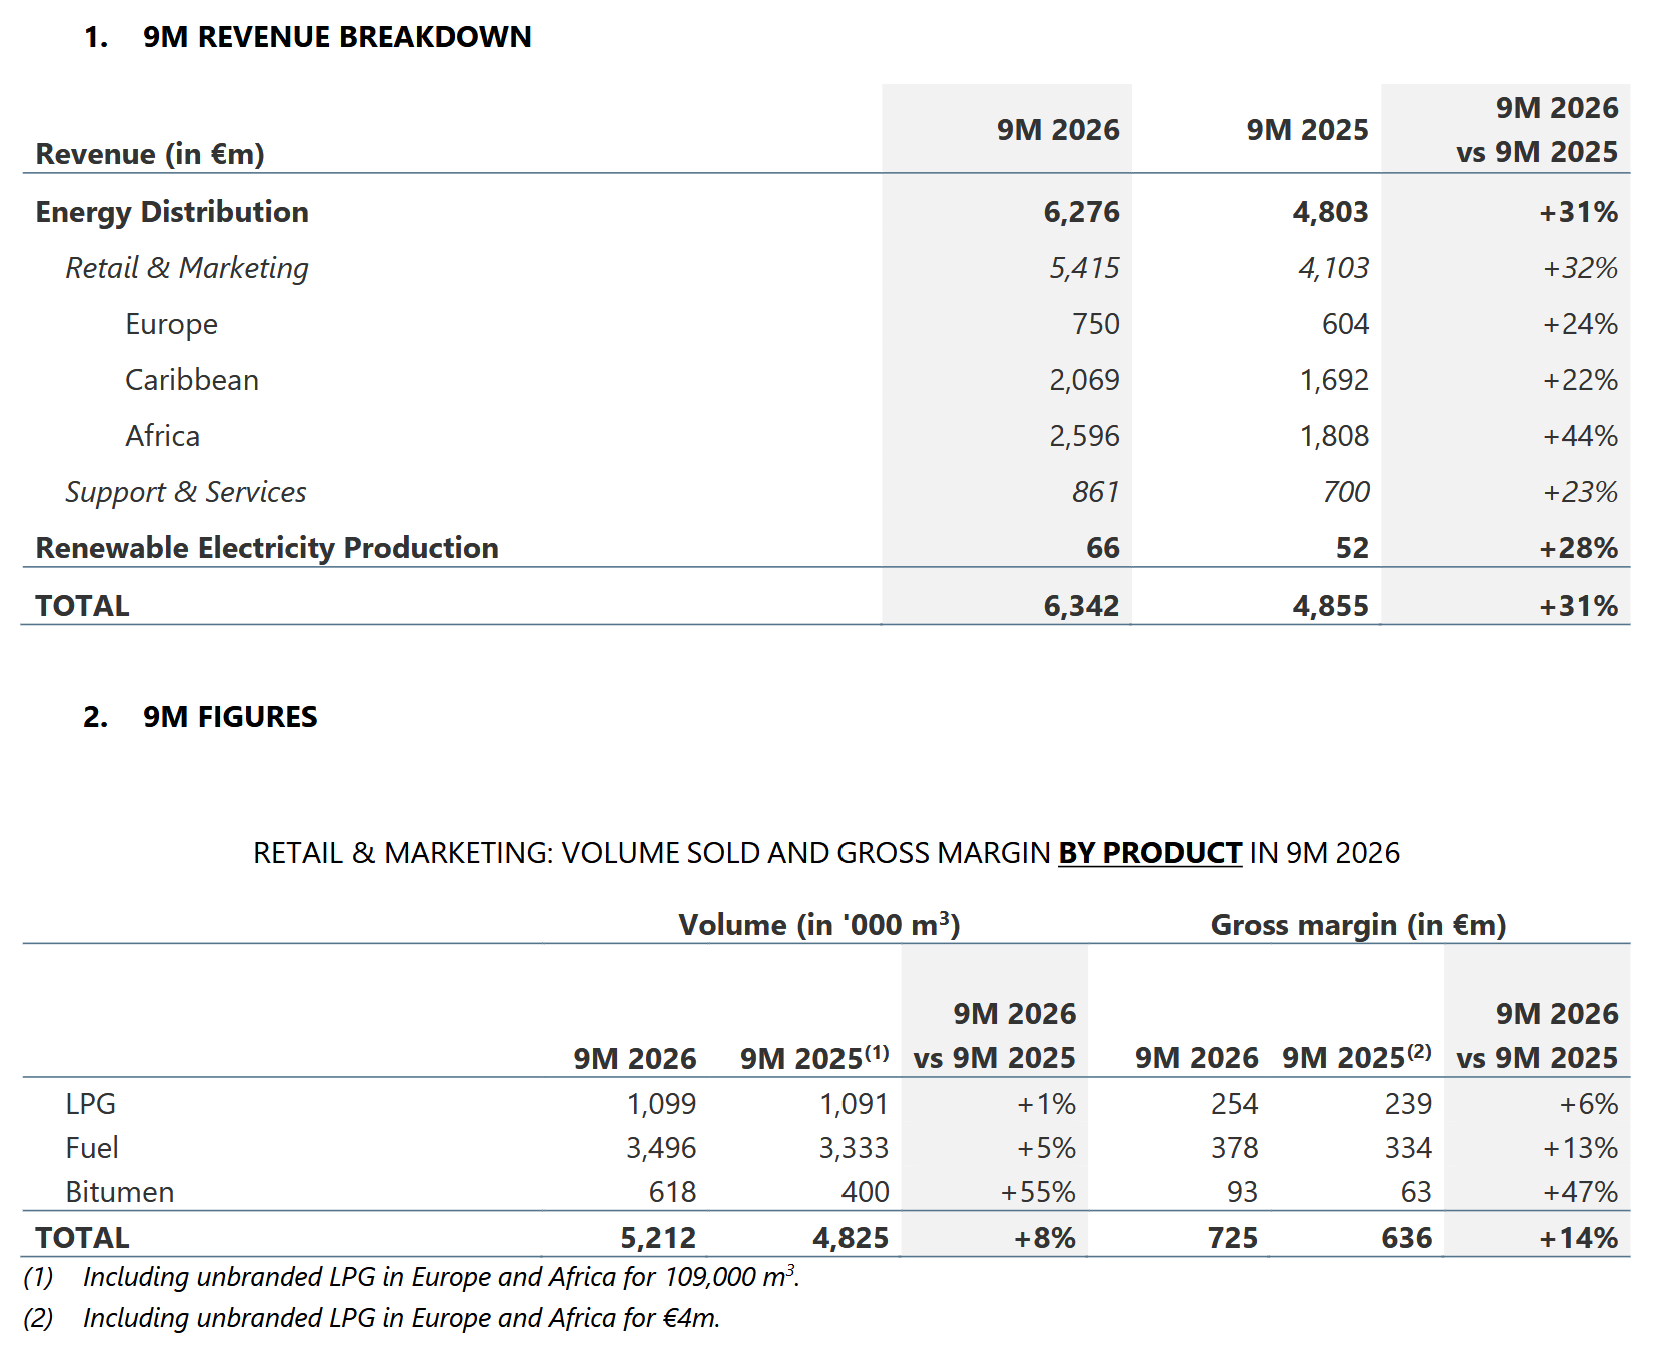
While revenue is influenced by the current oil prices, the more important numbers are volumes which are up +8% and Gross margins which are up +14%.

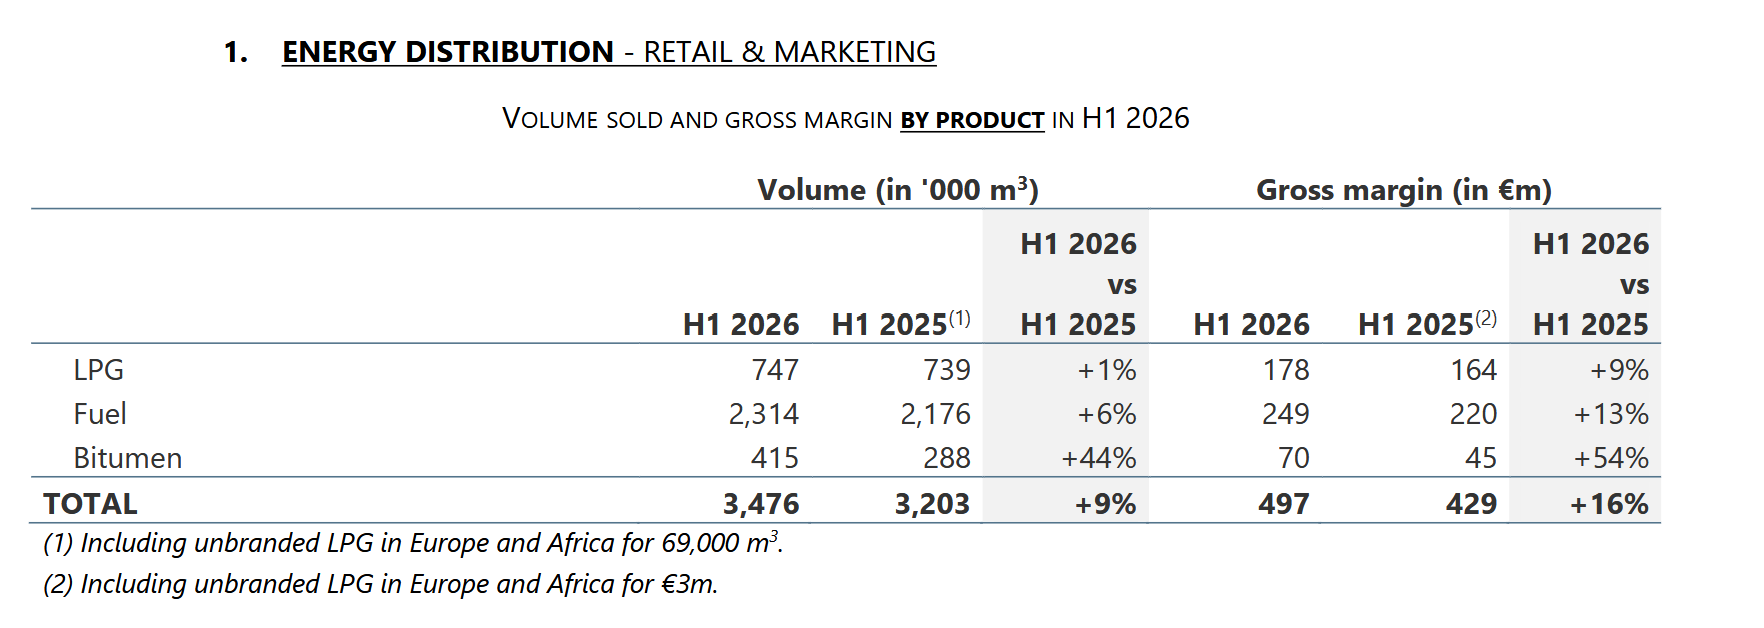
If we compare volumes and Gross margins with the 6M numbers, we can see that growth has decreased a tiny little bit:
But Rubis has confirmed the increased guidance from mid year.

They have also published the full set of documents for the December 9th special Shareholder meeting, so it seems that this is going according to plan as well.

The “Governance Roadshow presentation” nicely summarizes the new Managment and Supervisory board structure and Management incentive plans.

So from my perspective, the Rubis case is developing according to plan.

Fielmann:

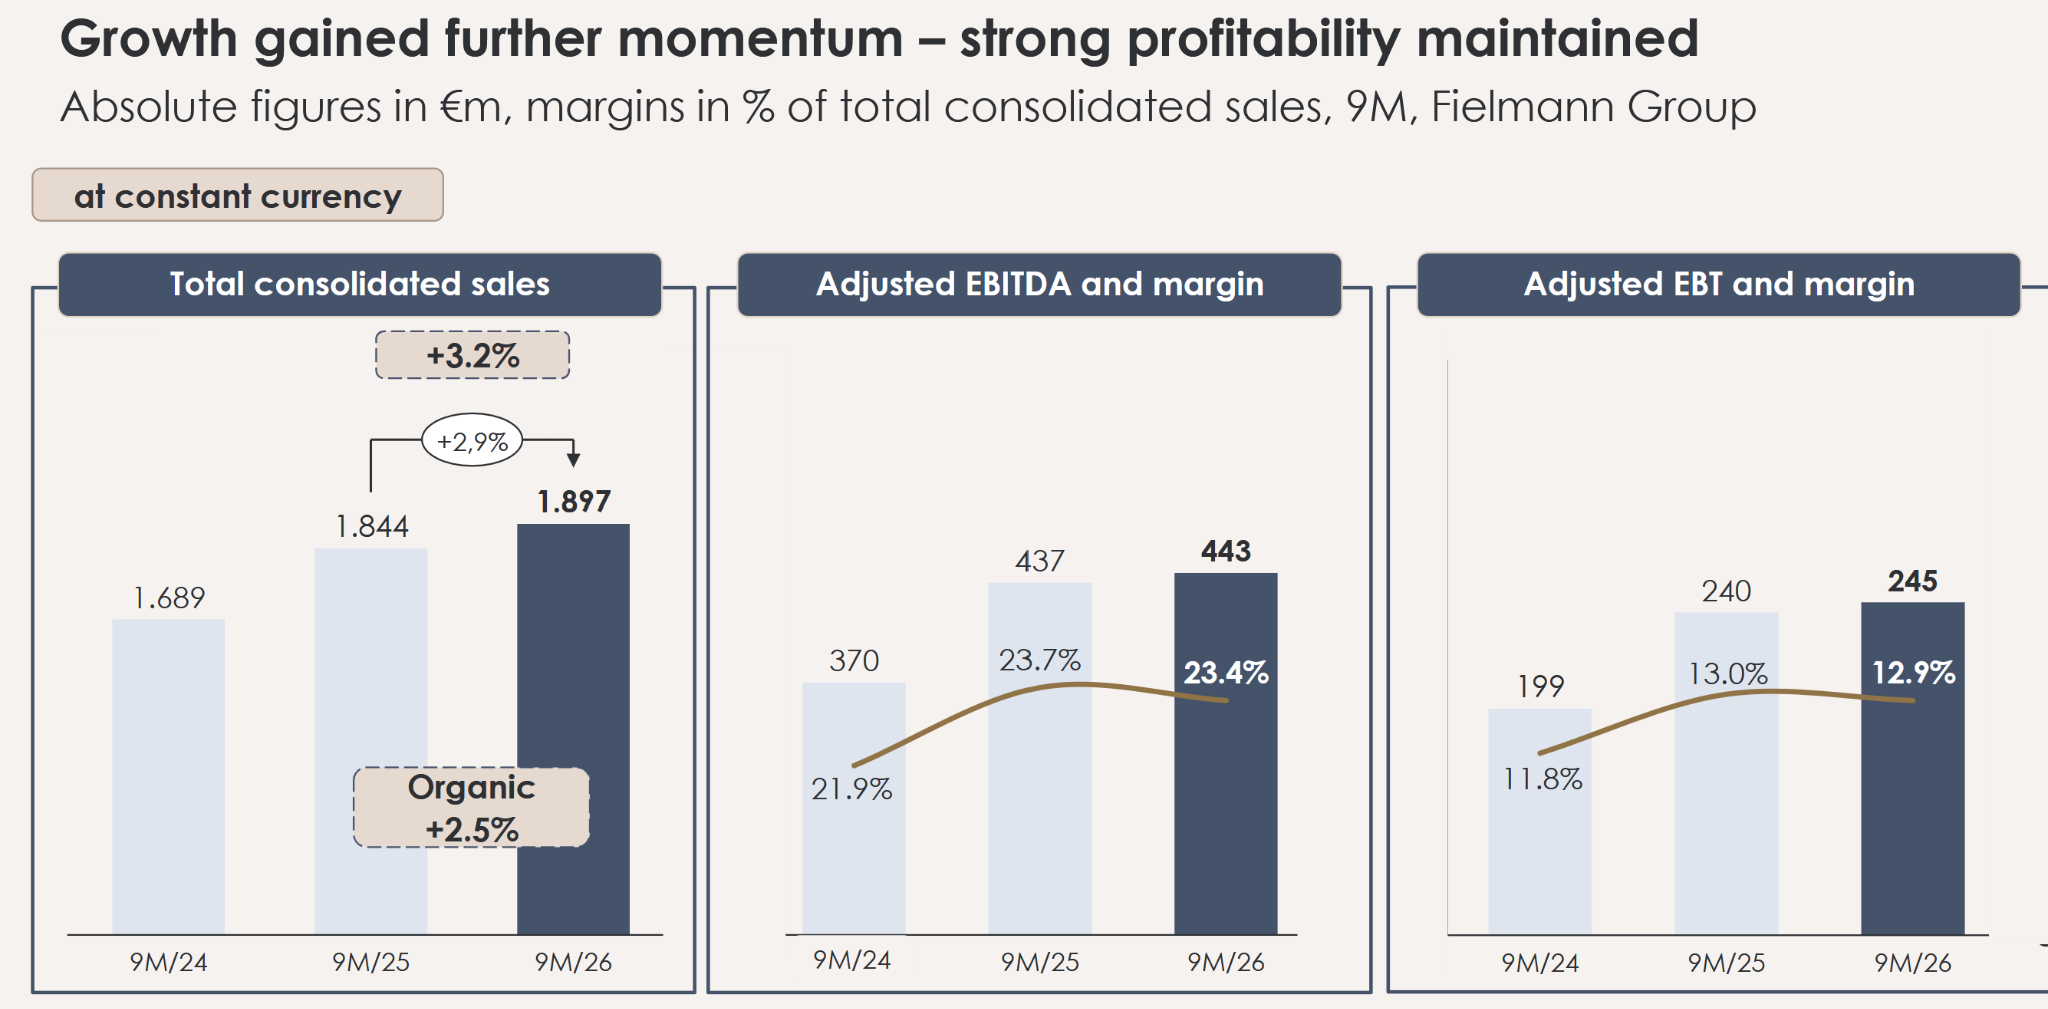
After EssilorLuxottica published decent Q3 numbers already in October, Fielmann came out with their Q3 numbers early last week.

Organic sales growth recovered from the low 6M numbers:
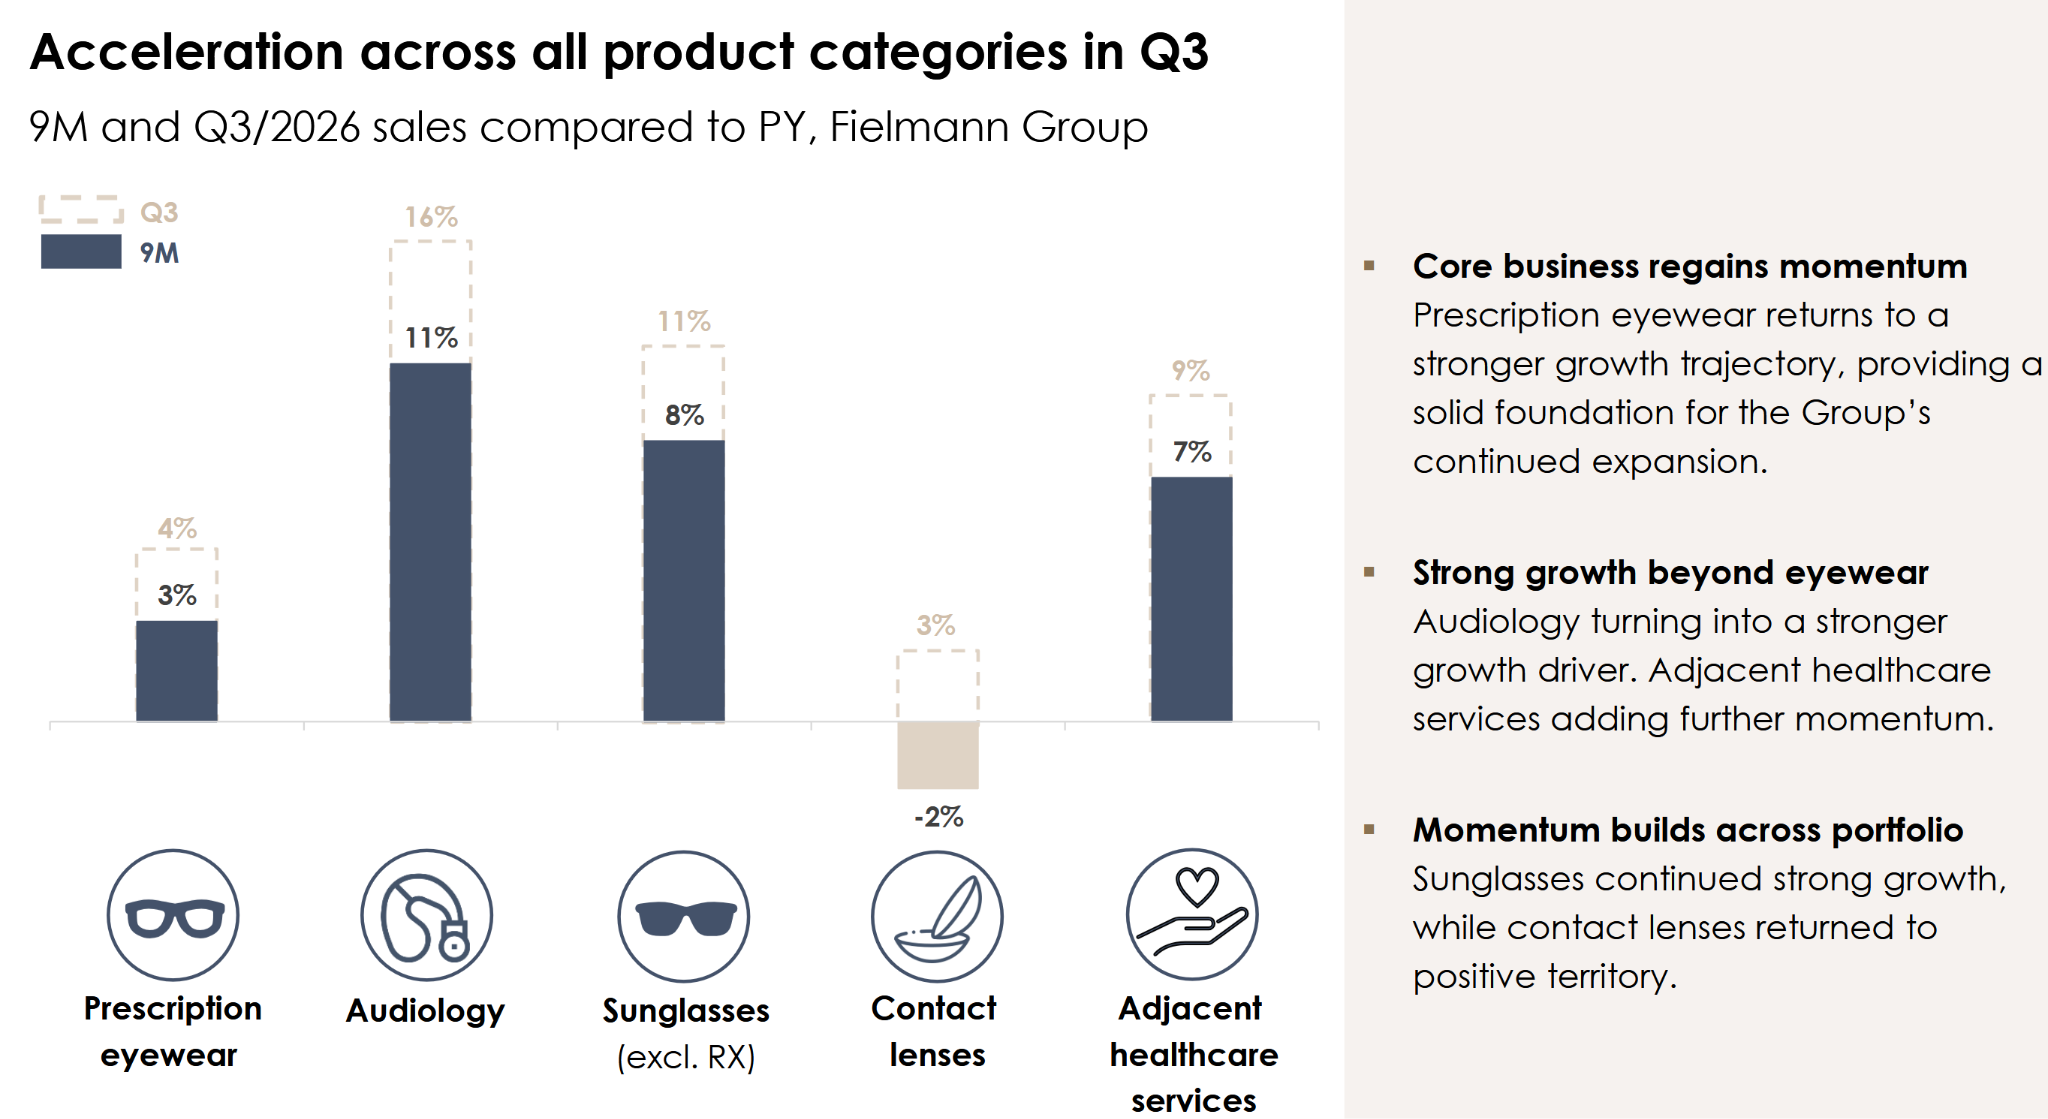
Interestingly, the Hearing aid products showed the largest growth, followed by Sunglasses:
The only negative aspect here is that the US business didn’t grow and profitability declined as they are investing into new store concepts.

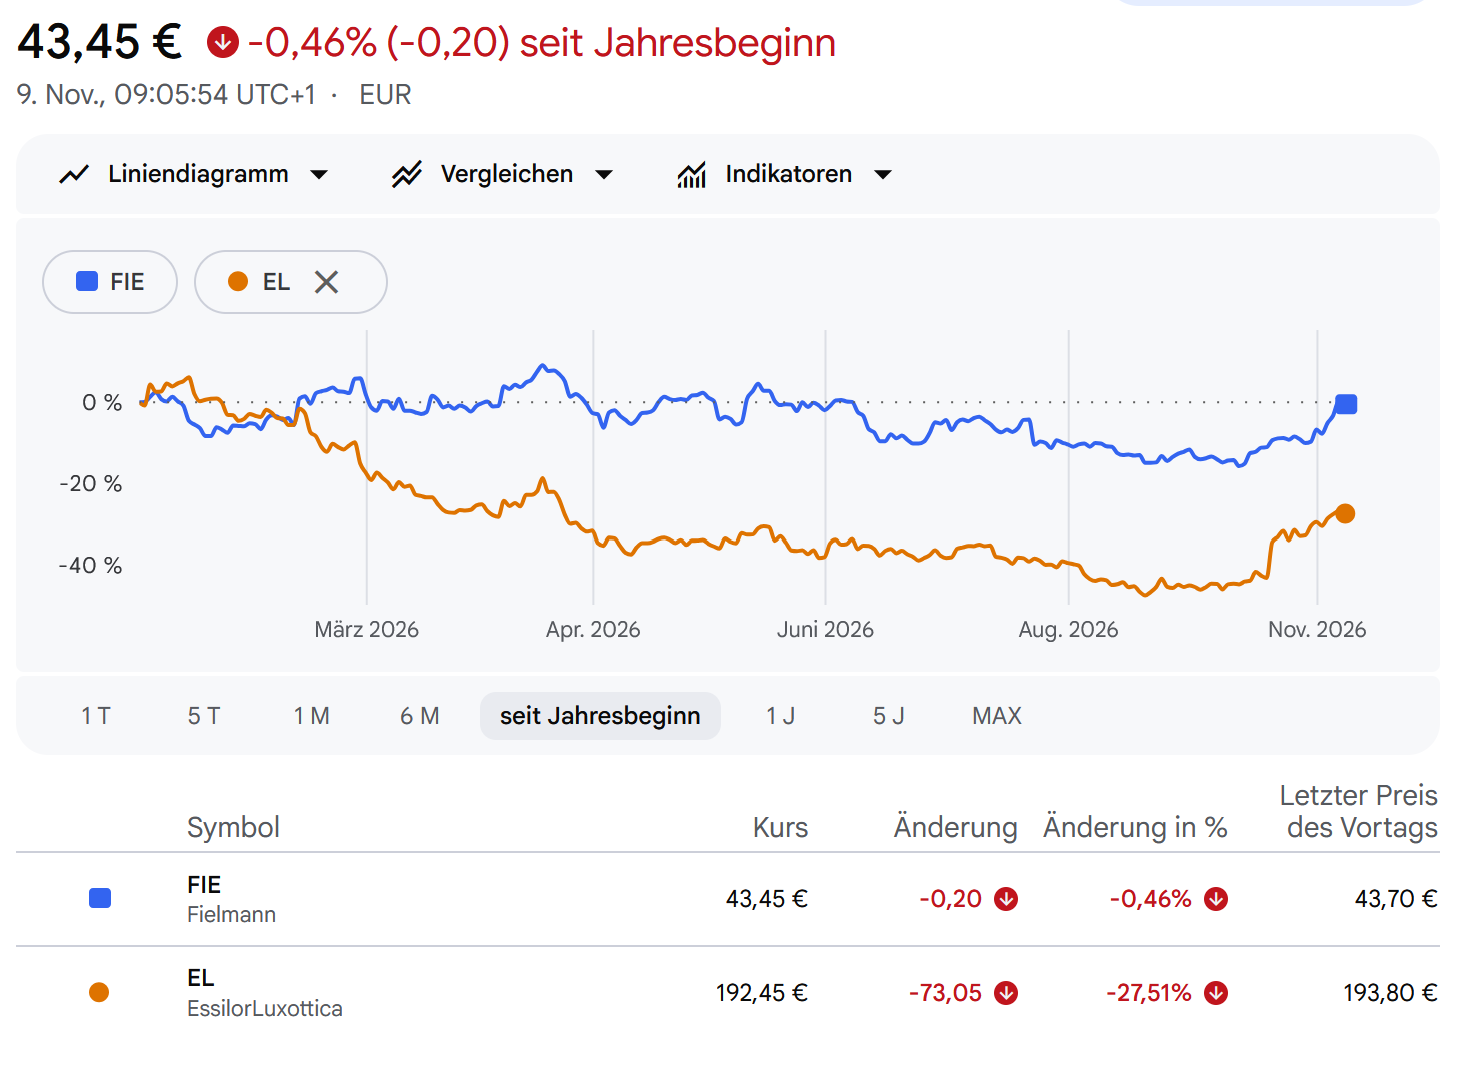
Filemann’s share price is now back to flat YTD while Essilor has still some way to go to reach the level from the beginning of the year:
For Fielmann, it seems that they will most likely reach their 2026 targets, but the US business still seems to be in a turn-around mode, which maybe explains the exit of the US business head earlier this year.

Auto Trader

My “Portal Pain Basket” member Auto Trader released HY numbers last week. The results are only “so so” at a first glance:
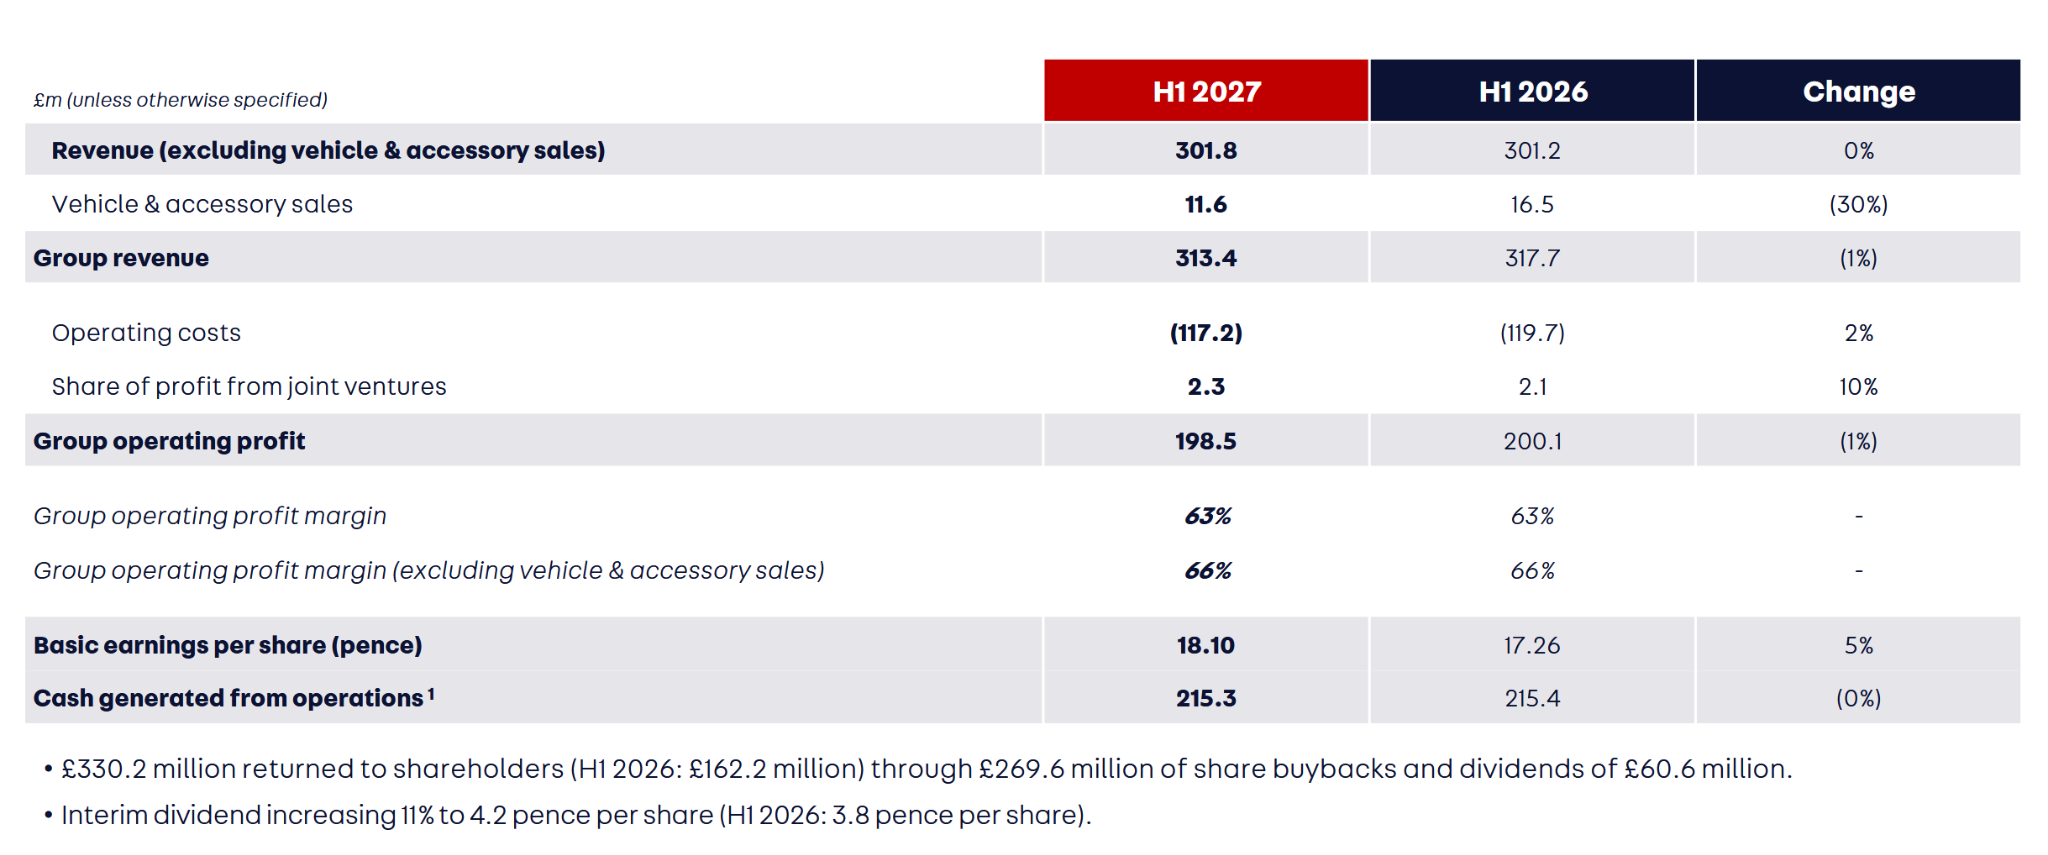
Revenues slightly declined, margins stayed constant but EPS went up due to massive buy backs. In their outlook they mention that they expect revenue growth in the second half of their financial year.

On the plus side, they report that they bought back a lot of stock at a decent price:

“During the period, a total of 55.7 million shares (H1 2026: 12.6 million) were purchased for a consideration of £269.6m (H1 2026: £100.2m) before transaction costs of £1.3m (H1 2026: £0.5m). The average price per share was 483.4p “

With a NTM P/E of 13,6x, Auto Trader is still cheap but of course without any visible growth, the upside is also limited. If they can actually return to growth in the second half, then this could get more interesting.

Rightmove

Rightmove issued a Trading update last week. The good news is that revenues have been growing at 7%, however operating profit was lagging revenue growth:
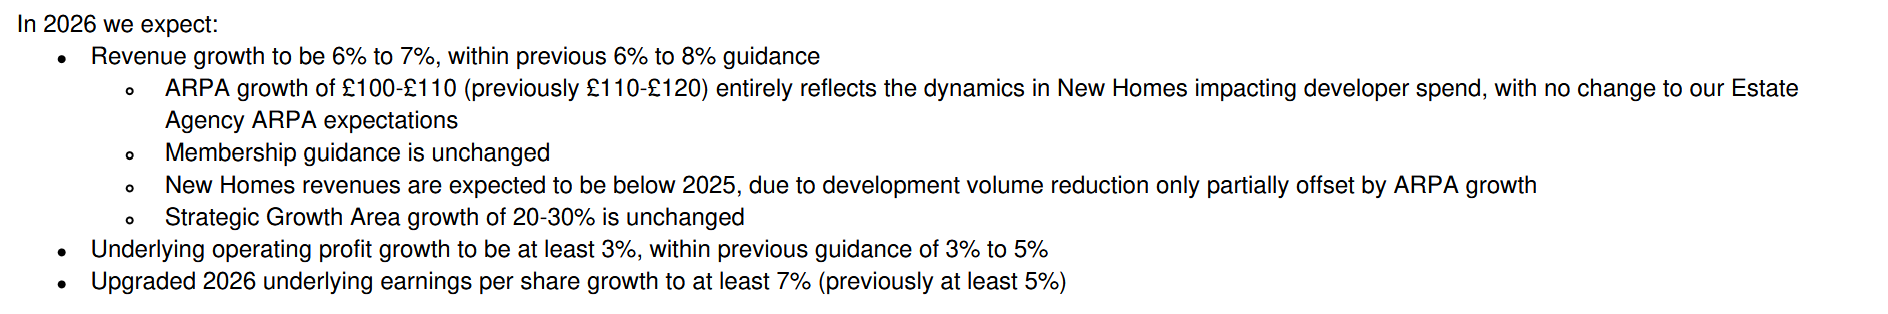
In 2027, they see similar revenue growth as in 2027 and improving operating results:

For 2027, reflecting the challenging and uncertain macro backdrop, we currently expect:

Revenue growth similar to 2026 as the current end-market dynamics are expected to continue into next year. This reflects the full-year impact of fewer New Homes developments and a subdued Estate Agency market. We expect: ARPA growth of £100-£110 Broadly flat Core membership Strategic Growth Areas growth of 20-30%

An increase in underlying operating profit growth to 4-7%. This will be driven by product launches, productivity gains and cost discipline alongside ongoing investment in

the initiatives announced in November 2025, with a margin of at least 67%

Underlying earnings per share growth of at least 10%

Considering the overall environment in the UK, this was a pretty decent trading update for Rightmove. As a (still) growing company, the slightly higher valuation compared to Auto Trader seems justified.

A few quick Q3 updates – EVS, Eurokai, Amadeus Fire, DCC, ATD & ABO Energy

Readers know that I am a very slow investor, nevertheless some noteworthy news from the porfolio for Q3 in no particular order;

EVS Broadcast

Just a few days ago, EVS held their investor day, the presentation can be found here. Business performance has been very good, they predict now that they will reach the upper end of the revised target. They also announced a (small) share buy back program. ZThe investor presentation contains a lot of interesting information, especially about the competitive landscape and how they want to gain market share. Overall I think they are executing extremely well and management eem to have a clear gorwth path ahead of them. As this is a European small cap, the stock of course did exactly nothing. According to TIKR analysts expect 3,03 EUR EPS for 2024 but only 2,56 for 2025. Yes, 2025 is not an event year but I think that analysts might be too negative. I have been buying and it is now very close to a full position.

Read more

Wirecard – the “German Enron” & a very personal history 2008-2020

For those who just came back from a 15 year space mission: Wirecard is a German  company that according to its website is ” one of the world’s fastest-growing digital platforms for financial commerce”. It managed (briefly) to achieve a market cap of close to 25 bn EUR and is part of the German Blue Chip index DAX 30. The stock lost -62,71% today which is most likely a record for a DAX company for a single day.

Backstory / Personal history 2008

This is an article I wanted to write for a long time but I was actually afraid to do so for several reasons.

Wirecard is a company/stock that I have been following for a very long time. My first “encounter” with the company ended in a kind of “5 minutes of fame” situation with some very unpleasant side effects.

The story starts in May 2008 when a post appeared under the pseudonym memyselfandi007 on Wallstreet Online, the largest German stock community/forum. (fun fact: This Thread seems to have been read 17,8 million times, so a lot more than all my blog posts on V&O combined….).

Read more

Short cuts: Installux, Kuka, Aixtron

Installux:

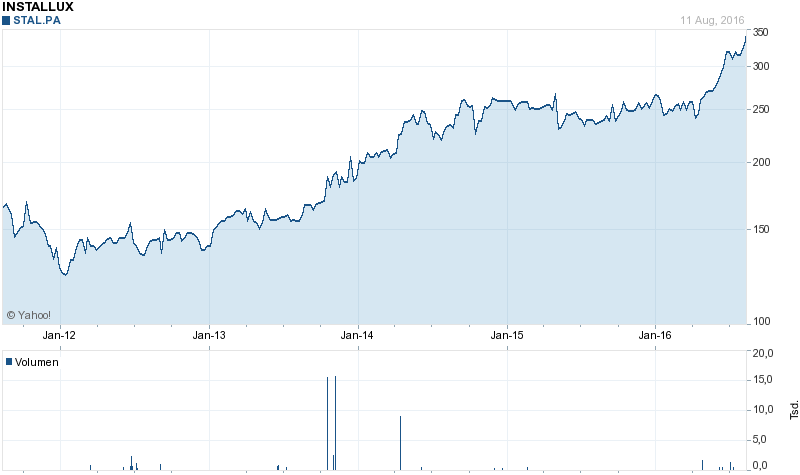
Installux is surprisingly one of my best performing stocks this year, including dividends the stock is more than 30% and is at an all time high.

installux

I did not fully understand why until I read the 6 month report.

Sales are up ~7% yoy, 6M earnings per share are 17,16 EUR vs. 14,37 EUR, an increase of almost 20%. Profit improvements happened across most of their sectors, so it doesn’t look like single special effects or so. Despite the recent run-up, the stock remains exceptionally cheap.

Kuka & MDAX exit

For those who did follow my comments on the original Kuka post, they might have noticed that I sold the stocks 2 days ago and bought them back yesterday slightly cheaper.

The reason was that in the meantime, the tendered shares were kicked out of the MDAX, the popular German MID Cap index.

As I was not sure how the shares would react I decided to manage the risk by staying out.

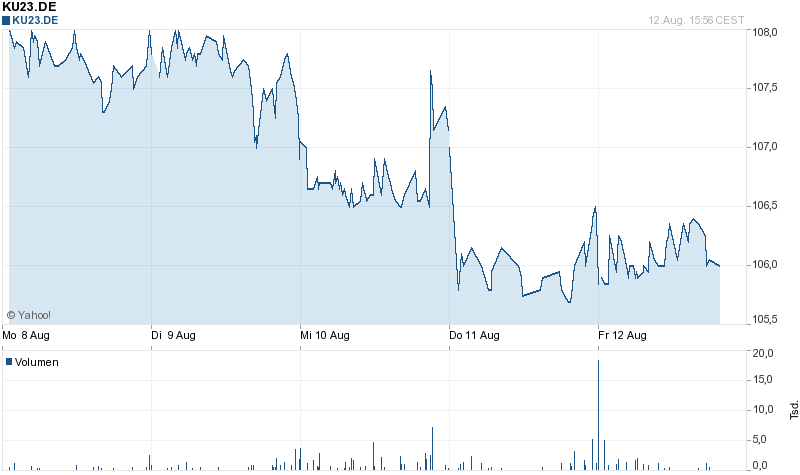
At the end of the day not much happened:

mdax kuka

Nevertheless I was able to cheapen my purchase price from ~107,5 to 106 EUR. As the deal now is more attractive, I invested a total of 4% of the portfolio.


Aixtron – another special situation (with a Chinese buyer)

Aixtron, a former TECDAX star has fallen on hard times. However a few weeks ago, a Chinese buyer showed up and finally made an offer for the company at 6 EUR per share.

With a share price at currently 5,53 EUR, the discount is similar to Kuka at around 8,5%.

The situation differs slightly from Kuka:

  • the buyer is a financial buyer, not a strategic one (more opportunistic ?)
  • The purchase price is “optically” not as rich as the one for Kuka (below book)
  • they require at least 60% acceptance as closing condition (vs. 30% for Kuka)
  • within the offer they have a “put” if the index (DAX or TEcDax) goes down more than 30%

On the plus side, there is little risk that anyone complains about the deal as Aixtron was not doing well anyway and they are not deemed “strategically important”. The time horizon here should be shorter than for the Kuka deal.

The offer runs until October 7th. So far, the acceptance is low, as of today, only 1,64% of the shares have been tendered.

I think the risk is slightly higher than in the Kuka case as they might not reach their threshold, on the other hand there might be a chance for a better offer.

Although the situation is less clear for me as in the Kuka case, I start here with a 1% position at 5,53 EUR and will monitor it closely.


Short cuts: Kuka, Swatch & Silver Chef

Kuka:

This is something that ran over the ticker today with regard to the Kuka case:

CFIUS Likely to Challenge Midea-Kuka Deal, Height Says

By Kasia Klimasinska

(Bloomberg) — CFIUS will likely challenge this deal “because Kuka has a direct relationship as a primary robotics supplier to Northrop Grumman,” Height analyst Nils Tracy says.

  • “At a minimum, we expect the transaction will face an extended CFIUS review timeline and a number of divestures”

Read more

Greenlight Re (sell), Handelsbanken (buy) & Bill Ackman

Greenlight Re

Following the E.On discussion, I really asked myself if it was such a good idea to invest into Greenlight Re.

My argument was as follows:

  • the stock looks historically cheap
  • Einhorn had a few very bad years
  • based on its track record hw might do much better in the future

After the E.On discussion however, I recognized the follwoing: Whenever I looked at a stock that Einhorn bought (Delta Lloyd, AerCap, SunEdison, Consol, E.on), I never understood why he did it or I thought it was not a good idea. Even if I look at his 20 bigest disclosed positions, I don’t find any stock that I would buy on my own:

     APPLE INC    AAPL  US
GENERAL MOTORS CO    GM  US
ISS A/S    ISS  DC
CHICAGO BRIDGE & IRON CO NV    CBI  US
TIME WARNER INC    TWX  US
MICHAEL KORS HOLDINGS LTD    KORS  US
AERCAP HOLDINGS NV    AER  US
CONSOL ENERGY INC    CNX  US
ARKEMA    AKE  FP
AECOM    ACM  US
ON SEMICONDUCTOR CORP    ON  US
BANK OF NEW YORK MELLON COR    BK  US
TAKE-TWO INTERACTIVE SOFTWR    TTWO  US
GREEN BRICK PARTNERS INC    GRBK  US
MICRON TECHNOLOGY INC    MU  US
MARKET VECTORS GOLD MINERS    GDX  US
VOYA FINANCIAL INC    VOYA  US
LIBERTY GLOBAL PLC-SERIES C    LBTYK  US
DILLARDS INC-CL A    DDS  US
APPLIED MATERIALS INC    AMAT  US

That in effect lead me to the conclusion that I am most likely the wrong kind of shareholder for Greenlight Re. If things go really  bad, I am not sure if I would have enough trust to keep the position or if I would get really nervous because I could not identify with the manager.

Secondly, I honestly don’t have much insight, how Einhorn generated his fantastic past track record.

Together with not liking his long position, I think it was a mistake to invest in Greenlight and I sold my stocks as mentioned in the comments at around 18,45 USD per share with a tiny profit of around +2,5%.

It could well be that Greenlight maybe has a spectacular 2016 but as I have mentioned above, one should not allocate money to someone where you don’t understand what that manager is doing. Conviction is important to withstand all kind of behavioural traps in investing.

Finally, I am not sure if there could be some isues on the Reinsurance side. AIG surpisingly disclosed a pretty massive reserve strengtening for Q4 and it looks like that this is mostly “long tail” exposure from long ago which is also the “bread and butter” business of Greenlight Re.

Handelsbanken

Following the market turmoil, I began to establish a first (2%) position in Handelsbanken. Purchase price was on average ~98 SEK per share. Valuation wise they are now at a level where I would expect to earn around 16-17% p.a. long term which looks atractive to me despite potential short term head winds.

I plan to increase this to a full position over the next months. I funded this position by selling some of the HT1 bonds, as I want to keep some cash (~10%) in order to be flexible if some of my watch list shares become really cheap.

Bill Ackman

Bill Ackman came out with his Q4 letter to investors just a few days ago. His results were similarily bad than Einhorn’s with -20,5% after fees for 2015.

There was already good coverage on his letter for instance from Matt Levine.

My 2 cents on this:

  • compared to Einhorn, he mostly blames others for his losses (index funds, copycats, the market)
  • he doesn’t seem to fully understand how index funds work
  • funnily enough, he accuses index funds that their only goal is to “attract more funds” at low costs. Why did Ackman then create the public vehicle Pershing Square Holdings ? Well, he also wants to attract more fund but a high costs.
  • he thinks that there are not enough activists. Understandable from an activist perspective. Subjectively I have the feeling that Carl Icahn alone is activist at every single stock in the US.
  • at least he admits that “platform” companies like Valeant are not such fantastic cases per se.

On a personal level, I do think there might be already TOO MANY activists. Many of them only care for short term payouts which, in many cases, might not be benefitial for long term share holders.

All in all, if I would have money invested with Ackman, I would really ask myself if I would trust a guy who only blames others for his misfortunes.


« Older Entries