Update Special Situations: Norma, Paypal & NEW: Delivery Hero (No action)
Norma Buyback Tender:
The original write-up is from mid-June and can be found here. Plus a same day update here.
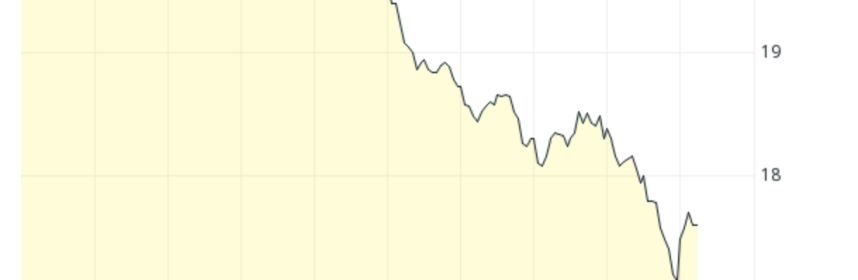
Looking at the share price development, I clearly got out too early from this one at around 18,85 EUR per share plus dividend:
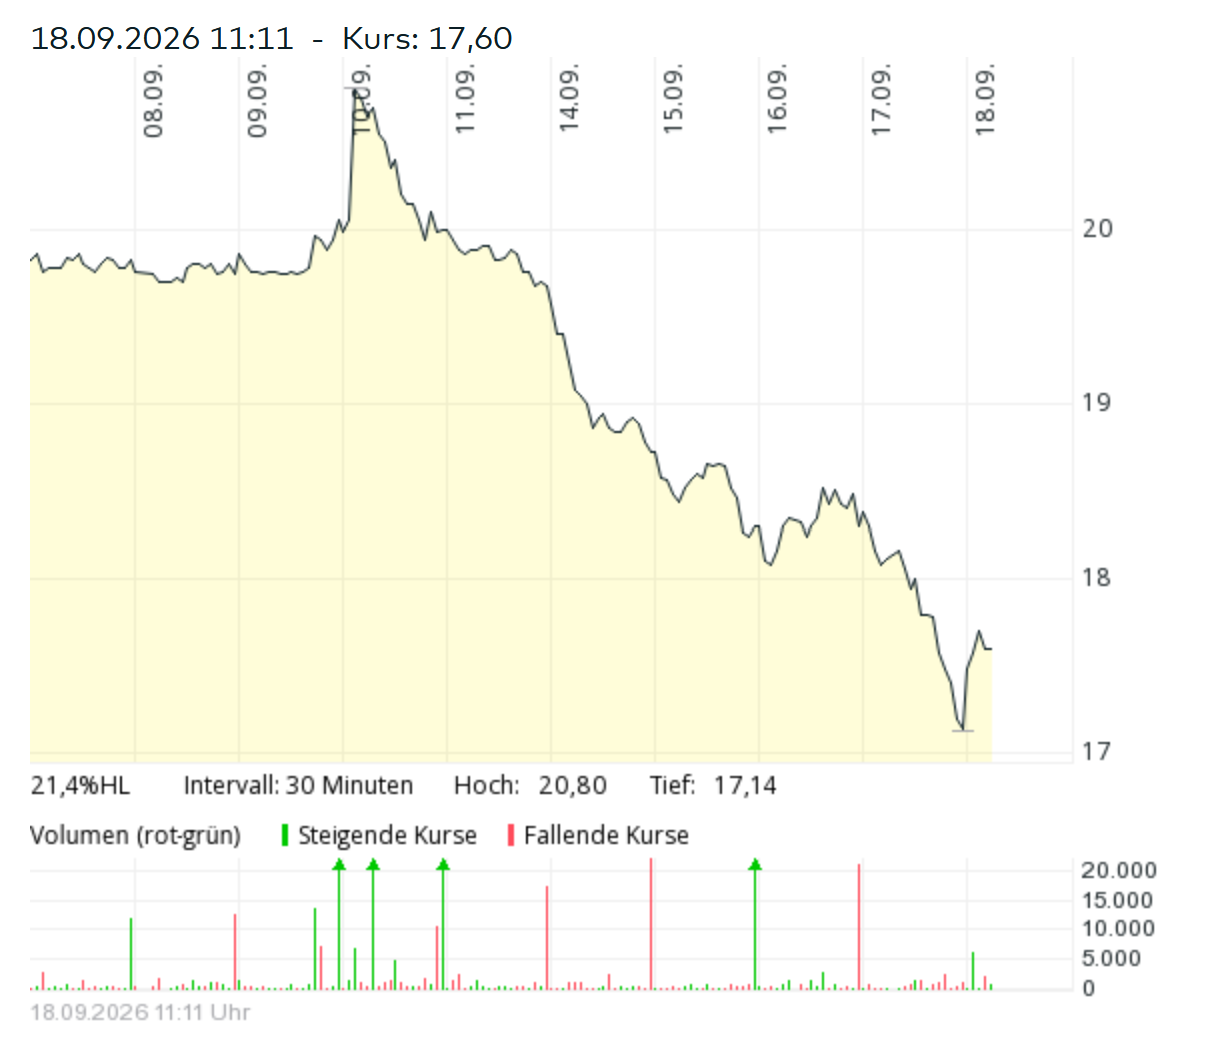
Overall, I was clearly lucky with the timing of the entry. I closed the trade early because first, I could lock in my expected return and secondly, I was a little bit “off grid” and had limited ability to react during the trading period of the tender rights.
The main difference to my initial case was that the tender price had been further increased from 20,87 EUR to 22,35. Interestingly, for the remaining shareholders, this is not really positive as more cash went to selling shareholders.
I had checked a few times during the trading of the tender rights and they were trading relatively close to their intrinsic value.
What I find quite surprising is that at the time of writing, the stock is still trading pretty high above my “undisturbed” value before the announcement. And how long it took to come down from the “inflated” tender price. I have to confess that I don’t fully understand this.
Paypal Stripe/Advent offer Special Sit:
Here clearly my expectation of a higher bid from Stripe/Advent did not materialize but they rather dropped their effort.
As mentioned in the comments of the original post, I directly sold after this became public as I have no opinion on the longer term development of Paypal. This is what I wrote back then:
However one more thing is important to mention: This is a special situation investment for me. So if for some reason, Stripe & Advent withdraw their bid, I will sell, no matter what. For a “Value investment” I still find Paypal too hard at this stage.
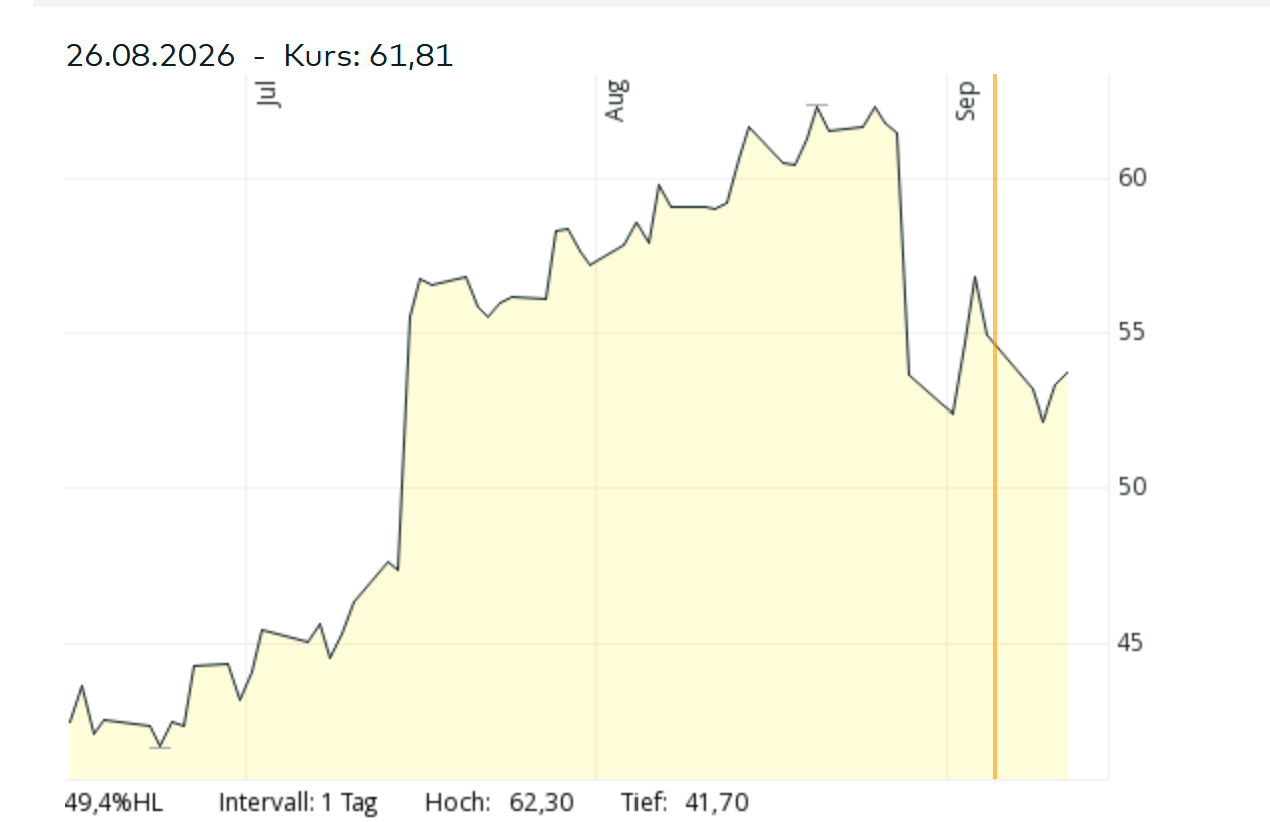
Luckily for me, the stock did not drop down to the “undisturbed” price of ~45 USD. So I could get out with a relatively modest single digit loss in this case.
I have to admit that I was already feeling a little bit insecure after Stripe closed the OpenRouter acquisition for ~7,5 bn USD a few days earlier. Stripe is a great company but they don’t seem have an unlimited budget for M&A as a financial intermediary.
As in all of these cases, there is always the risk that a case doesn’t work out. In my opinion, the most important part here is to stick to the original plan (i.e. sell) and try to find out if I have made any “a priori mistakes”.
In this case, the only mistake was maybe not to reduce the position after the open router acquisition from Stripe.
For the future, any public take-over situations with Stripe need to trade at a wider discount to account for this episode.
Delivery Hero/Uber take over Special Sit
As mentioned in my weekly links post, the UBER/ Delivery Hero take over could be an interesting Merger “Arbitrage” Special Situation.
In a nutshell, Uber owns currently around 25% of DHR outright and has launched a take-over offer in late August at an offer price of 41,5 EUR.
Expected closing of the deal is in the second half of 2027 and the acceptance hurdle for this offer is only 51% which Uber seems to have in the bag already.
The main risk of the transaction is clearly a relatively complicated merger control and approval process in many countries and especially an intermediate step where part of DHER’s business needs to get carved out and sold to a Private Equity shop called SSW Partners.
At the current share price of 36,85 EUR/share, the “spread” to the 41,50 EUR offer is 12,6%.
This needs to compensate for:
- a relative long time horizon (long stop November 2027)
- a relative high premium to the undisturbed price (+100%)
- and the aforementioned deal complexity
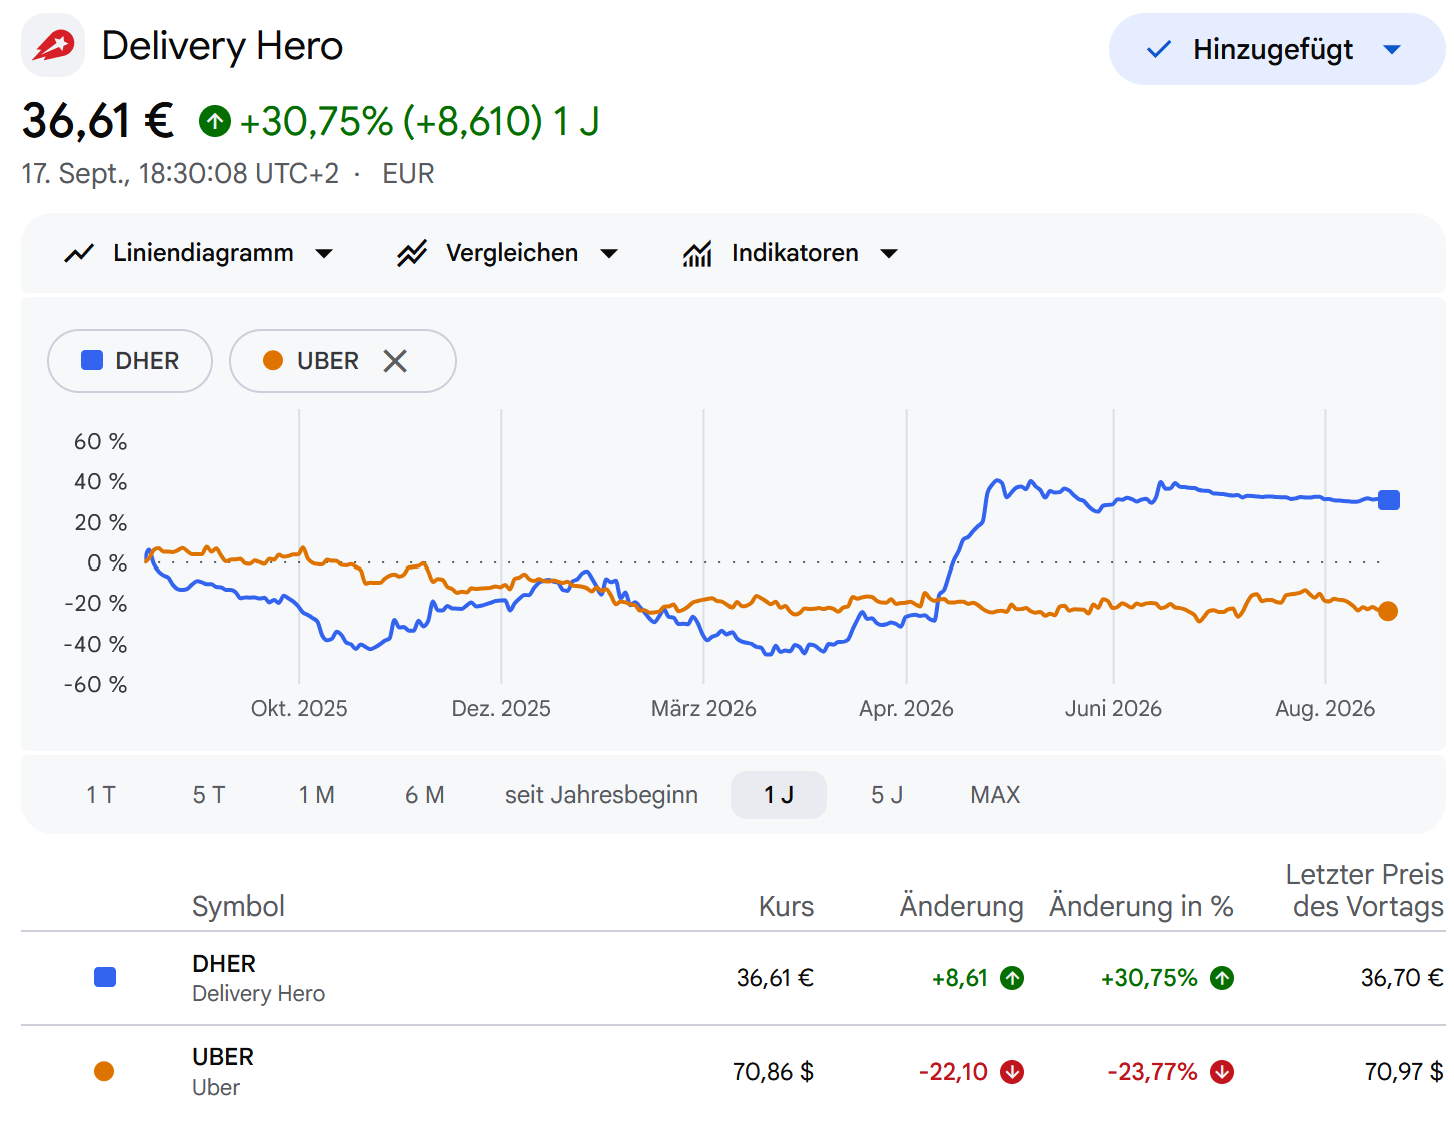
This is the stock chart from Delivery Hero which shows the significant bid premium:
All my 3 AI Tools (Claude, ChatGPT & Gemini) were recommending not to establish a position due the complexity of the deal (carve-out requirement) and the significant downside in a “no deal” scenario if the “cost of capital” is 10 to 15% p.a.
Personally, I think especially countries like UAE or Saudi Arabia could become more risky with regard to merger clearance when the war in Middle East continues to spread.
So in this case I actually follow the advice and sit on my hands. I will revisit this by end of October to see if it has become more attractive, either by a lower price or some fundamental improvements.
Interestingly, both ChatGPT and Claude offered to build an Excel spreadsheet. Here are some screenshots from ChatGPT which look very professional:
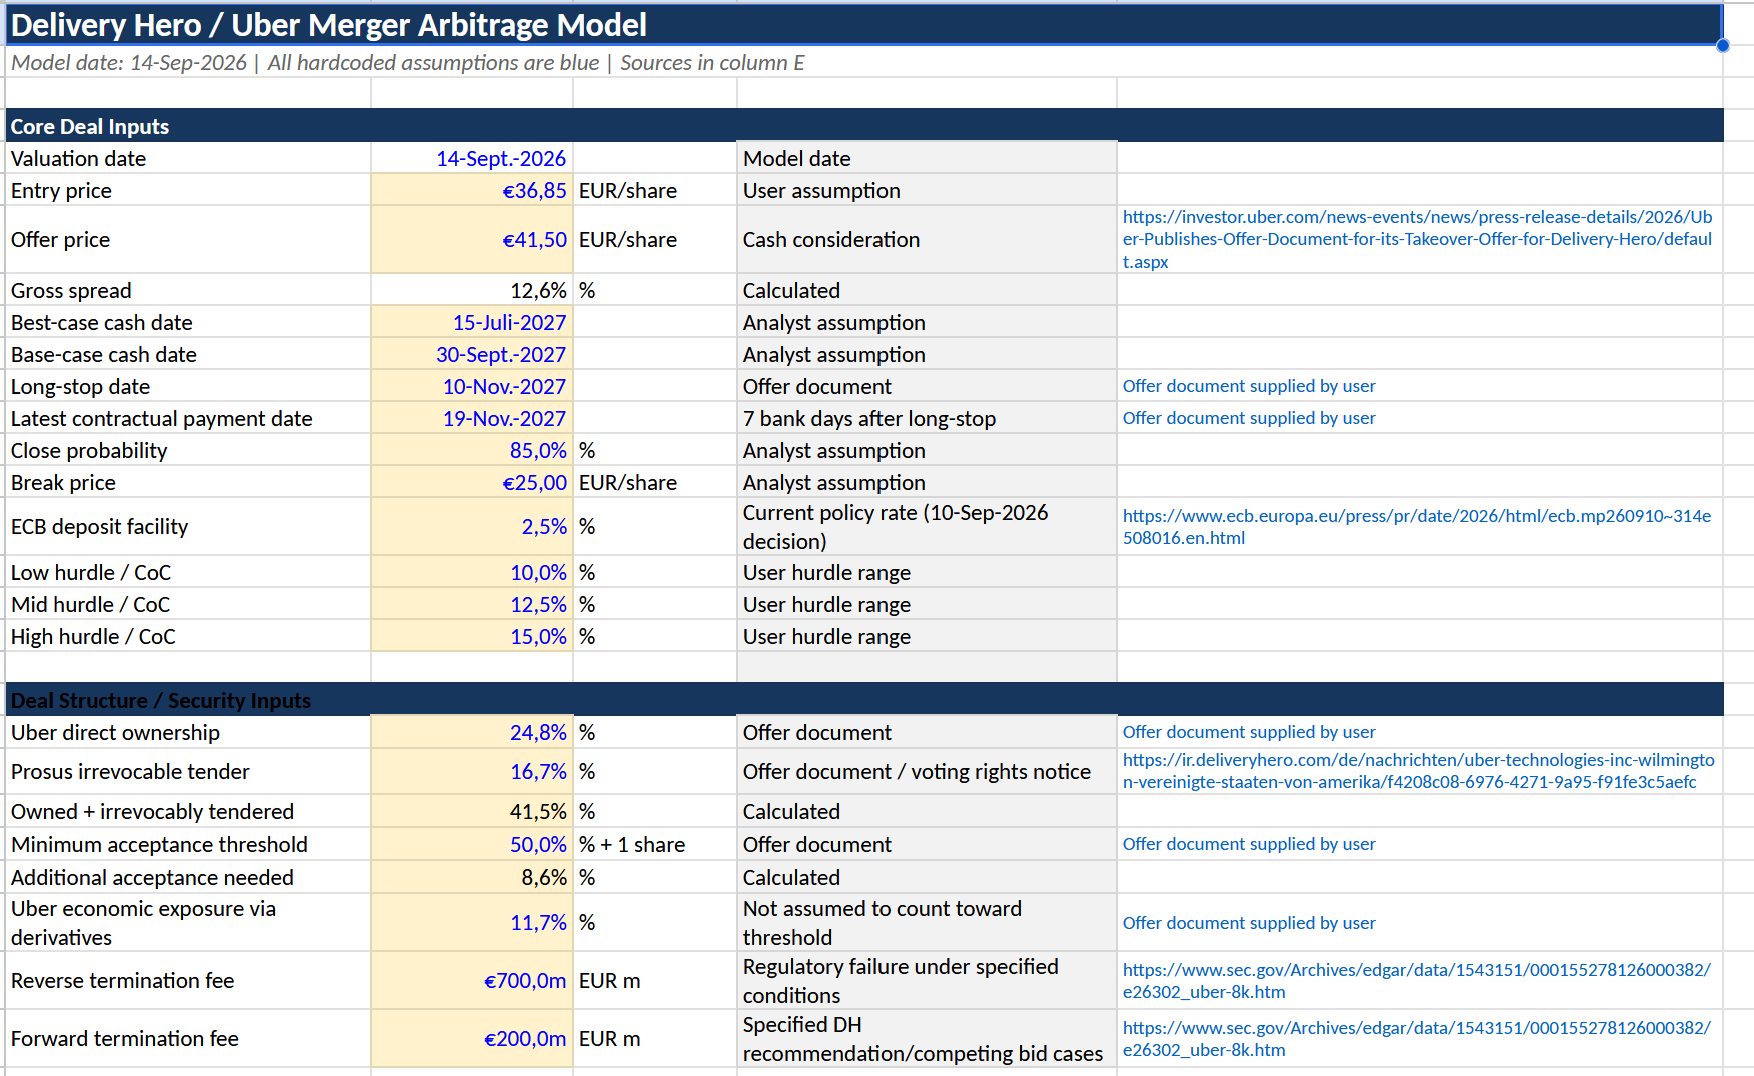
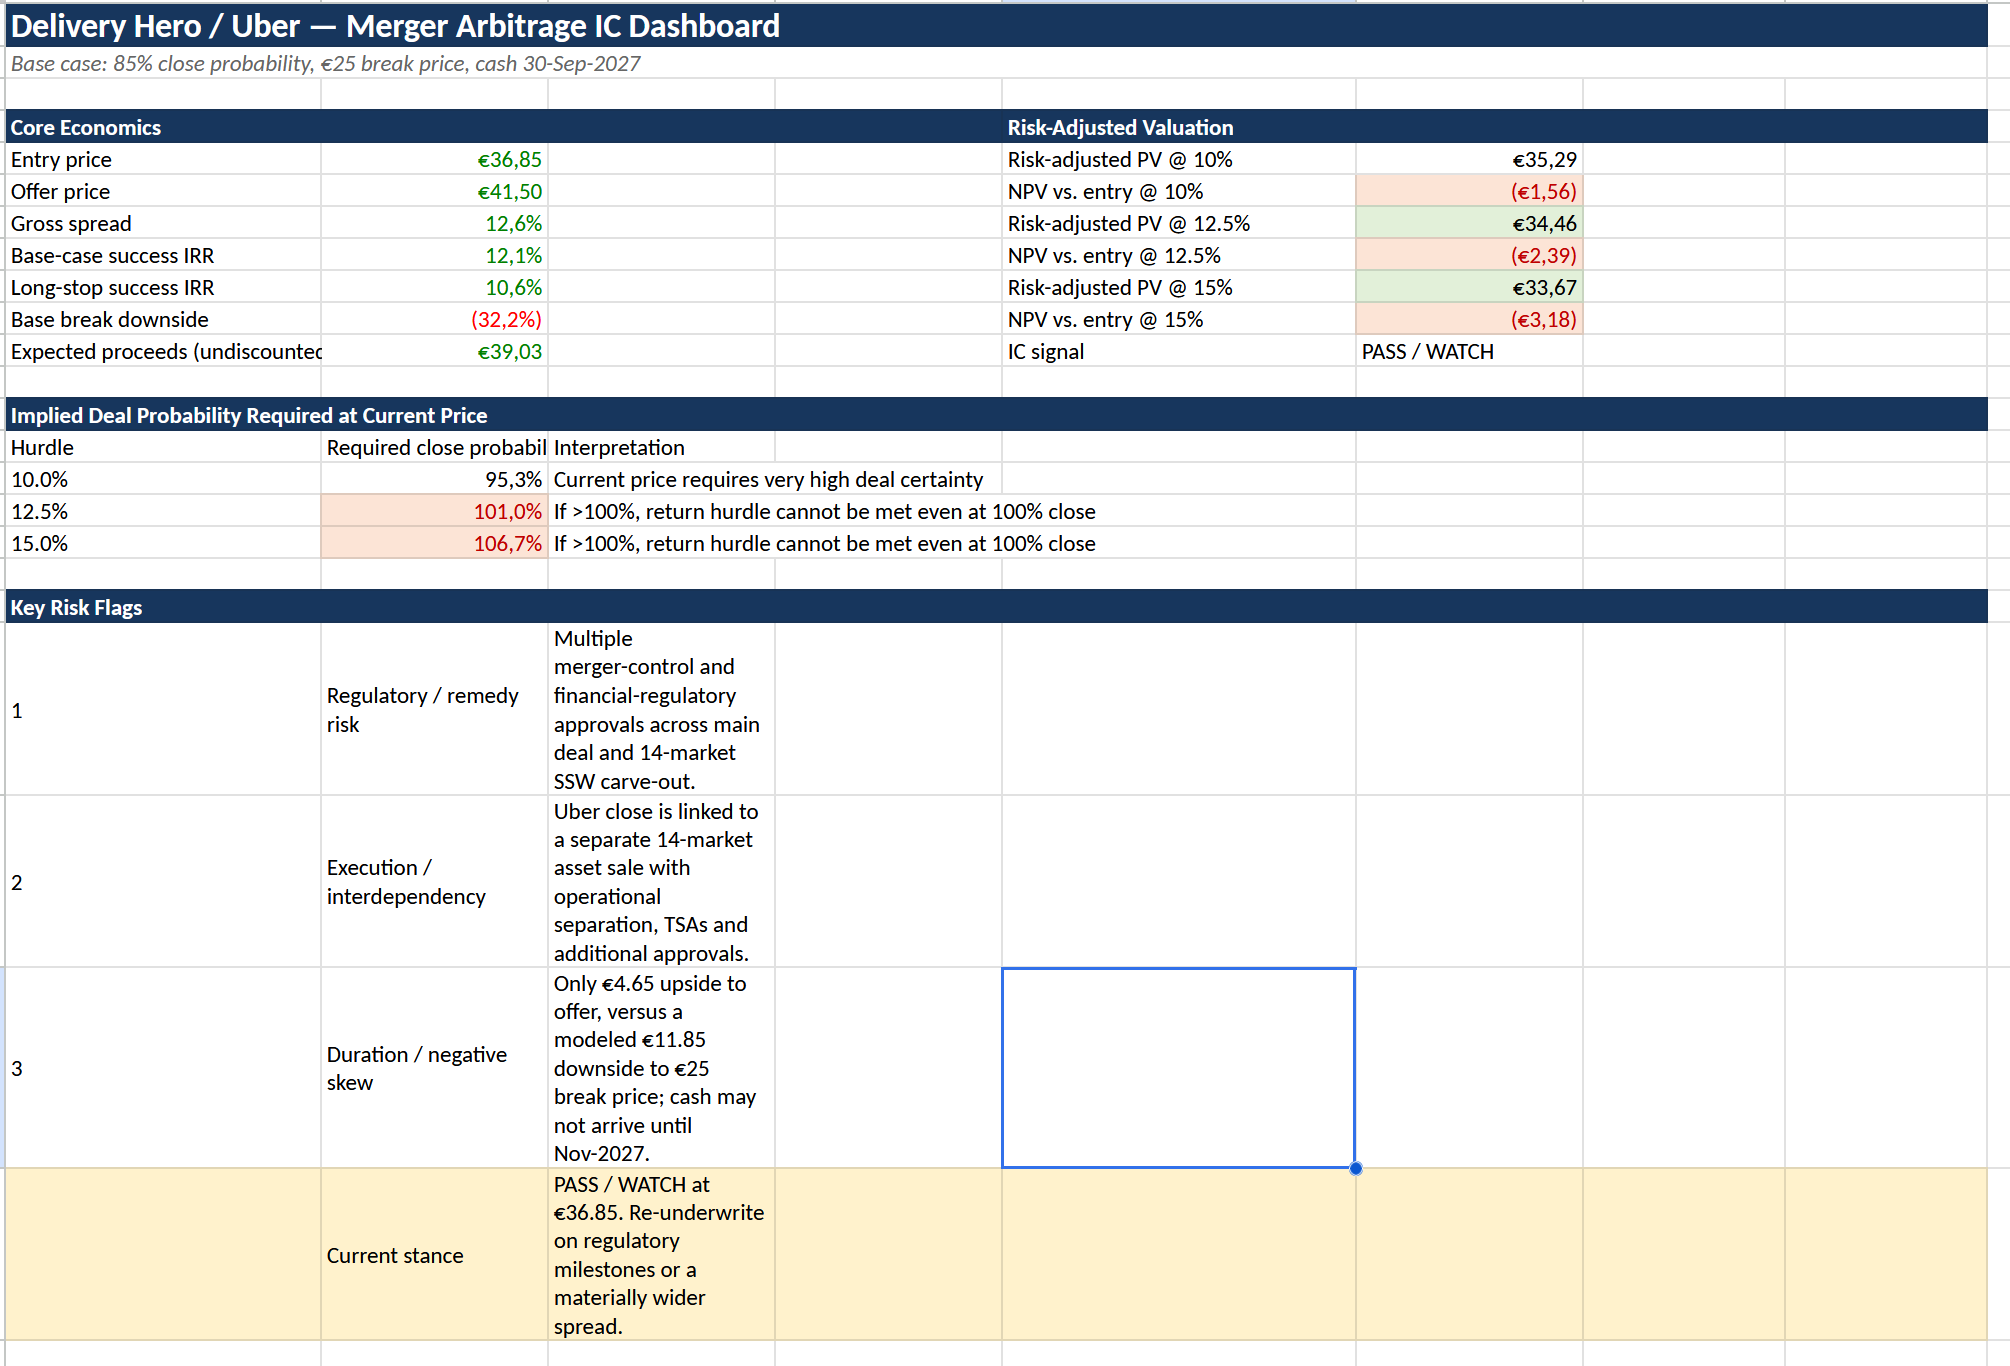
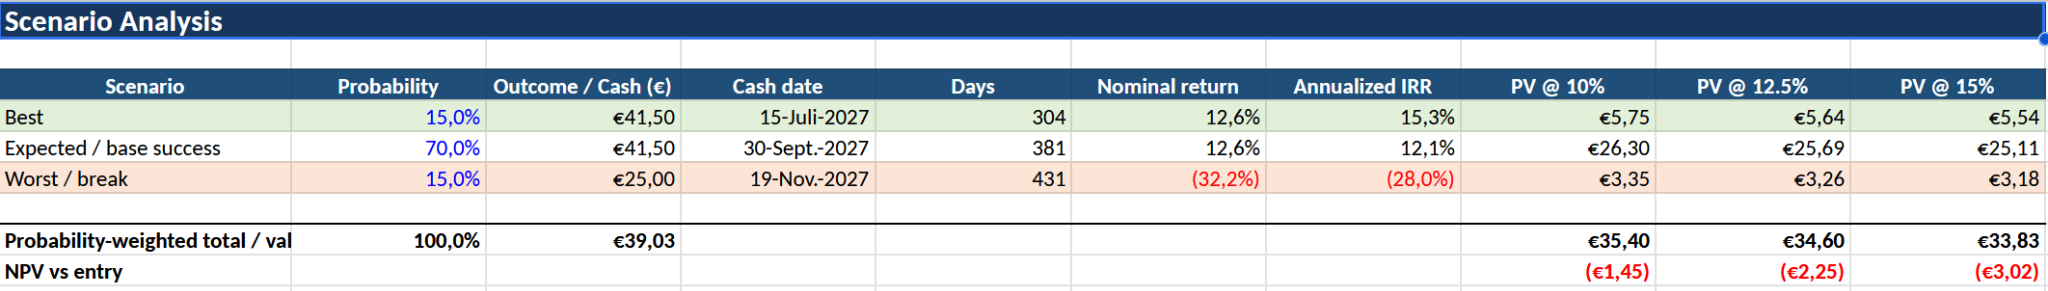
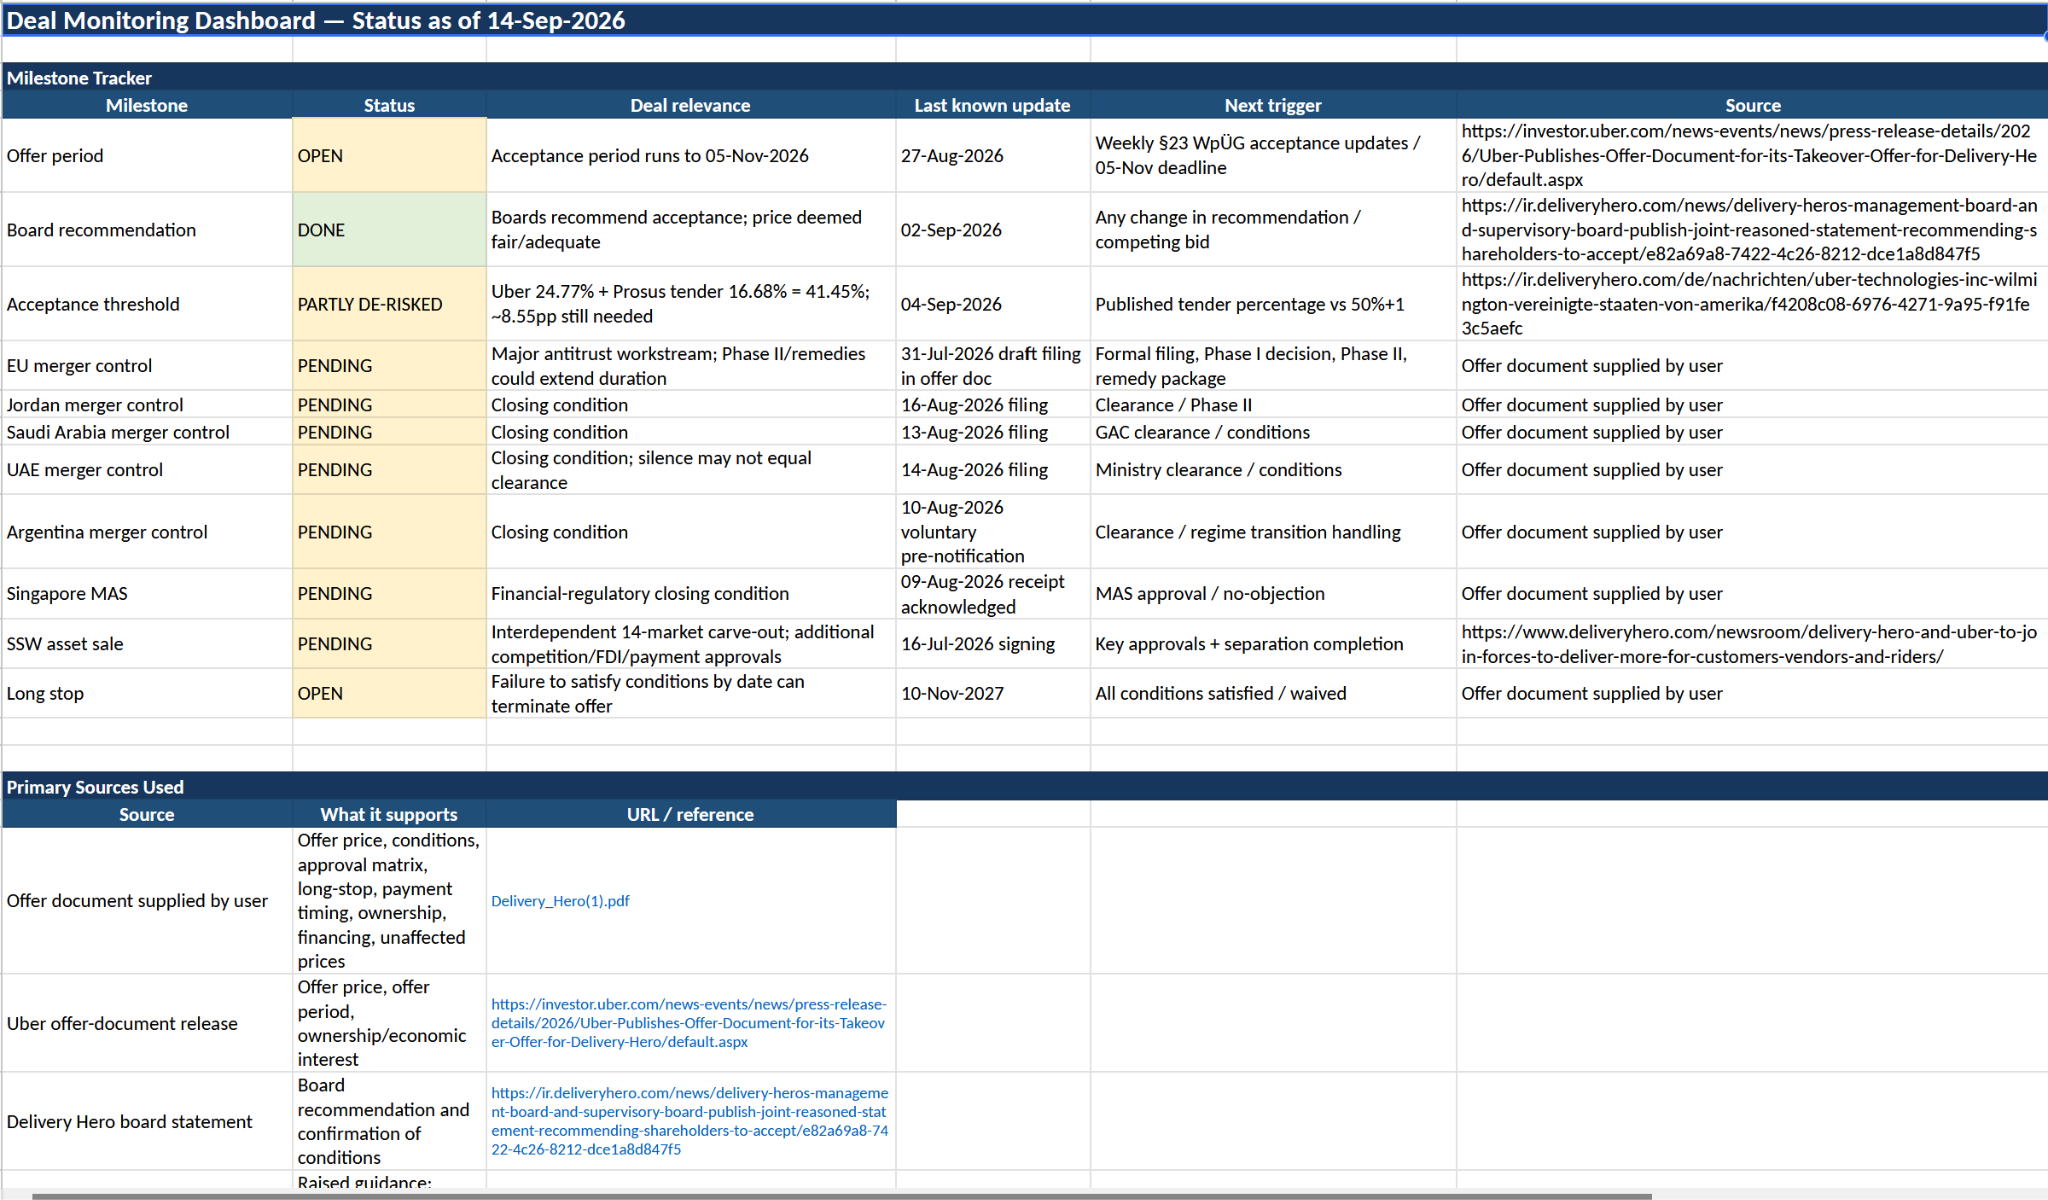
I didn’t check all the formulas, but it seems to be quite good.
In addition, ChatGPT also is checking now 2 times a day for updates.I guess Claude can do the same easily.
Although AI tools don’t change the Special Sit game completely, it clearly makes a more “equal playing field” as it reduces the effort to get into this.
The main risk that I see is that the motivation to actually read relevant documents goes down even more and that it is hard to see if the AI Agent makes mistakes or catches everything.
 value and opportunity
