Monthly Archives: October 2026

Rubis SCA: Interesting French listed Special Situation with a Corporate Restructuring catalyst
DISCLAIMER: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!

Management Summary:

Rubis, the French listed Fuel distribution company, represents a potentially interesting Special Situation investment, despite (or because of) the current negative sentiment towards French stocks.

On the back of strong earnings momentum (6M earnings +18%), Rubis has almost no exposure to France and has recently announced to undergo a structural transformation from a disadvantageous SCA structure (similar to a German KGaA) to an ordinary stock corporation.

For normal shareholders, this is hugely positive despite a planned compensation for the former controlling shareholders. In addition, this opens up M&A opportunities which had been rumoured about for some time.

The share price so far has not reacted, most likely because of the perceived problems in France which in my opinion creates an opportunity for the opportunistic investor. The time that will be required until a potential M&A transaction will occur, will be nicely compensated through a 6% dividend yield.

Rubis Background

Historically speaking, Rubis is a rather young company, having been founded only in 1990 by a gentlemen called Gilles Gobin and then grew rapidly through many acquisitions, often buying small subsidiaries of large international energy companies.

Rubis is  a company that I came across several times in the past. It has a very interesting mix of businesses and geographies, but due to corporate structure issues (SCA, more similar to a GP/LP structure than a normal stock corporation) I never considered investing.

Effectively, the heirs of the founder through a 2,3% share holding were controlling the board and on top of that was able to charge a significant royalty on Rubis’ profit (in 2025 this was approx. 30 mn or 10% of Rubis net profit). The formula seems to give them a percentage of the annual share price increase but capped at 10% of the net income.

At the time of writing, Rubis is valued at around 3,6 bn market cap and trades at a relatively modest ~10,7 x NTM P/E which is clearly impacted by this unusual arrangement:
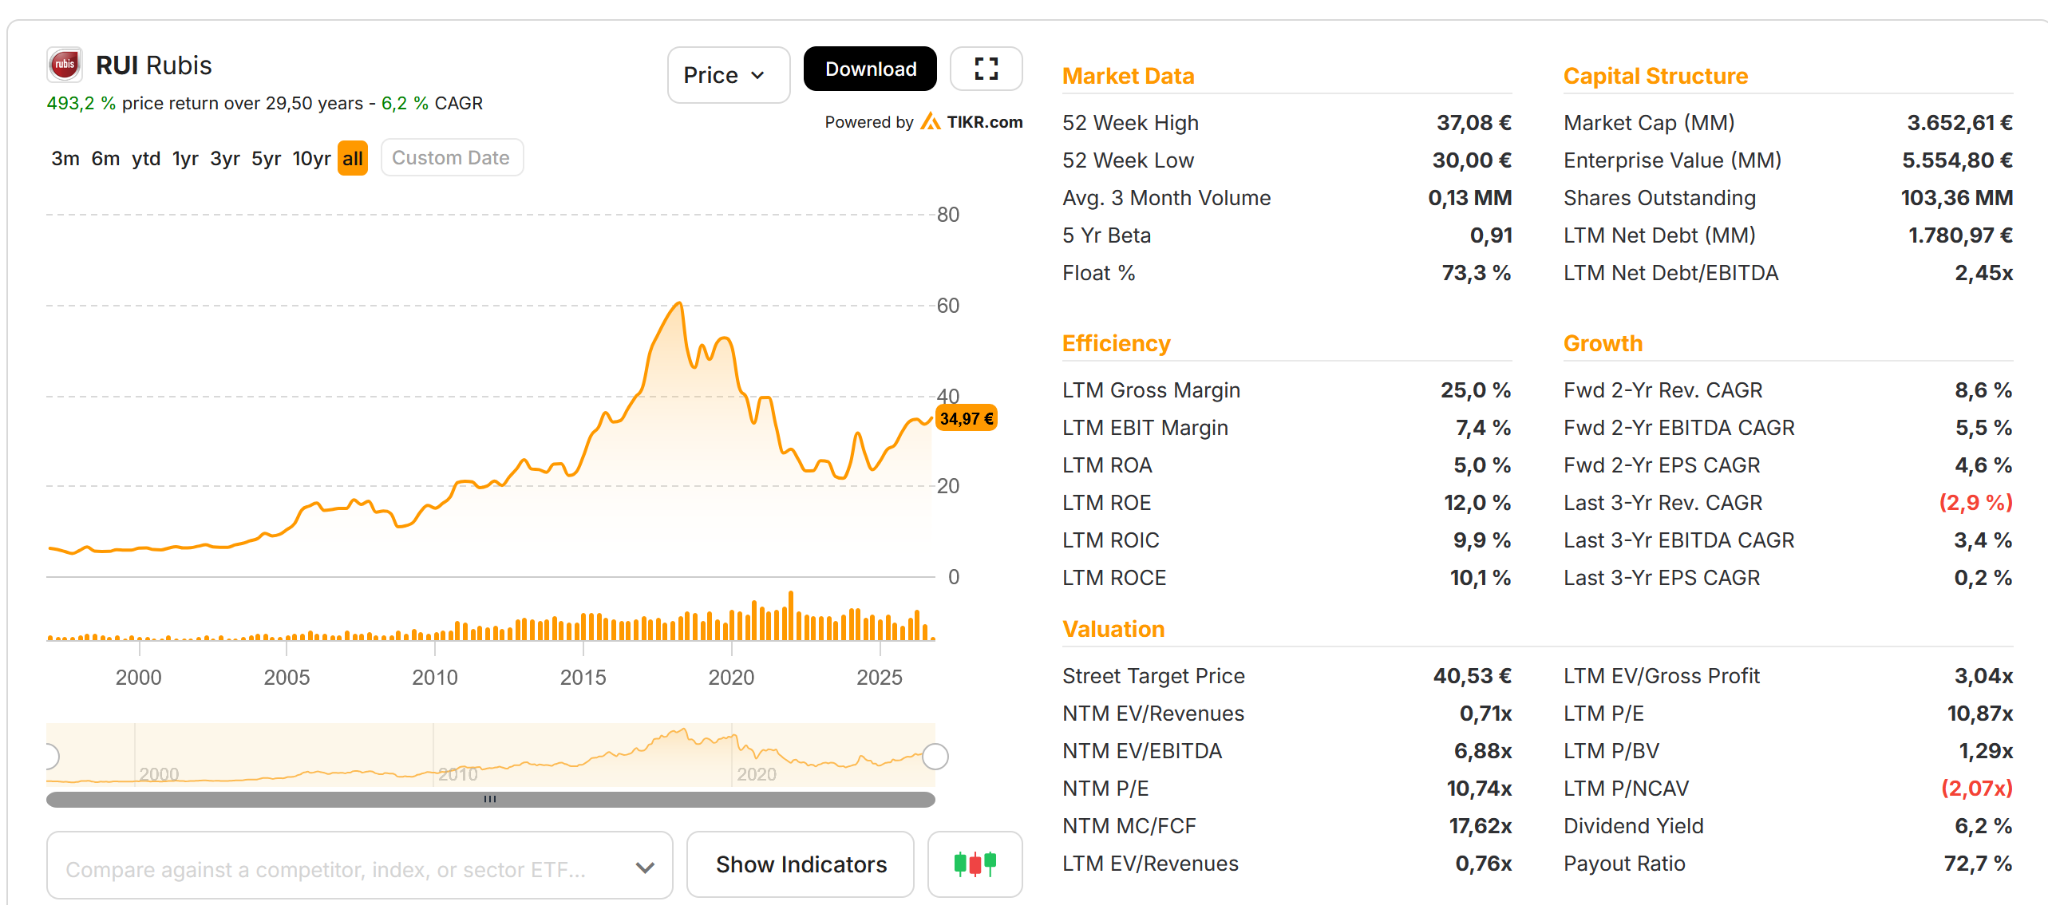
Looking at the long term chart, Rubis shareholders have done Ok including the dividend but the share price is significantly below the peak of around 60 EUR from 2018.

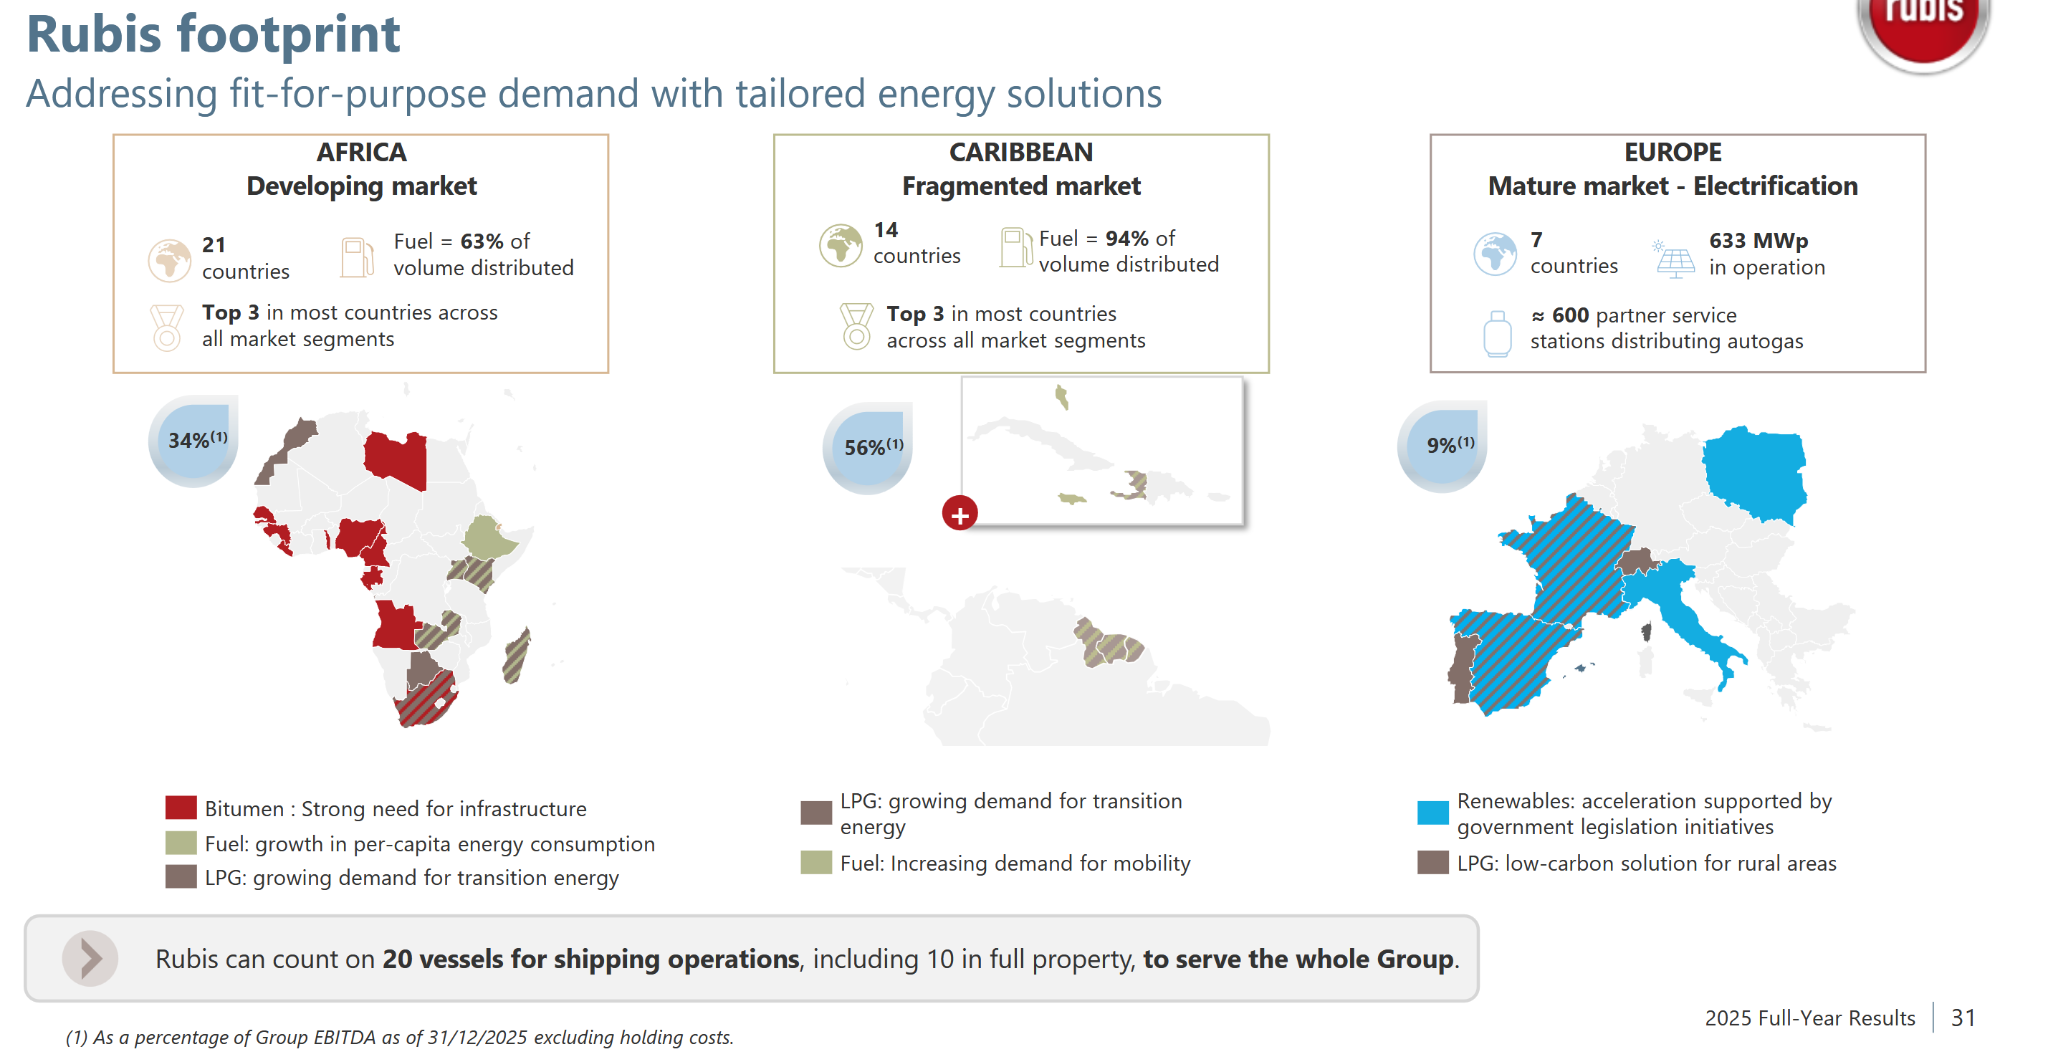
Rubis is French listed but has very little exposure to France

As there is “blood in the streets in Paris”, it is worth mentioning that Rubis sales have a pretty unique breakdown:

~50% of sales are in Africa

~40% in the Carribean

~0nly around 10% in Europe

The business as such is a mixture of fuel and LPG distribution, Renewable Energy and interestingly Bitumen distribution. Bitumen is a byproduct from refining oil and is used among others to create asphalt by mixing bitumen with sand and stones.

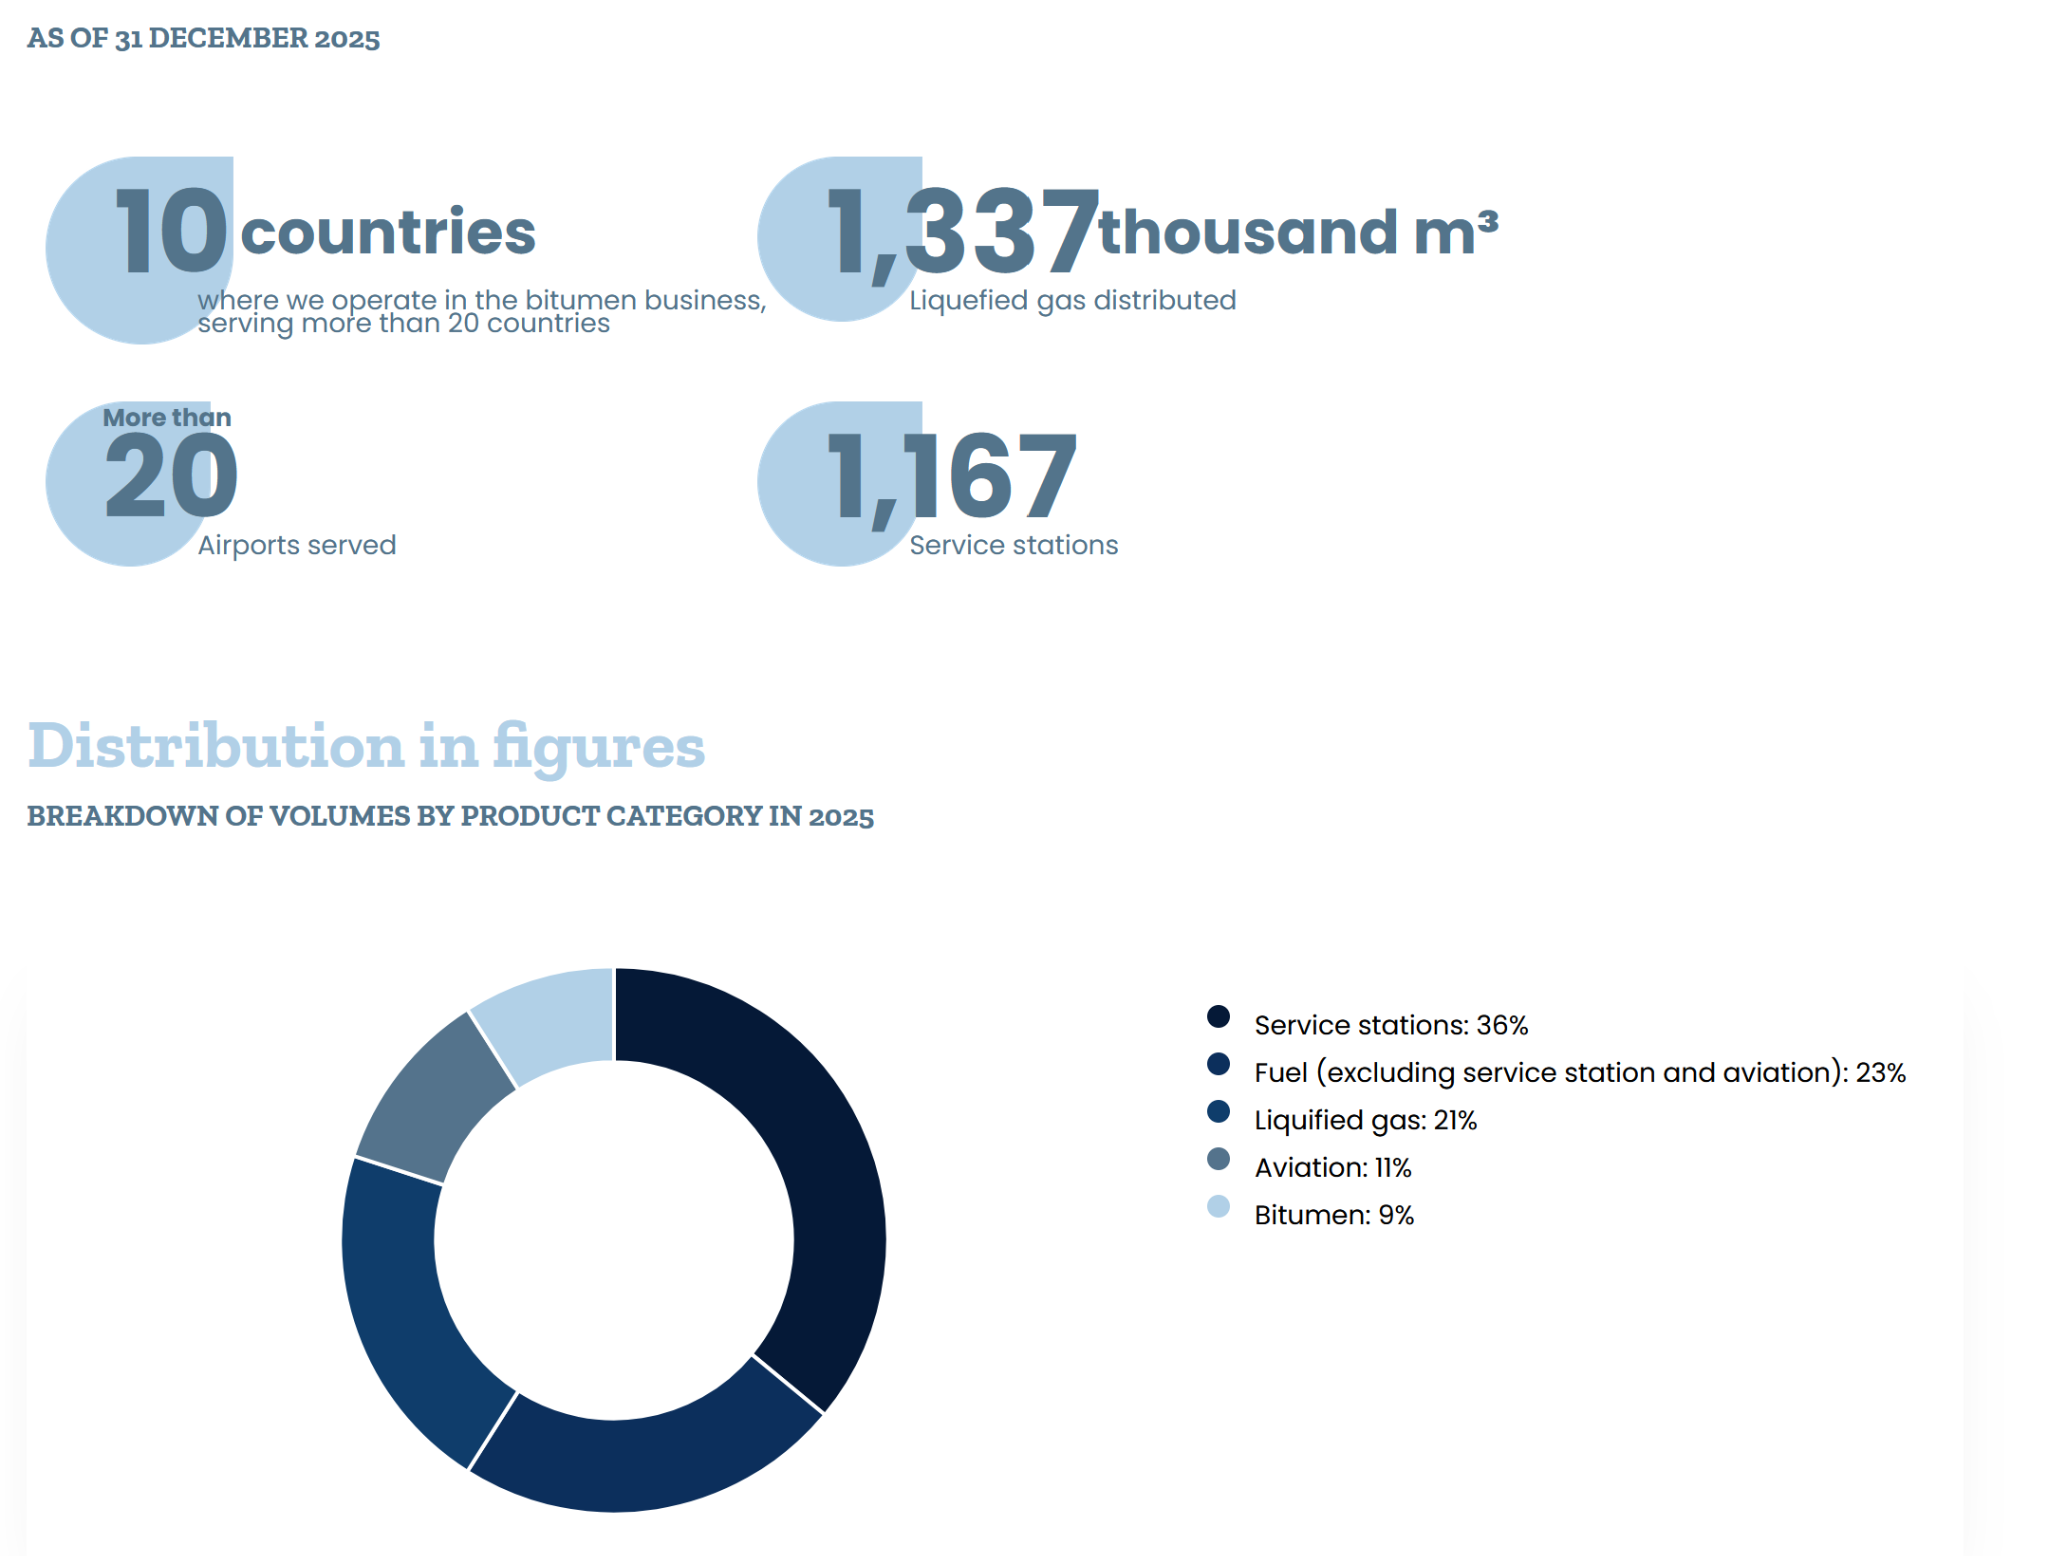
Rubis is the biggest Fuel distributor in Kenya which according to some sources is their biggest single market. This is a split of the fuel distribution business from their website:
This chart from the 2025 annual results nicely shows the extremely unique geographical  footprint of RUBIS:
The Renewables Energy business is a result of the 2022 acquisition of a French Renewables company called Photosol, which was widely criticized as too expensive.

Rubis also owned a terminal business, but sold that in 2024 to JV Partner and Infrastructure fund I Squared capital.

So in a nutshell, Rubis is not impacted much by the current situation in France.

Financing wise, they seem to have restructured their debt financing “just in time” in late 2025 with a syndicated loans facility that seems to have a 5 year term.

As the business is very cash generative, it looks like that they are also not affected by the recent widening of French spreads as they don’t have to issue debt for the next few years.

The catalyst: Corporate structure change

Now however, things seem to change and quite quickly: Rubis intends to become a “normal” company, most likely under the pressure of some prominent investors, such as the Bollore Group. My friend Graouilly has written about it here.

From a technical perspective, the former “GP” will receive an extra 12% of newly issued shares as compensation for giving up his special rights that included a royalty on Rubis’ net profit.

Rubis has scheduled an extraordinary shareholder meeting for December 9th where these changes including the capital increase shall be approved.

There seems to be some resistance among the larger shareholders that the compensation is too generous, but any lower compensation amount will be a positive for shareholders.

Share price:

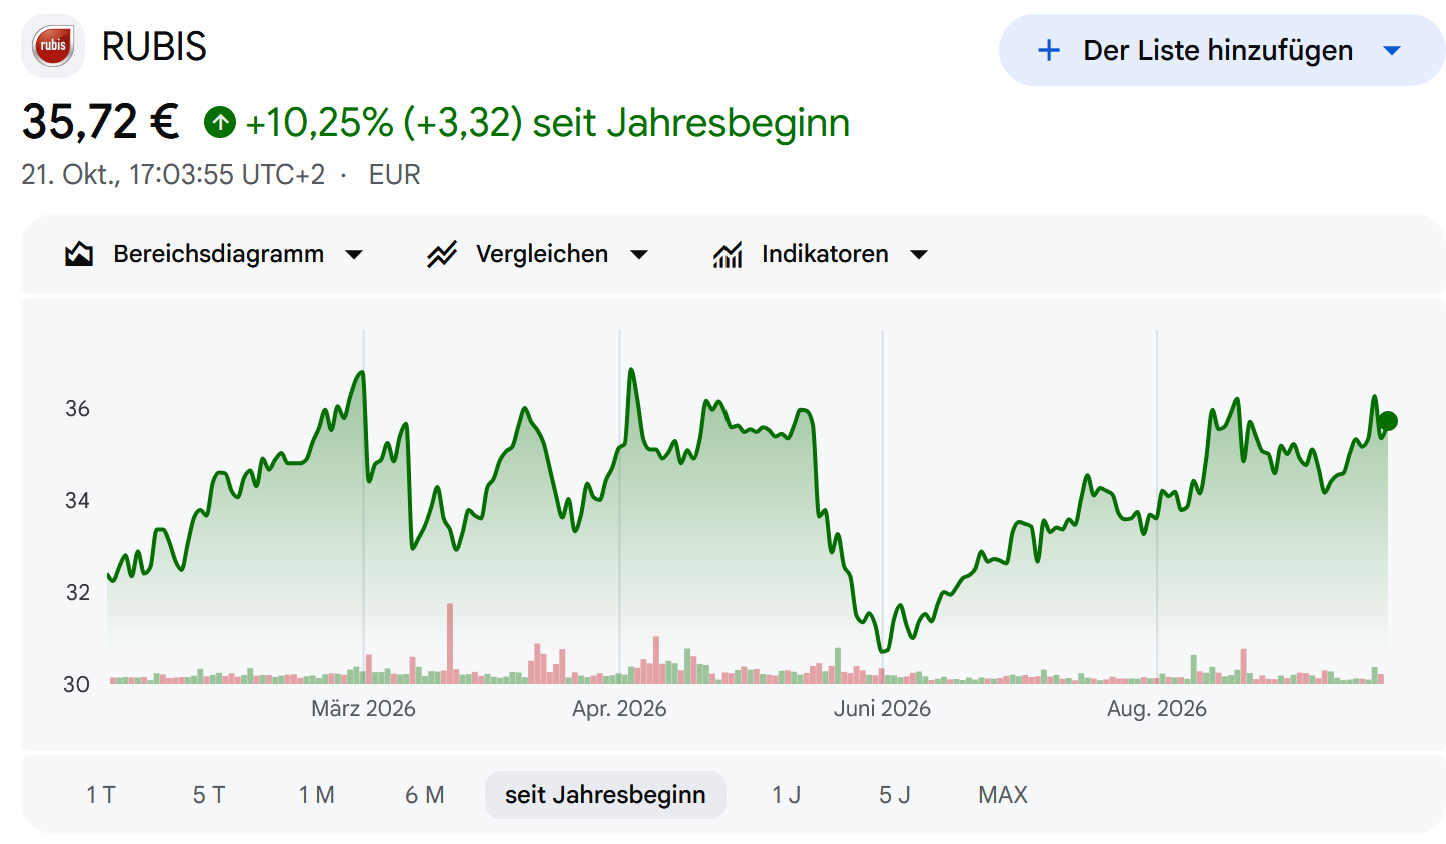
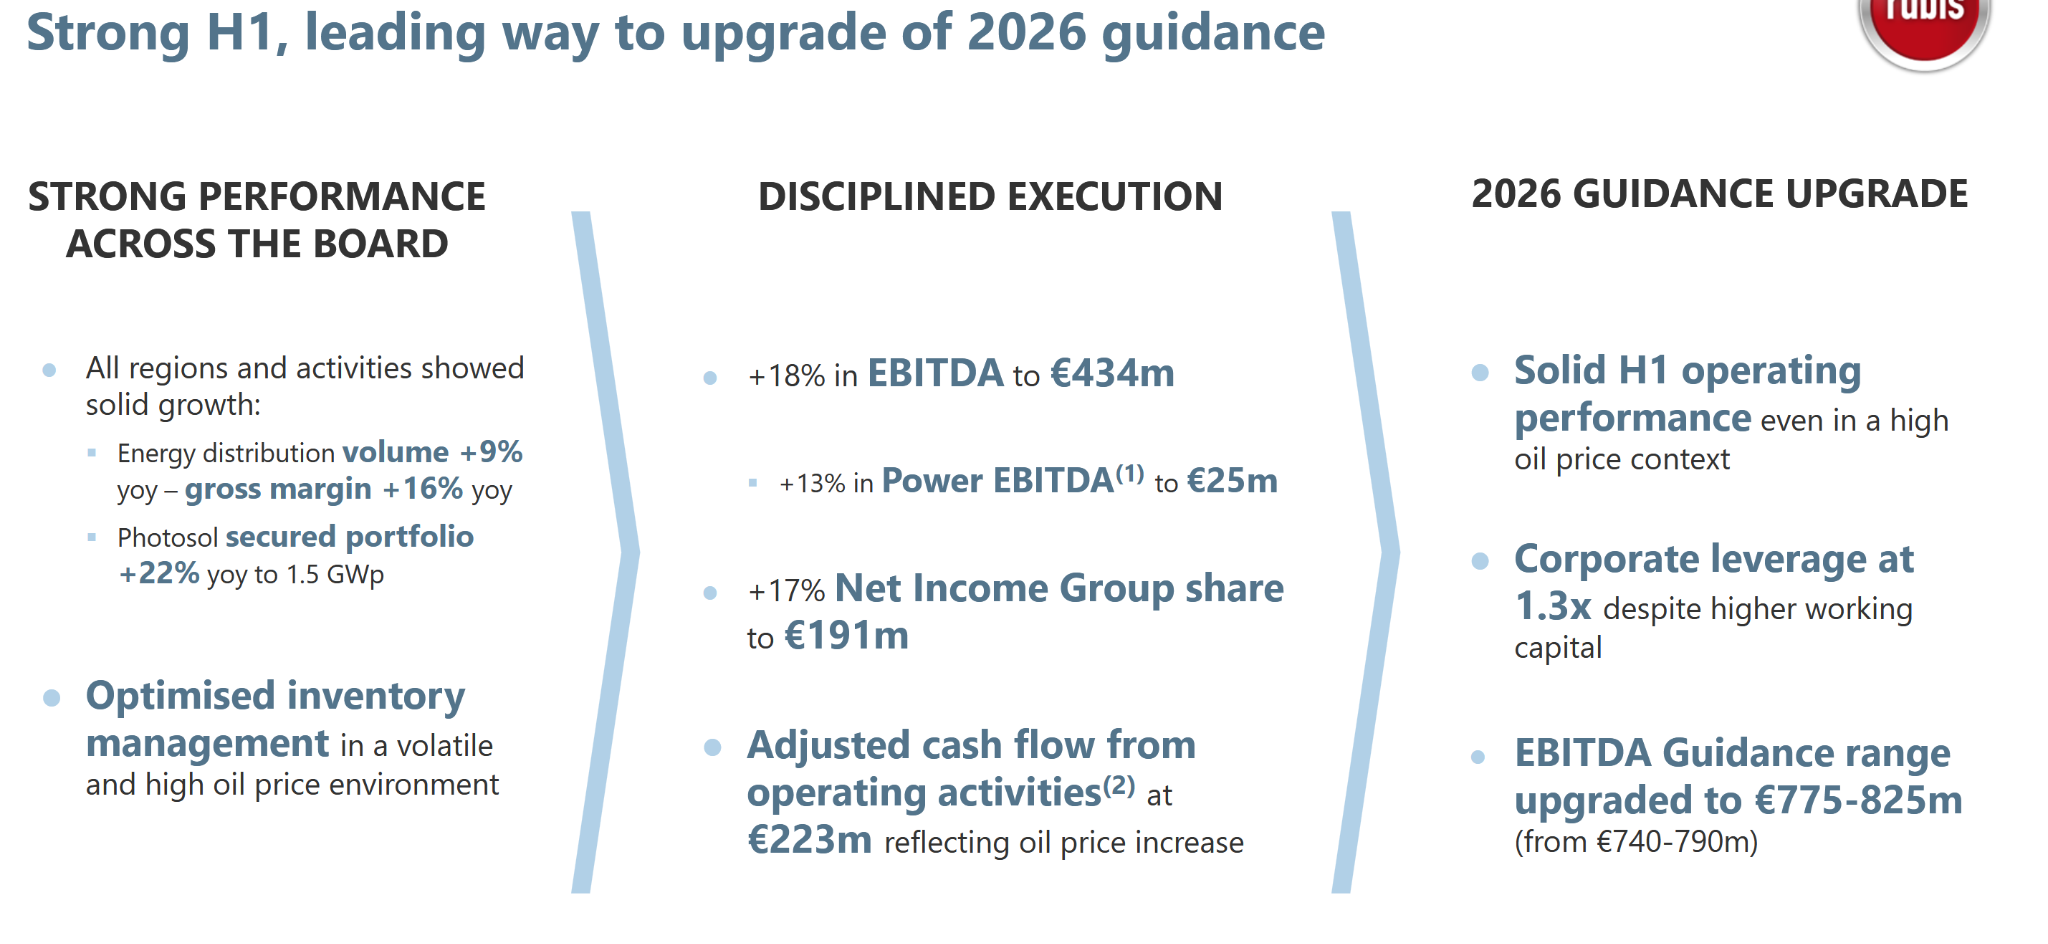
Looking at the share price, we can see that Rubis is up ~11% YTD, which is in line with earnings growth that had been +18% for the first 6 months:
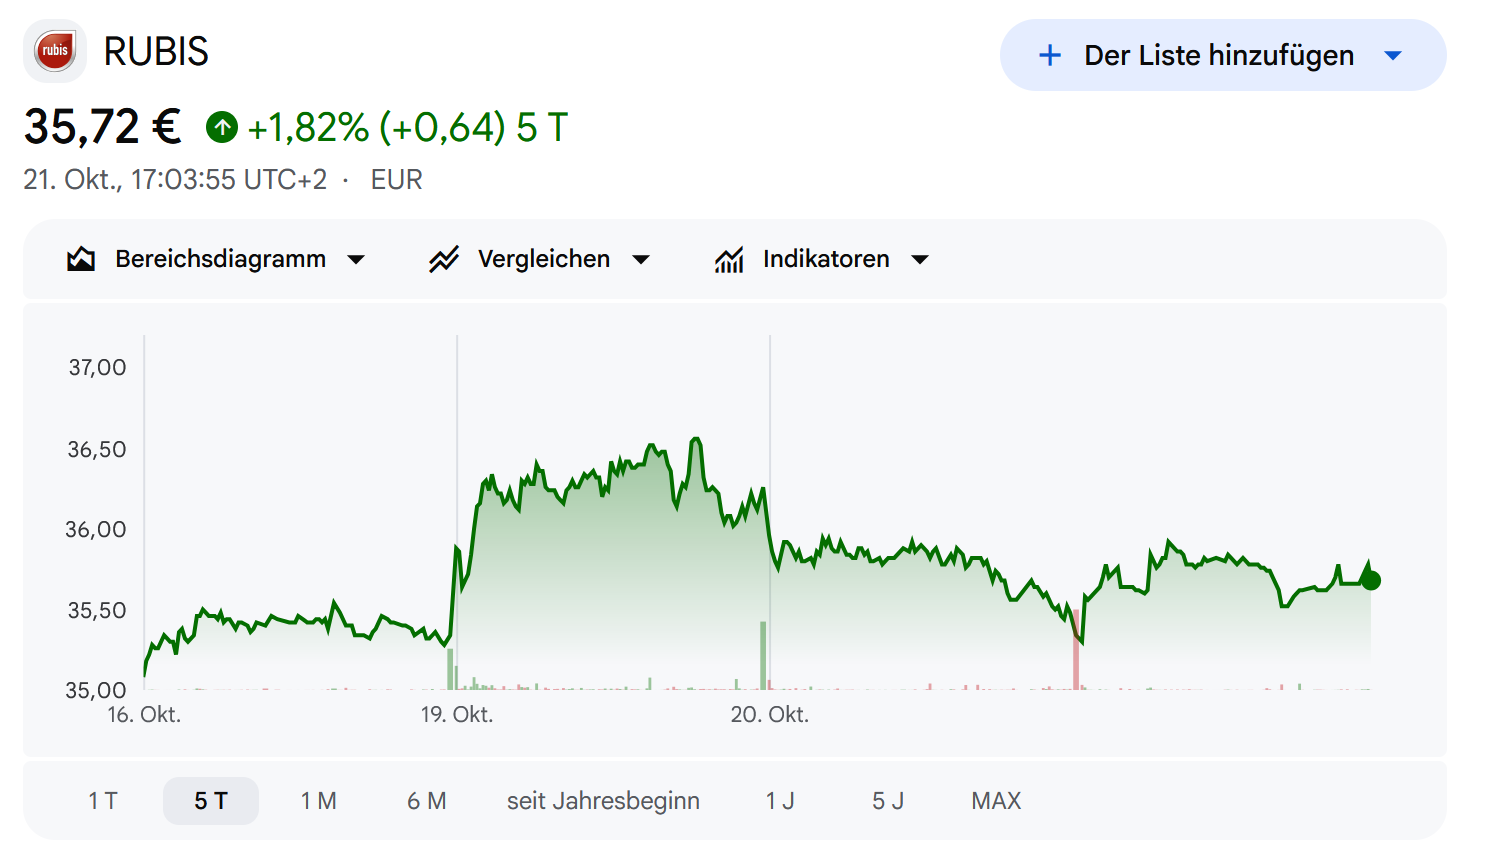
What I find interesting is that the share price didn’t react a lot on Monday’s surprise announcement, although all in all, this is quite positive for shareholders:
Similar cases in the past:

There was a very similar case in the past in France: Lagardere underwent the “same procedure”, also driven by behind the scenes activism from Boloré. The GP in that case got compensate by a share capital increase of ~8% but the shares jumped 10-15% after the announcement.

Subsequently, Lagardere was taken over by Vivendi by Vivendi and Lagardere Shareholders did quite well.

A somehow similar case was  Fresenius Medical Care, where Fresenius transformed FMC from a KGaA to a normal AG because they wanted to deconsolidate FMC and FMC subsequently performed quite well.

One can only speculate why Rubis didn’t move at all, but my guess is that the current riots in France and general Caution with regard to French stocks clearly plays a role here.

Good earnings momentum

Higher fuel prices are almost always good news for distributors and Rubis is no exception here. After  decent Q1, 6M numbers looked really good an dthe increased their guidance for 2026 significantly:
Investor base

Over the past few years, some prominent investors have disclosed stakes in Rubis:
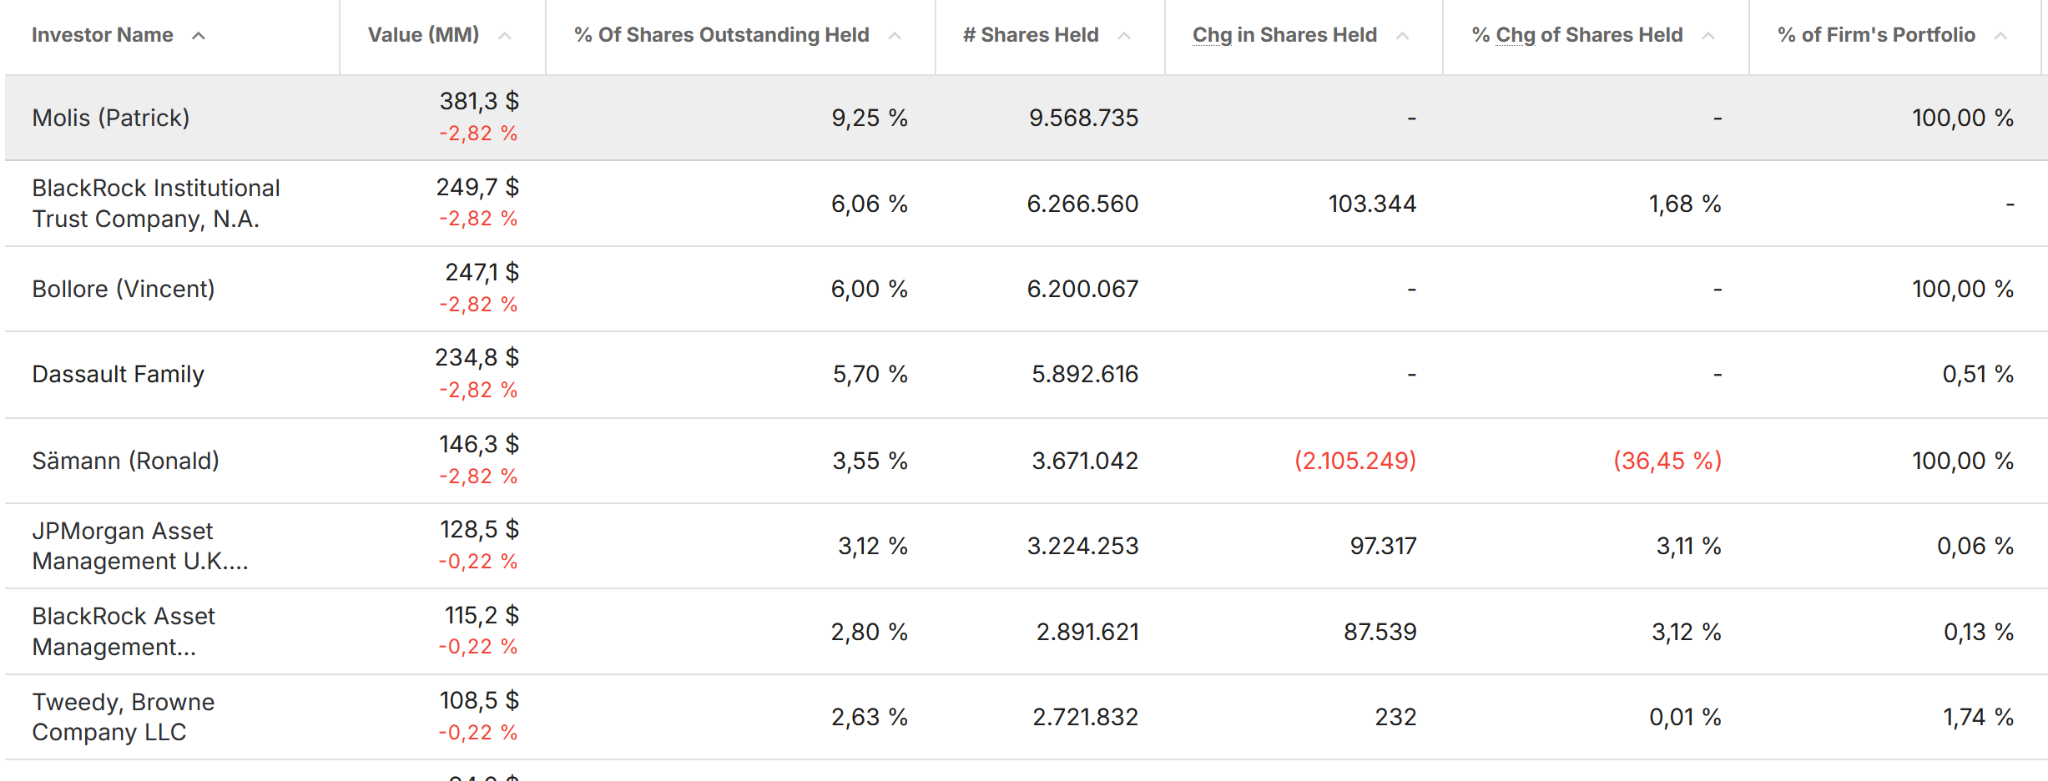
The largest shareholder, Patrick Molis is  a French Business man active in logistics who started a first position in 2023/2024. He had been openly activist in the company for some time, demanding among other things a complete overhaul of the board.

At the same time, Vincent Boloré disclosed a 6% stake. Boloré is especially experienced in African businesses. He also seemed to have been involved in Rubis in the 1990ies and seems to know Molis from a couple of previous interactions.

The billionaire Dassault family seems to own its stake already a little bit longer since 2017 or 2018. I didn’t find a lot about Ronald Sämann but he also seems on board since 2023/2024 and was actually part of the supervisory board until early this year.

Graoully has some more information on this eclectic group of shareholders in his post.

In any case, I assume that those shareholders will most likely not just sit around and be happy to collect dividends but they will continue to press for change and even more so once the structure is cleaned up.

What would a PE buyer do with Rubis

Already in September last year, there were relatively specific rumours that PE firm CVC and energy trader Trafigura were interested in taking over the company.

As we have seen with my previous portfolio company DCC, especially LPG and fuel distribution are highly attractive businesses for PE companies as these businesses are stable, can be leveraged and there is still ample room for consolidation.

In Rubis’ case, those two businesses would be clearly the main targets. The Renewable business would most likely be sold to a more specialised renewable fund or energy company, although right now, there are quite some renewable assets on the market.

That leaves us with the Bitumen business for which the natural buyers would most likely be competitors like Colas or the Swedish guys

My “sum of parts” estimate for such a scenario would be at least 50 EUR per share based on recent transaction multiples including DCC. Although one has to mention that Rubis’ geographic footprint makes this analysis a little bit more difficult. For those more exotiv locations, the number of buyers is clearly smaller, however potential growth in these countries is also much higher than in saturated markets.

A quick win of any “activist” would in my opinion be to spin off the renewables business and leave the Fuel and bitumen business together which would be a veritable cash machine. This could also lead to a decent rerating of the stock.

Return expectations

Other than a direct M&A “arbitrage” situation, the current situation at Rubis is a little bit more fluent.

My base case looks as follows: I look at a time horizon of 18-24 months. Within this time horizon I expect to:

  • receive 2 dividends of ~6% each
  • expect that the stock will reflect the structural improvement after the AGM has approved the change in december which should lift the stock price between 10-20% (average based on similar situations in the past)
  • expect at least some discussions about potential bids from either strategic players (maybe Boloré himself) or Private Equity)

My estimate for a Pivate Equity “take out value” would be around 45-50 EUR per share.

So my overall return expectation for Rubis, including dividend would be in the range of +30% to +40% in the base case including dividends.

The bull case would be a little bit higher, the bear case would be the dividend yield only.

Pro’s & Cons

So let’s summarize the Pros and Cons for this special situation quickly:

  • Operational tailwind with 18% profit increase in the first 6M 2026
  • Clear catalyst with structural change but so far not priced in at all
  • Stock is relatively cheap and offers an attractive dividend yield of 6%
  • After the restructuring, high likelihood of “value accretive” M&A activities due to the presence of strong activist investors and already existing interest
  • almost no exposure to French economy as such and French bond spreads

+/-  in general negative sentiment towards French stocks which limits short term upside

  • exposure to FX fluctuations and Hyperinflationary jurisdictions
  • PV assets are maybe not so easy to sell at a good price right now
  • some residual risk that the restructuring will not happen or be delayed because of the amount of the proposed compensation

Summary & game plan

Overall, I find the set-up quite interesting as an “early stage” special situation, despite the exotic geographical footprint of Rubis.

The relevant dates are as follows:

From an operational perspective, Rubis will announce a Q3 trading update on November 3rd. I assume that this trading update will confirm the positive trajectory of the business. The upside case would be a further upwards revision of the expected 2026 profit.

The most important  step will be clearly the formal approval of the restructuring in the special AGM on December 9th. Maybe this triggers some revaluation already, especially if maybe the compensation for the former “GPs” can be reduced a little bit.

I would then expect over the course of 2027 that we see more discussions on how to “catalyze” the value of Rubis. Either through renewed negotiations with CVC and Trafigura or some other actions.

My “long stop” date for this will be Mid 2028. If nothing happens until then, I will get out in any case.

Overall, I find this set-up attractive enough to allocate a 2,5% position of the portfolio into Rubis at the current price of ~35,50 EUR per share.

I partially financed the position with further sales of STEF, which has much more exposure to France, high French interest spreads and high fuel costs.
CEWE Group CMD – More potential upside than I thought

DISCLAIMER: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!

Background/Follow up:

When I wrote the initial post about CEWE a few days ago, I didn’t know that CEWE actually held a Capital Markets Day for selected investors on the very same day that I was publishing my post. They didn’t disclose it on their Website or IR calendar either.

Anyway, in the meantime, the slides are online.

On the capital markets day they presented more background on the Kodak acquisition. In a nutshell, I can now better understand the rationale and see it as less opportunistic but more strategic than without that information.

I think there are clearly some risks with the Kodak Moments acquisition, but on the other hand, there seems to be also a plausible path for some extra growth on top of the rather slow growth in the past few years.

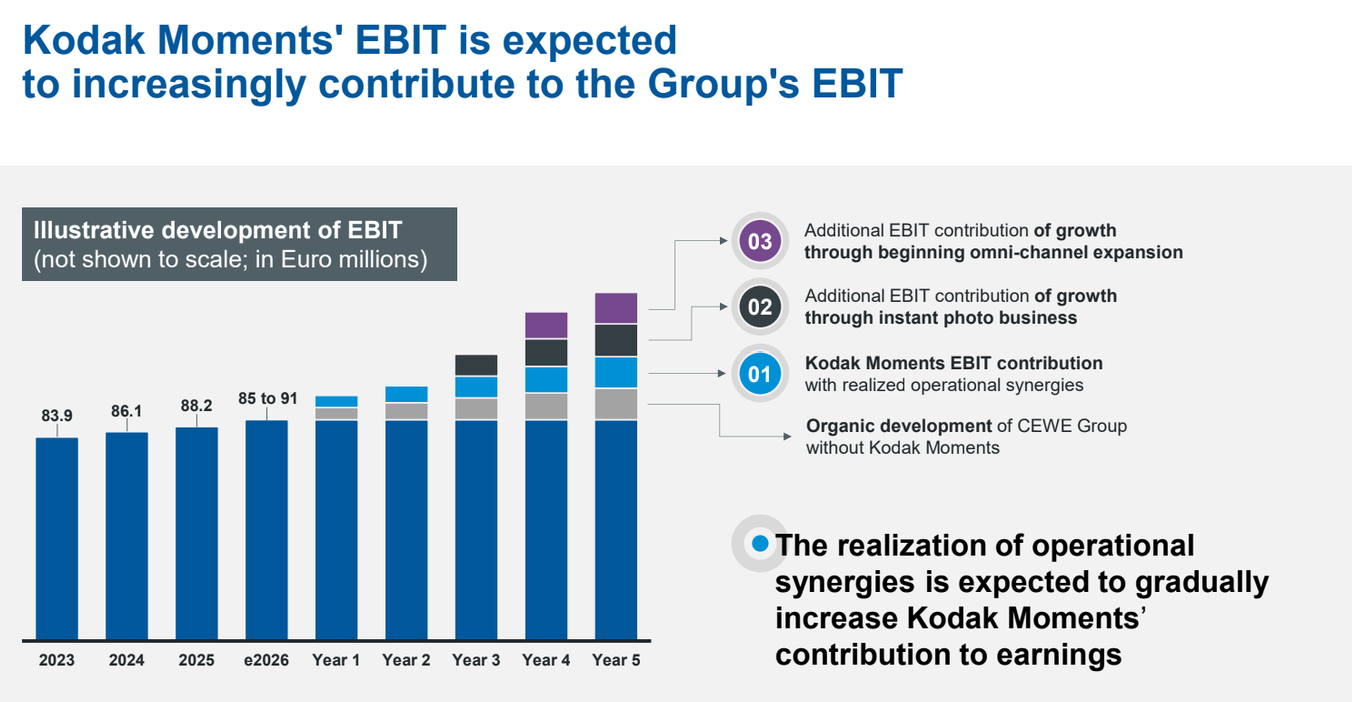
Here are a few interesting snippets:

Although there are no actual numbers, they project EBIT growth that in the first 2 years is double the organic run rate and up to almost 3x in year 5. As organic growth in the last years was more like 3-4%, this implies growth rates of 6-10% for the next 5 years which would of course be really great.

If growth would actually accelerate like this, then there is also a decent chance that the stock might get back to historical valuation ranges. So in the upside case, there is potentially much more upside than I thought initially.

One detail they seem to have mentioned only verbally is that Kodak Moments currently only charges around 50% per printed picture than CEWE. It seems that Kodak’s quality is also lower, but this is clearly a relatively simple lever for CEWE to increase prices (and quality) up to CEWE’s levels.

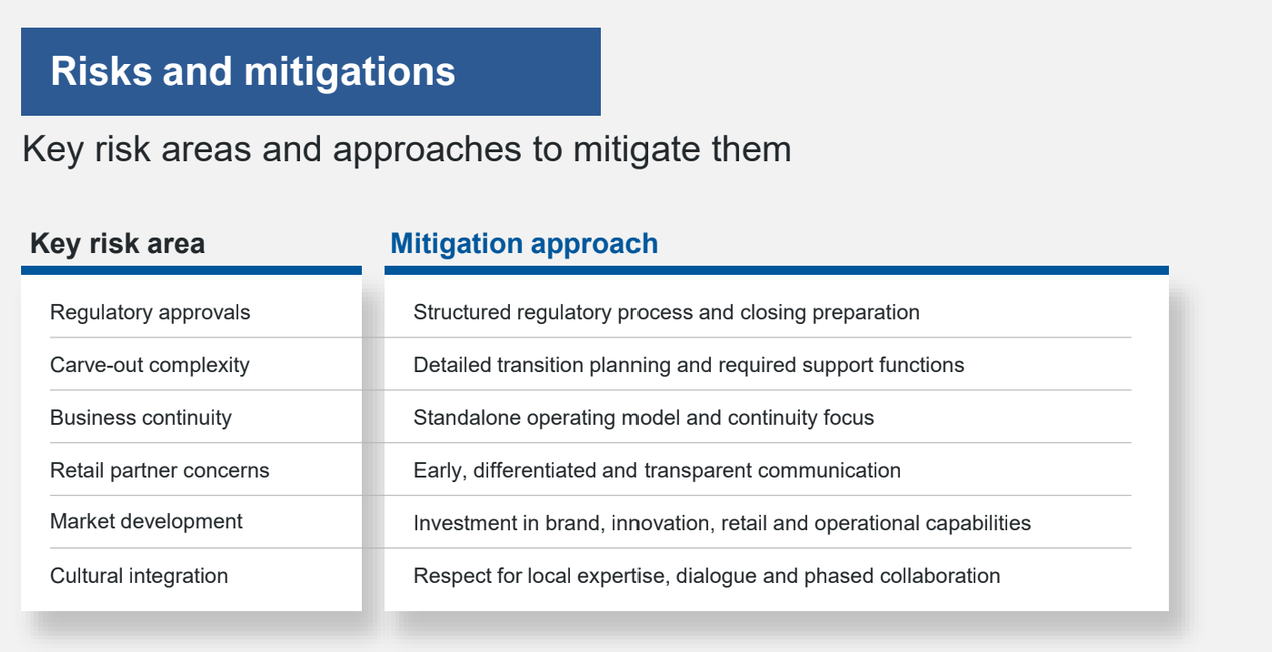
They also point toward some risk, where the regulatory approvals might be the most relevant ones:

From previous reports one can estimate that ~40% of Kodak Moment’s business is actually from Germany.

The attractiveness of the instant photo kiosk business

Another aspect that seems to have been mentioned in the call is that the “instant photo” business as such has been growing nicely within CEWE already. I always thought that only the online photo books were the growth driver, but with this information, the acquisition could make even more sense.

I did a little background research on these photo kiosks and it seems that they fulfil quite an interesting niche for customers.  We shoot more and more digital pictures and it seems that from time to time, people have the urge to print out pictures rather today or tomorrow than to wait 4-5 days and uploading them online.

Modern Photo kiosks often offer additional formats like larger prints or even more sophisticated Greeting card or invitation card formats.

On my past visits to a dm or Rossmann, I always checked on the photo kiosks and I was surprised how busy they are at any time of the day. Interestingly, I have seen branches where CEWE stations were next to Kodak stations in the same store.

From the perspective of the drugstores, these photo kiosks seem to be helping to draw customers into the store who might then also purchase something else. So these photo kiosks seem to look like a win-win. It would be interesting to know how the revenue sharing looks between Rewe/Kodak and the drugstores.

Some other aspects of CEWE

Governance/Incentivation

As a KGaA, the Governance is different to a normal “AG”. Effectively, common shareholders have no say who runs the company, this is solely determined by the “Komplementär”, in this case the foundation of the family that owns around 30% of the shares.

Therefore it is important to understand how Management is incentivized. In CEWE’s case, the variable component of the Management’s salary is relatively small and almost exclusively tied to EBT development. So no per share or Return on Capital measures.

There is a share option program but the amounts are rather insignificant.

From that perspective, incentives are not optimal. Interestingly, they still buy back some shares and report ROCE, but the variable component of the Board’s compensation really only depends on absolute EBT.

Share price momentum

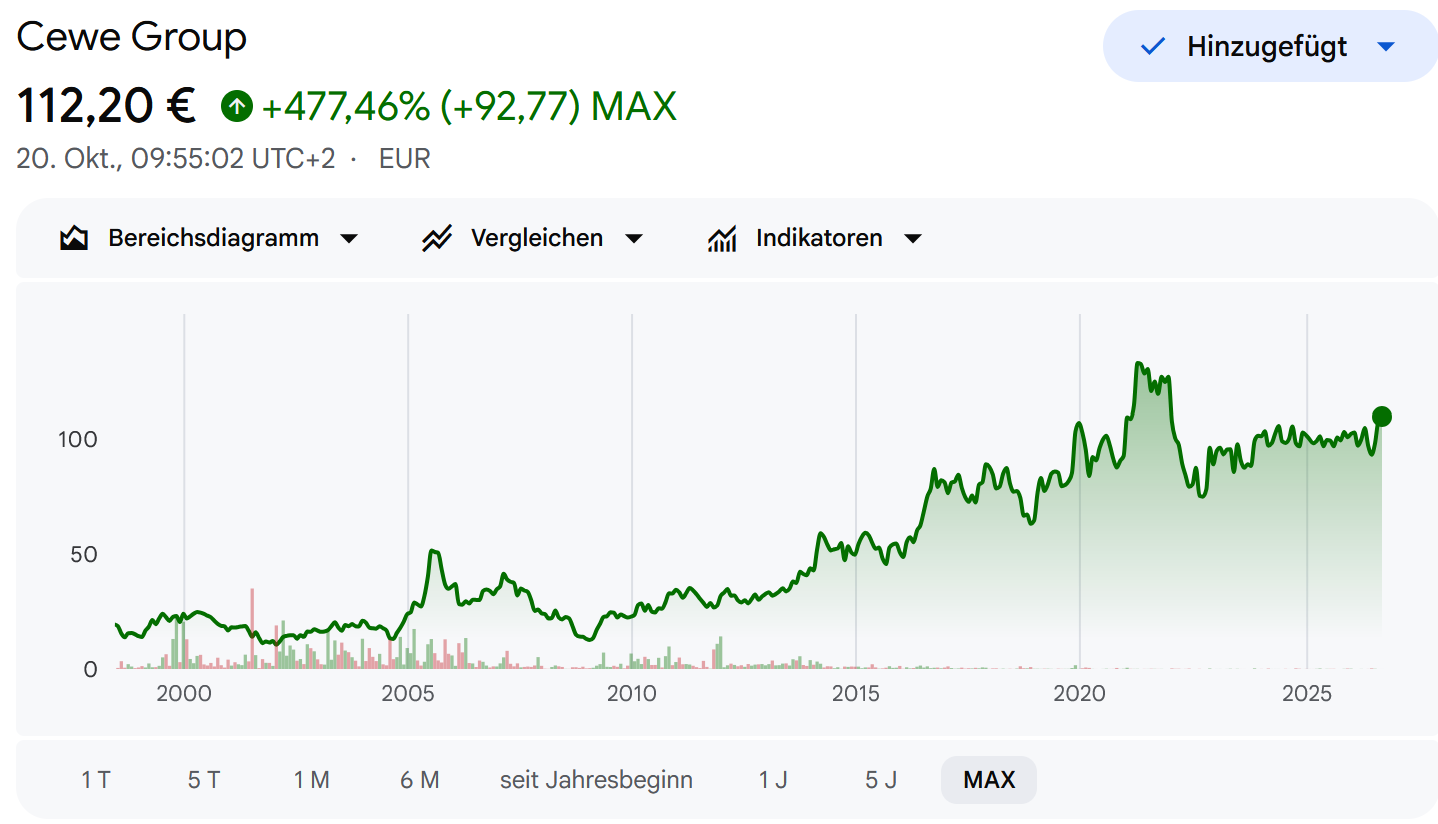
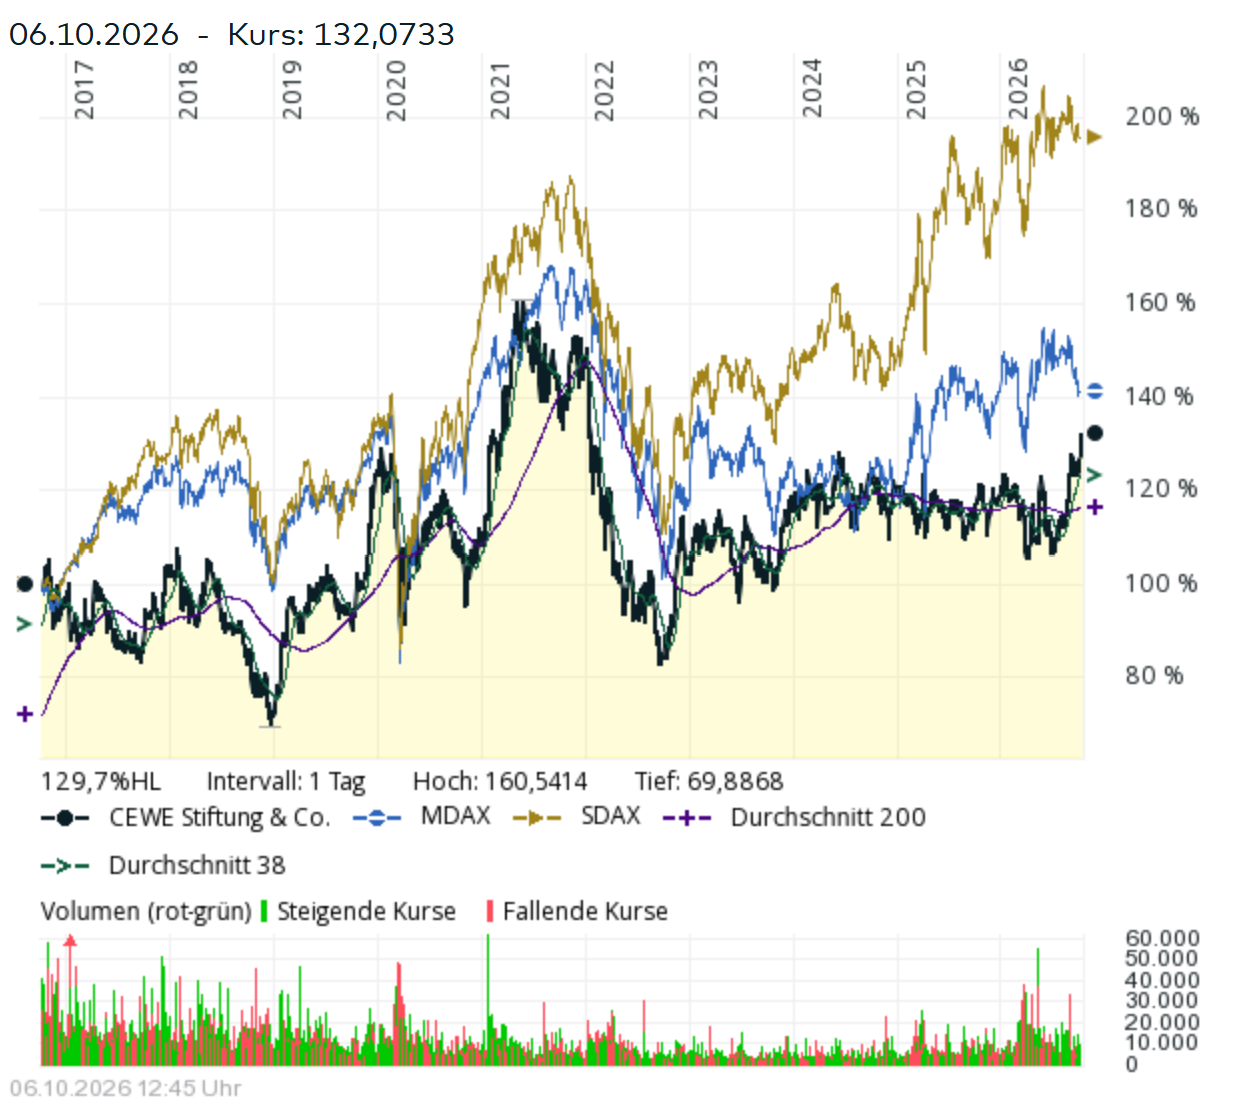
Although it is not a criteria per se, the stock has positive Momentum. Looking at the long term chart, we can see that it is still below the ATH from COVID, bt it has been breaking out a little from a trading range recently:

In my screening model, the overall score at the moment is quite good, putting CEWE fromly into the top 10 of stocks that I monitor.

Summary & conclusion

Following the CMD material, I have become more optimistic about a potential longer lasting growth runway following the Kodak Moments Acquisition.

As mentioned above, I now better understand the motives and think that there is a potential for some additional growth if they execute that acquisition well.

I therefore decided to allocate 3% of the portfolio into CEWE at the current price of ~112 EUR per share. My expected investment return for this will be somewhere between 40-50% including the dividend yield, buybacks and maybe a little valuation uplift over the next 2-3 years. This is clearly not exceptionally high, but I think the downside is also relatively well protected at less than 9x EV/EBIT.

Due to the Governance topic (KGaA) and suboptimal Management incentives, I will most likely not increase the position much above the current level. For a full position, I would need better scores on that aspect.

The next milestones will be as every year, the result of the all important Q4 and then in 2027 the successful closing of the Kodak moments transaction.

Some links 26/2026

Chinese researchers conclude that Ai cannot pick (Chinese) stocks successfully

The Slow Compounding Substack on Swedish Serial Acquirer Momentum Group

KNA Capital thinks that Howden’s has a great opportunity in the US (Via Flyover stocks)

Quick pitches for three cheap French Technology stocks

Another set of short musings from Graoully

A nice interview with Jensen’s Group CEO and Chairman

The Blackwood Research Substack has a great series of unusual stocks

Updates: DCC (sold), TFF (sold), EVS (hammered) & Rightmove (rumours)

DCC – post mortem

Let’s start with the positive case. I realized my DCC position recently as the share price (~64,4 GBP) approached the bid value (66,72 GBP) and the remaining upside was not so attractive anymore, especially considering potential GBP volatility for me as a EUR investor.

Looking back at the initial write-up, the result was pretty Ok.  

I made slightly over +50% over 3 ¾ years plus some more on the additional portion I bought after the first bid in May this year. This was within the expected range of outcomes:

However, and this is a big HOWEVER, this positive result was not driven by the business case that I had underwritten, but purely a function of the premium paid by the acquirer KKR.

Looking at the earnings history, we can see that DCC’s earnings didn’t improve at all since my purchase in late 2022:

DCC rather had to go through a painful restructuring because they found out that everything they acquired outside their core business Energy was rather not good.

To be honest, I didn’t see this when I invested back then. I rather thought that having 3 different “platforms” gives them a lot of flexibility to allocate capital.

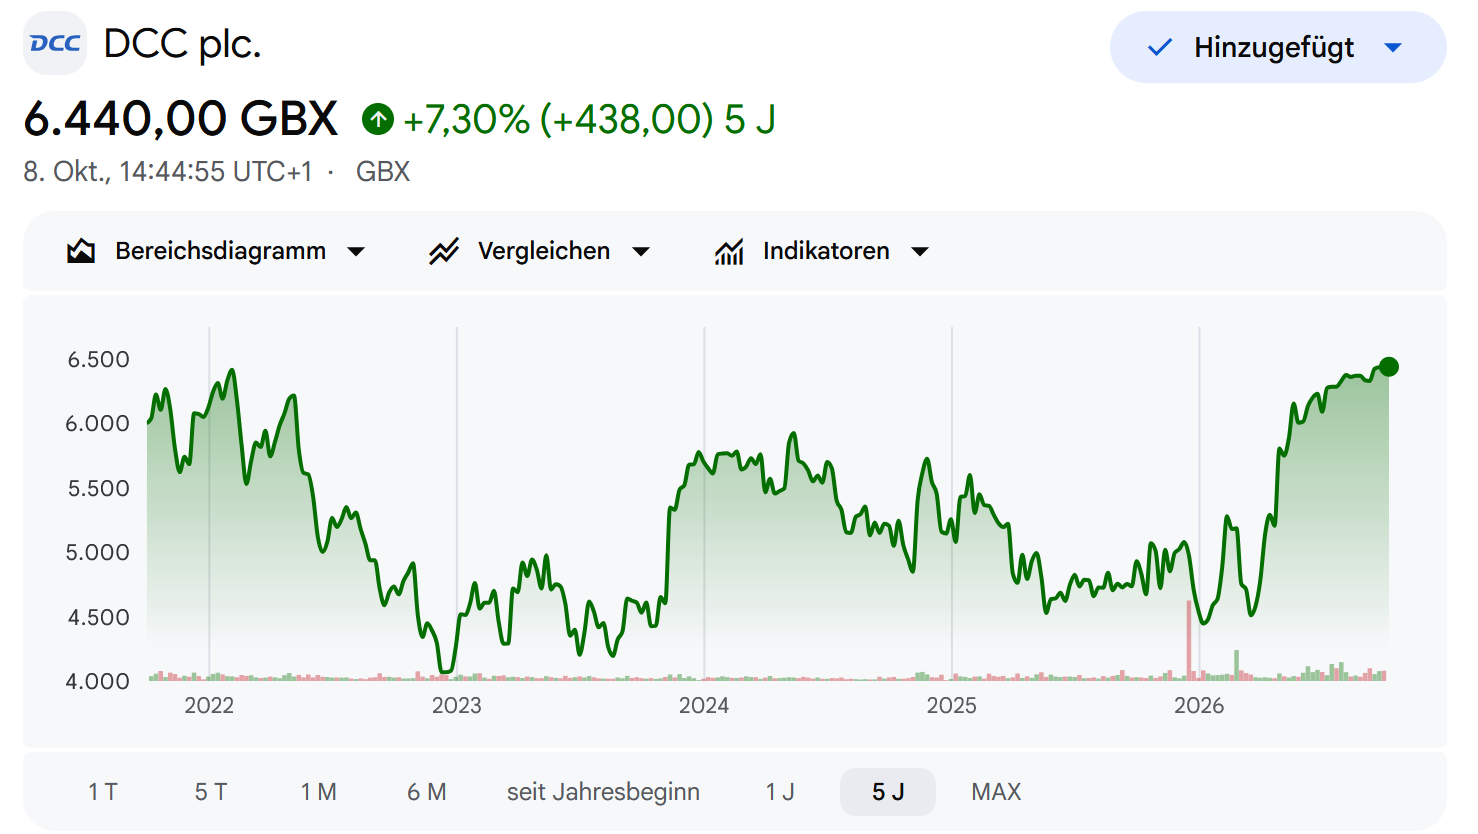
Looking at the stock chart we can see that my entry timing was quite lucky, but then not much happened until very recently:

So the positive outcome of this investment was much more luck than my ability to pick an undervalued company with a great past that performed well.

I think this is/was maybe a major weakness of my investment approach: Just assuming that a successful past is a good indicator for an equally successful future, depsite some temporary headwinds. This can work, but it clearly doesn’t have to work.

What went well though was the decision to increase the position after the first bid. While this was not a huge performance driver for the overall position, it was a very low risk Special situation add-on.

Quick update: Just an hour ago, DCC announced that they sold the remaining business from the Technology segment for a rather “lowish” price. From a potential 125 pence “Sweetener” for this deal the actual outcome seems to be “only” 42 pence now.

TFF post mortem

Funnily enough, I funded part of my DCC position as mentioned above with a partial sale of TFF, which back then was my largest position. I just checked my files and I sold ~11% of my position back then for ~39,70 EUR per share.

TFF was my oldest position and the only stock remaining from the initial portfolio from December 2010.

So why did I decide to sell now ? To be honest, i had been thinking about reducing/selling for quite some time. I wrote about my doubts already in the 2026 performance review in January 2026 and subsequently sold my Laurent Perrier shares.

With regard to TFF,  I cautiously thought that maybe the worst is behind us.

And:

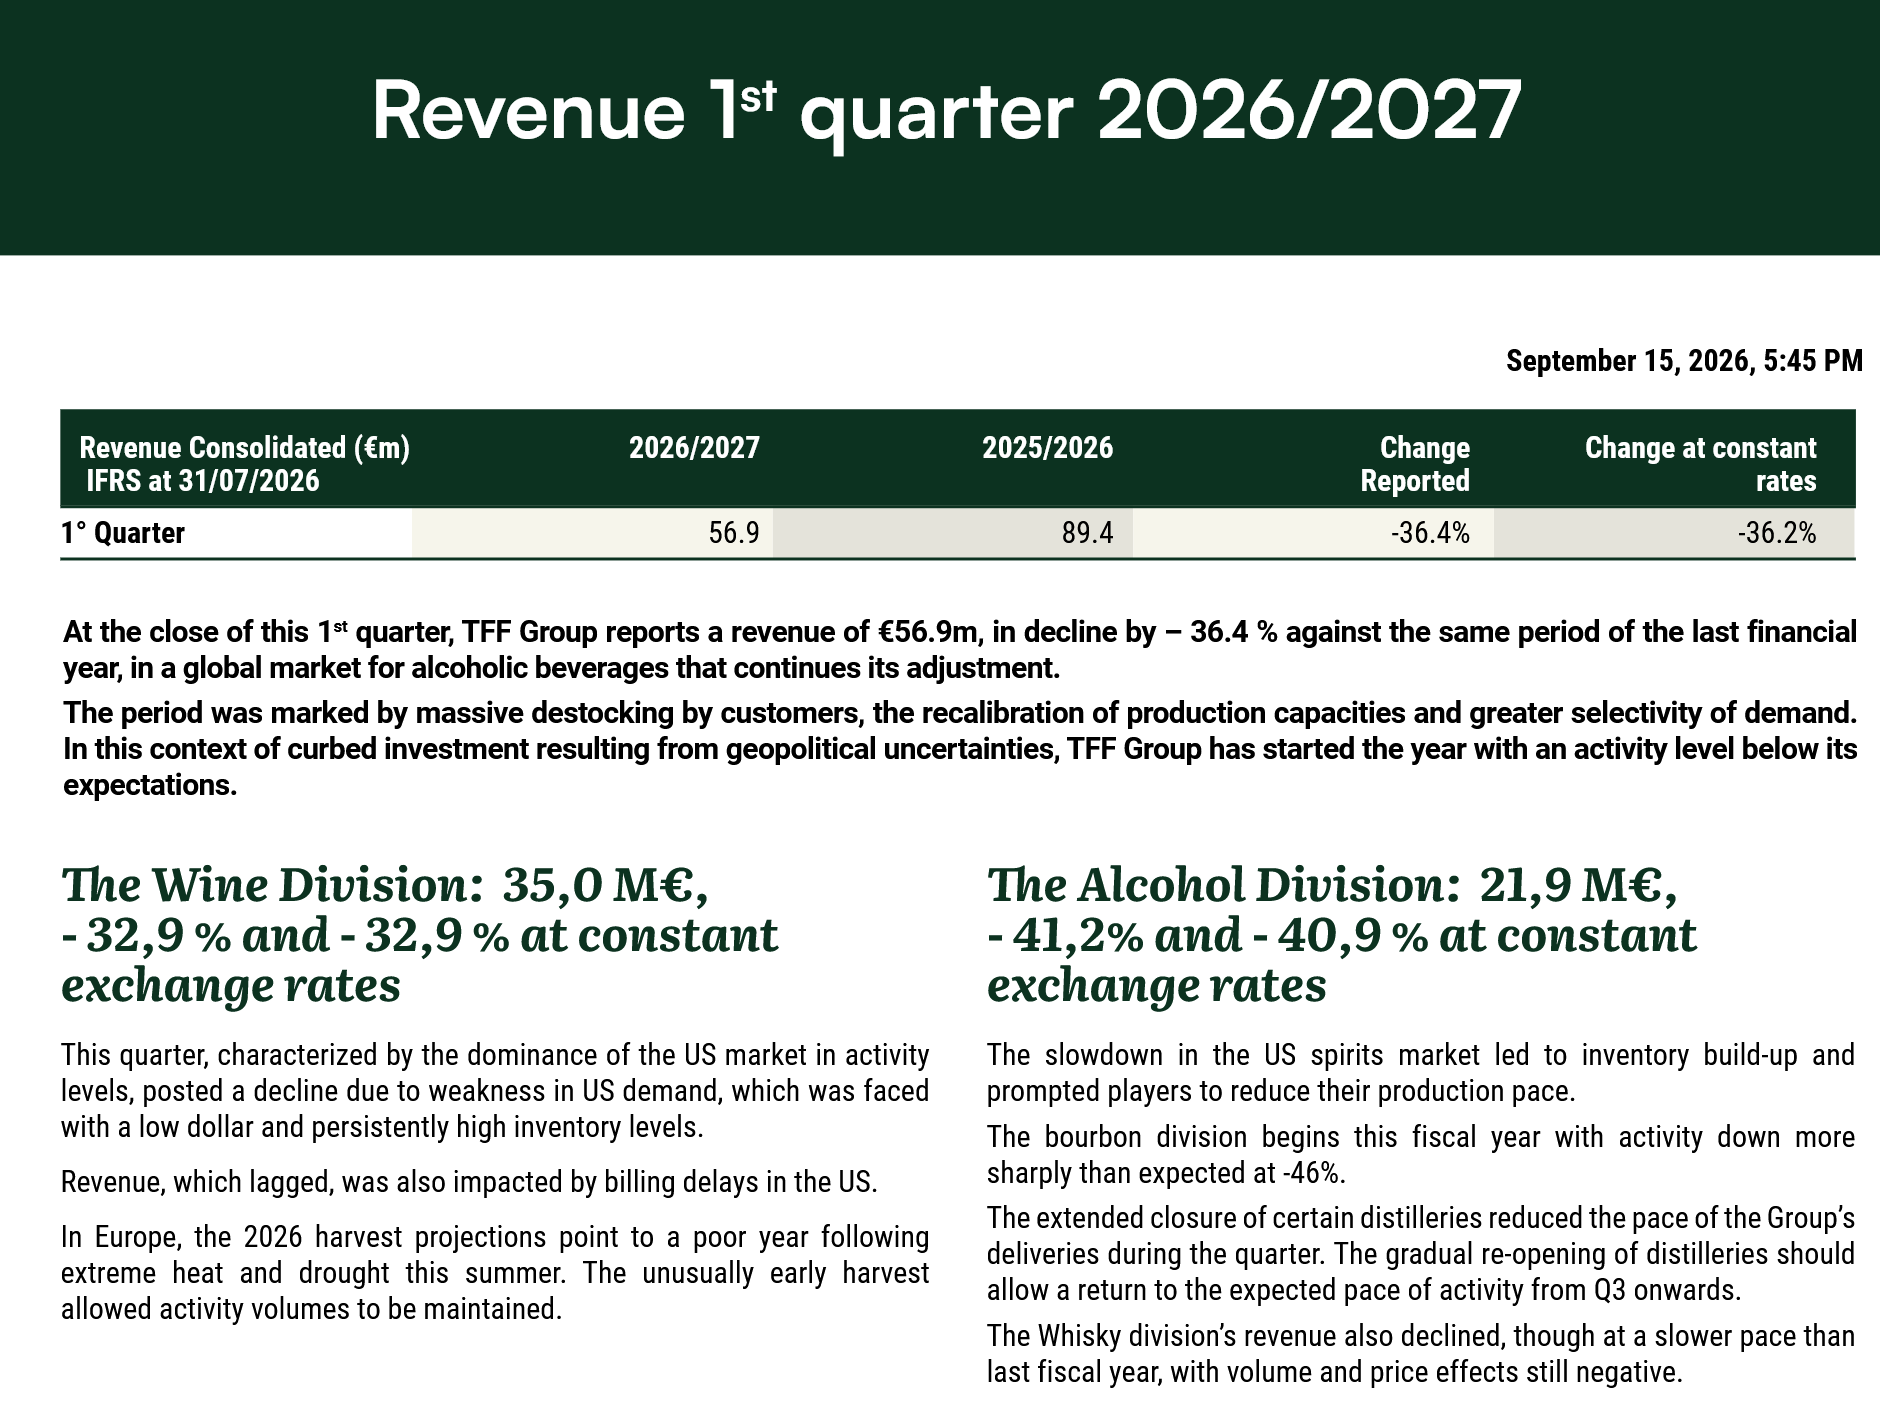
Then however came the horrible horrible Q1 (2026/2027) report in mid Septmeber which showed once again an acceleration of the sales decline, both in Wine and Whisky:

What really worries me now is the debt level of TFF. With declining Sales and profits, the 300 mn in net debt will become a larger and larger burden and refinancing this with the rapidly increasing interest rates especially in France is clearly not so easy.

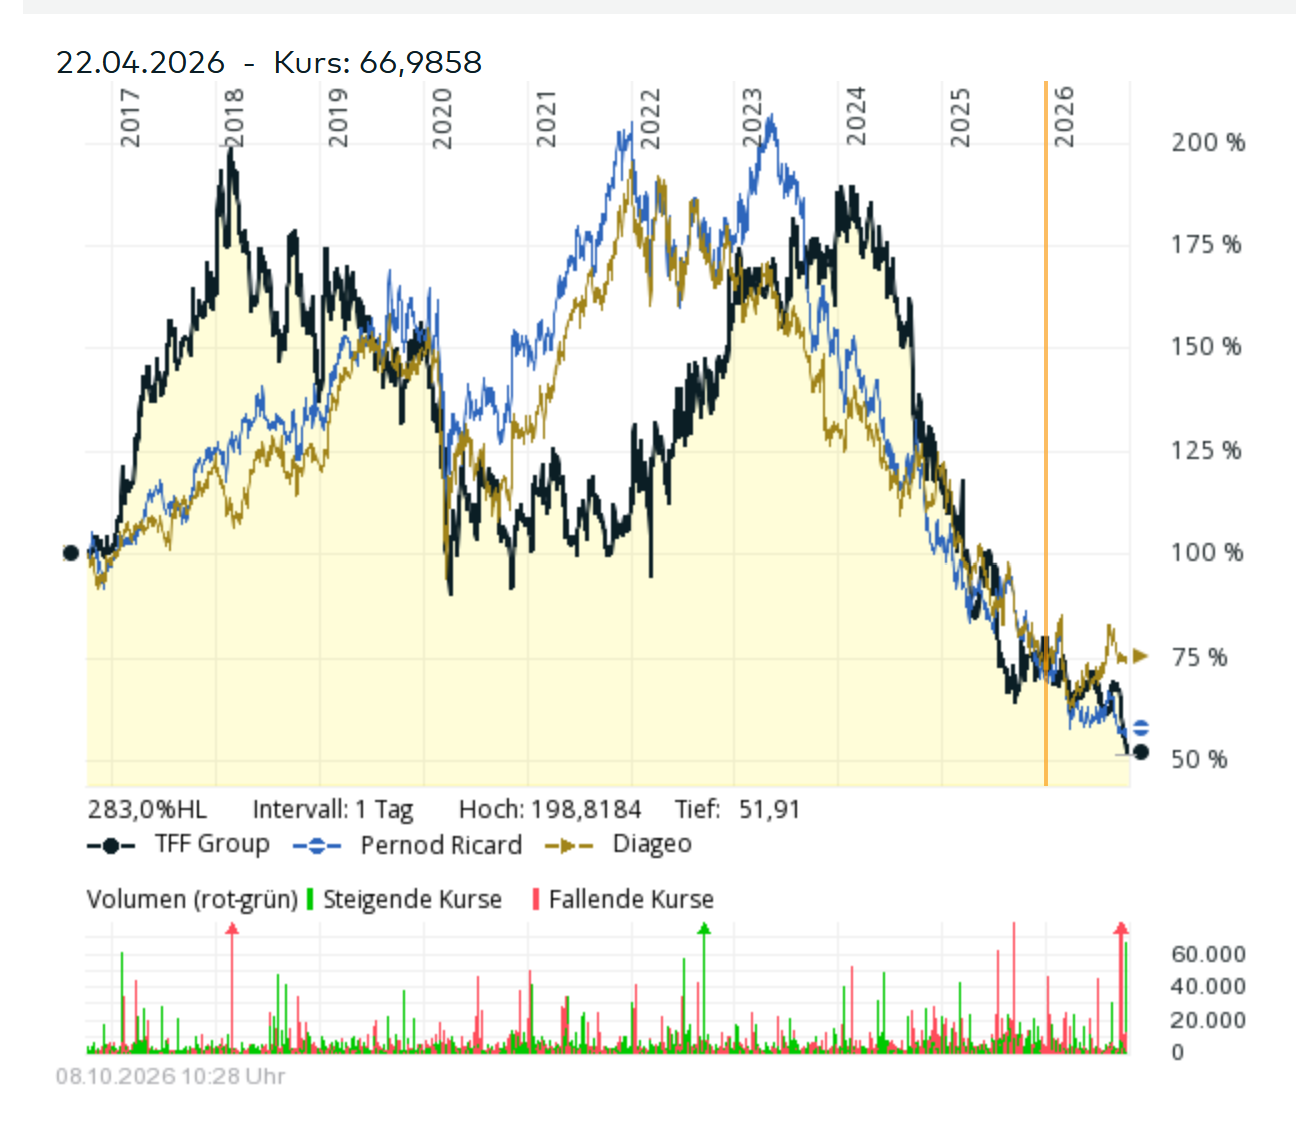
What I find interesting, looking at the charts of TFF  vs. Pernod and Diageo, is that TFF’s share price for some reason kept up longer than the actual spirits makers:

One of the disadvantages of writing a blog is that when I write about a decision like this one, the risk is relatively high that I look like a complete idiot if the stock rebounds within a short period of time. Then the usual group of trolls will make nasty comments that I delete (of course).

I think that was also one of the implicit reasons why I didn’t sell earlier. Going forward, I think I will move from a “real time blog portfolio” to something like a “quarterly rebalanced watchlist” in order to avoid such “mental traps”.

In any case, after almost 17 years, I sold my TFF position which now was only 2% of the portfolio. My average purchase price (including a later purchase at a higher price ) was 11,75 EUR and I collected 4 EUR in dividends per share. That’s about 2% p.a. over almost 17 years. It improves a little bit taking into account the mentioned partial sale in 2022. But overall, the result was not great.

EVS

Luckily, I sold EVS in July because I didn’t feel comfortable after the CFO suddenly disappeared and numbers looked weak in an “event year” with Olympics and the Football Worldcup.

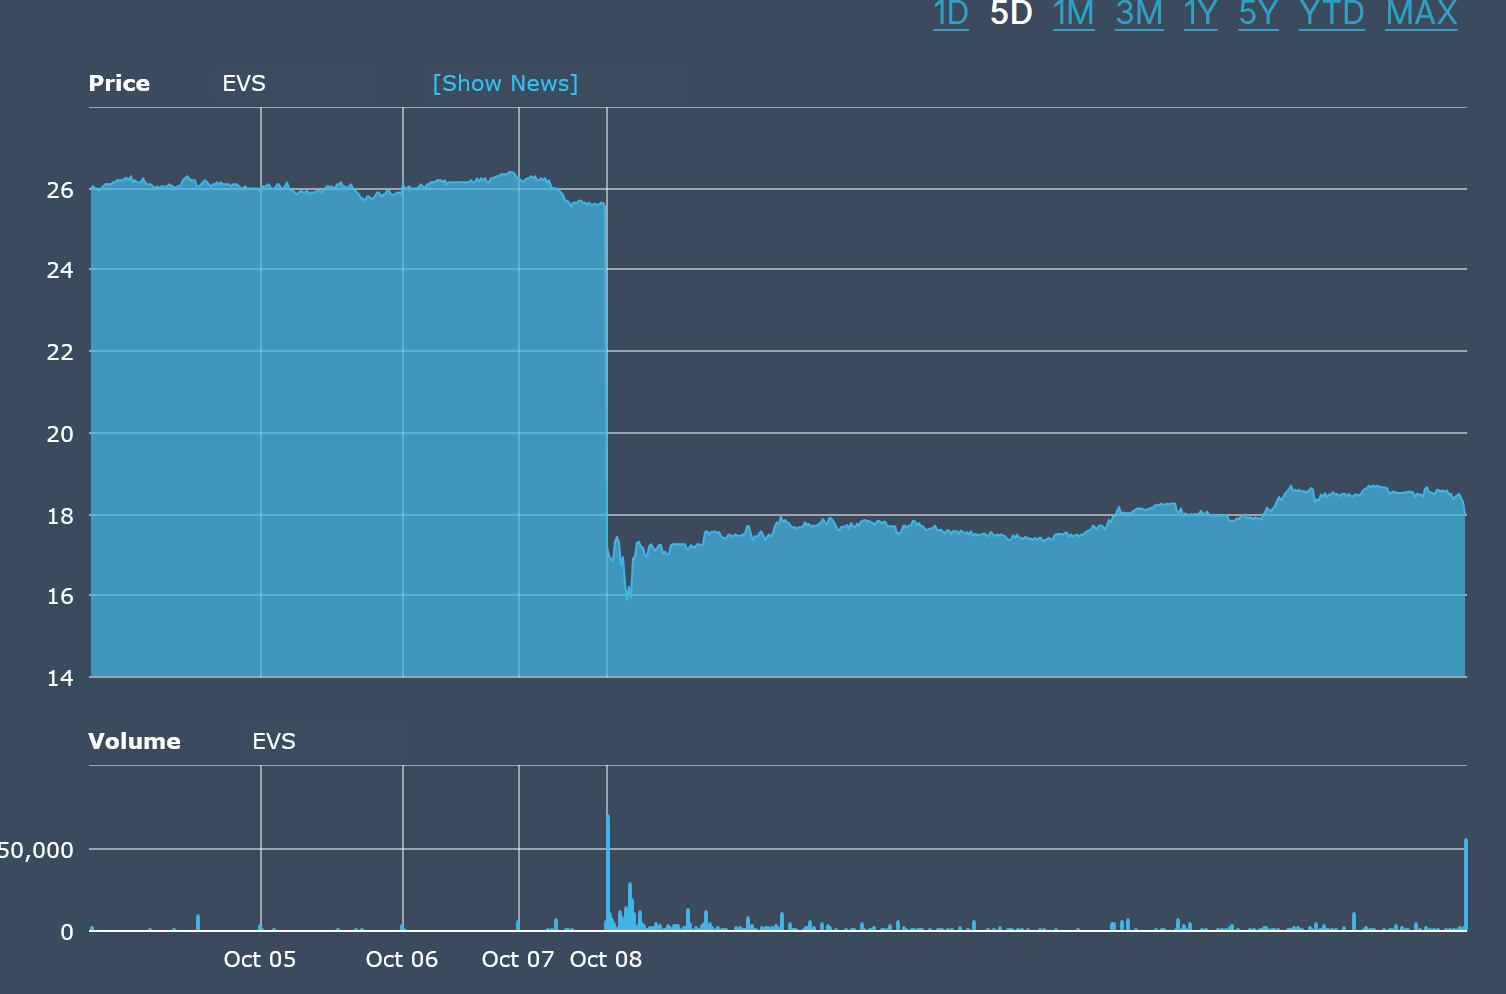
Yesterday, EVS drastically reduced their sales outlook for 2026 and the stock got hit really hard and was down -30% at the end of the day:

And this after being already down -30% YTD.

In this case, my timing was fortunately better than usual. 

Rightmove 

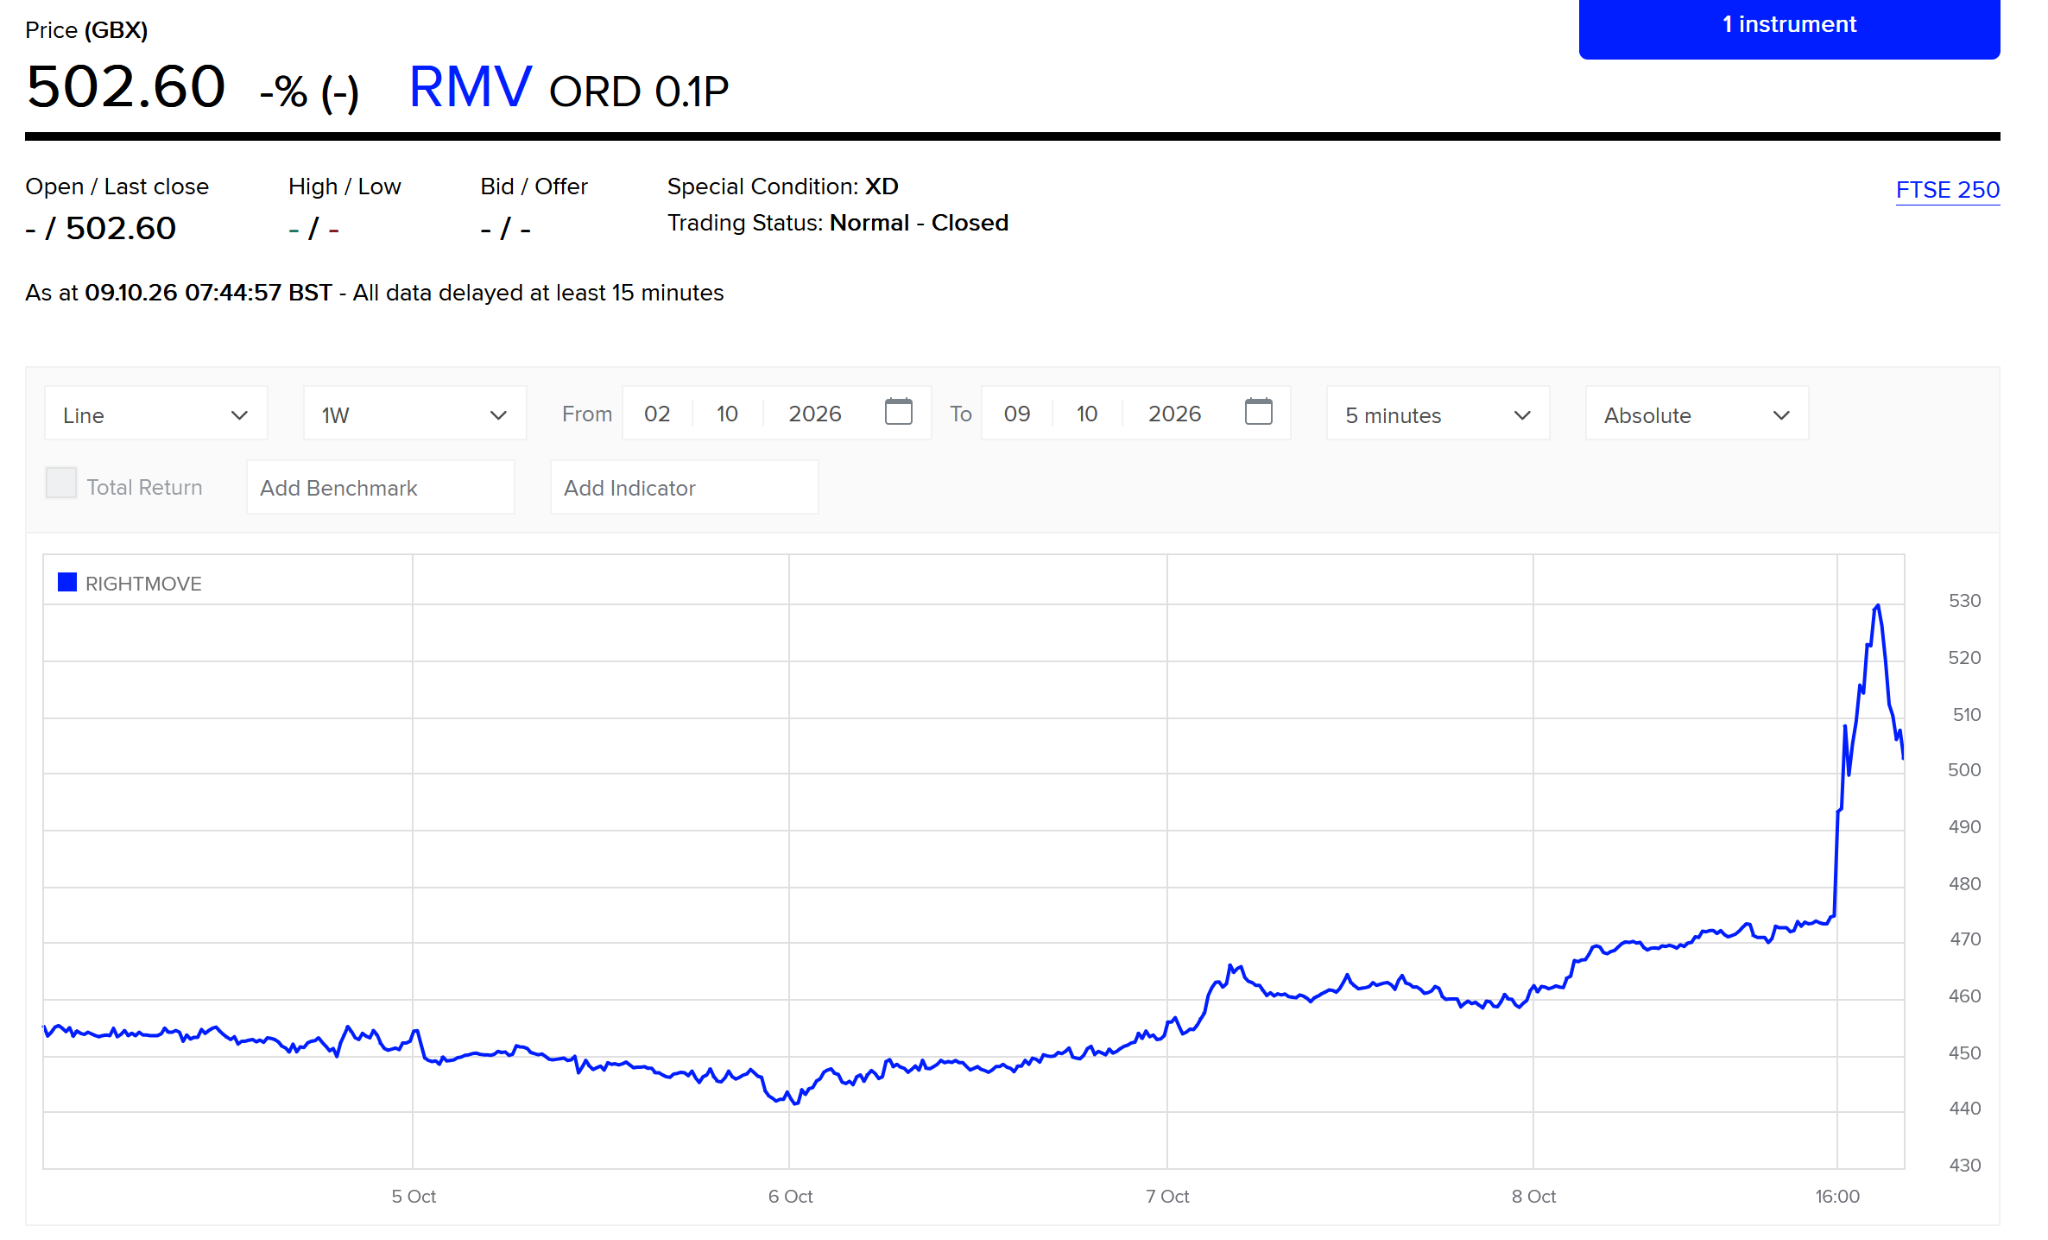
Yesterday around 4 pm my time, Rightmove suddenly jumped almost 15% because an outlet called “Betaville” mentioned that they heard about a rumor of take over interest for Rightmove.

No one knows if there is any truth in that or not, but the significant reaction in the share price in my opinion shows that maybe (and this is a big maybe), the worst is behind for the major classified/marketplace players.

CEWE KGaA – Good company but not a “Buy” yet ?

Upfront remarks & Management summary:

This is not a deep dive but more like my typical “first round screening” of a potential interesting investment. In the past, I would have not necessarily published it if I didn’t invest. Going forward, I will now and then publish these “initial assessments” mainly in order to receive feedback from readers who might see it differently. So please give feedback if you see things different !!!

As a Management Summary, I did not invest. Although I like the company, I could not build up the conviction for a 3-5 year investment case mainly due to recent slow growth and a somewhat risky acquisition. 

Company History:

Cewe Color traces its roots back to 1912 to a photo finishing lab in the Northern German town Oldenburg. And that’s what they did for the next ~100 years: “finishing” or “developing” Fotos from films that were given or sent to them. For the (few) younger readers: In the old days, there were real photo cameras where you took the pictures on a rol of film and you could only look at the pictures after they came back from the phot finishing lab.

In 1951 they introduced color pictures, 1994 they started to develop digital pictures and in 2025 they introduced the category that is today’s most relevant: The photo book.

in 2007/2008, CEWE became the target of US activist Guy Wyser-Pratte, who wanted CEWE to speed up its transformation into a digital player. However, in 2008, the activists lost interest.

As a consequence of this “activist attack”, CEWE changed into a KGaA structure in 2013, which makes it factually impossible to take over the company as the listed shares are effectively only non-voting shares.

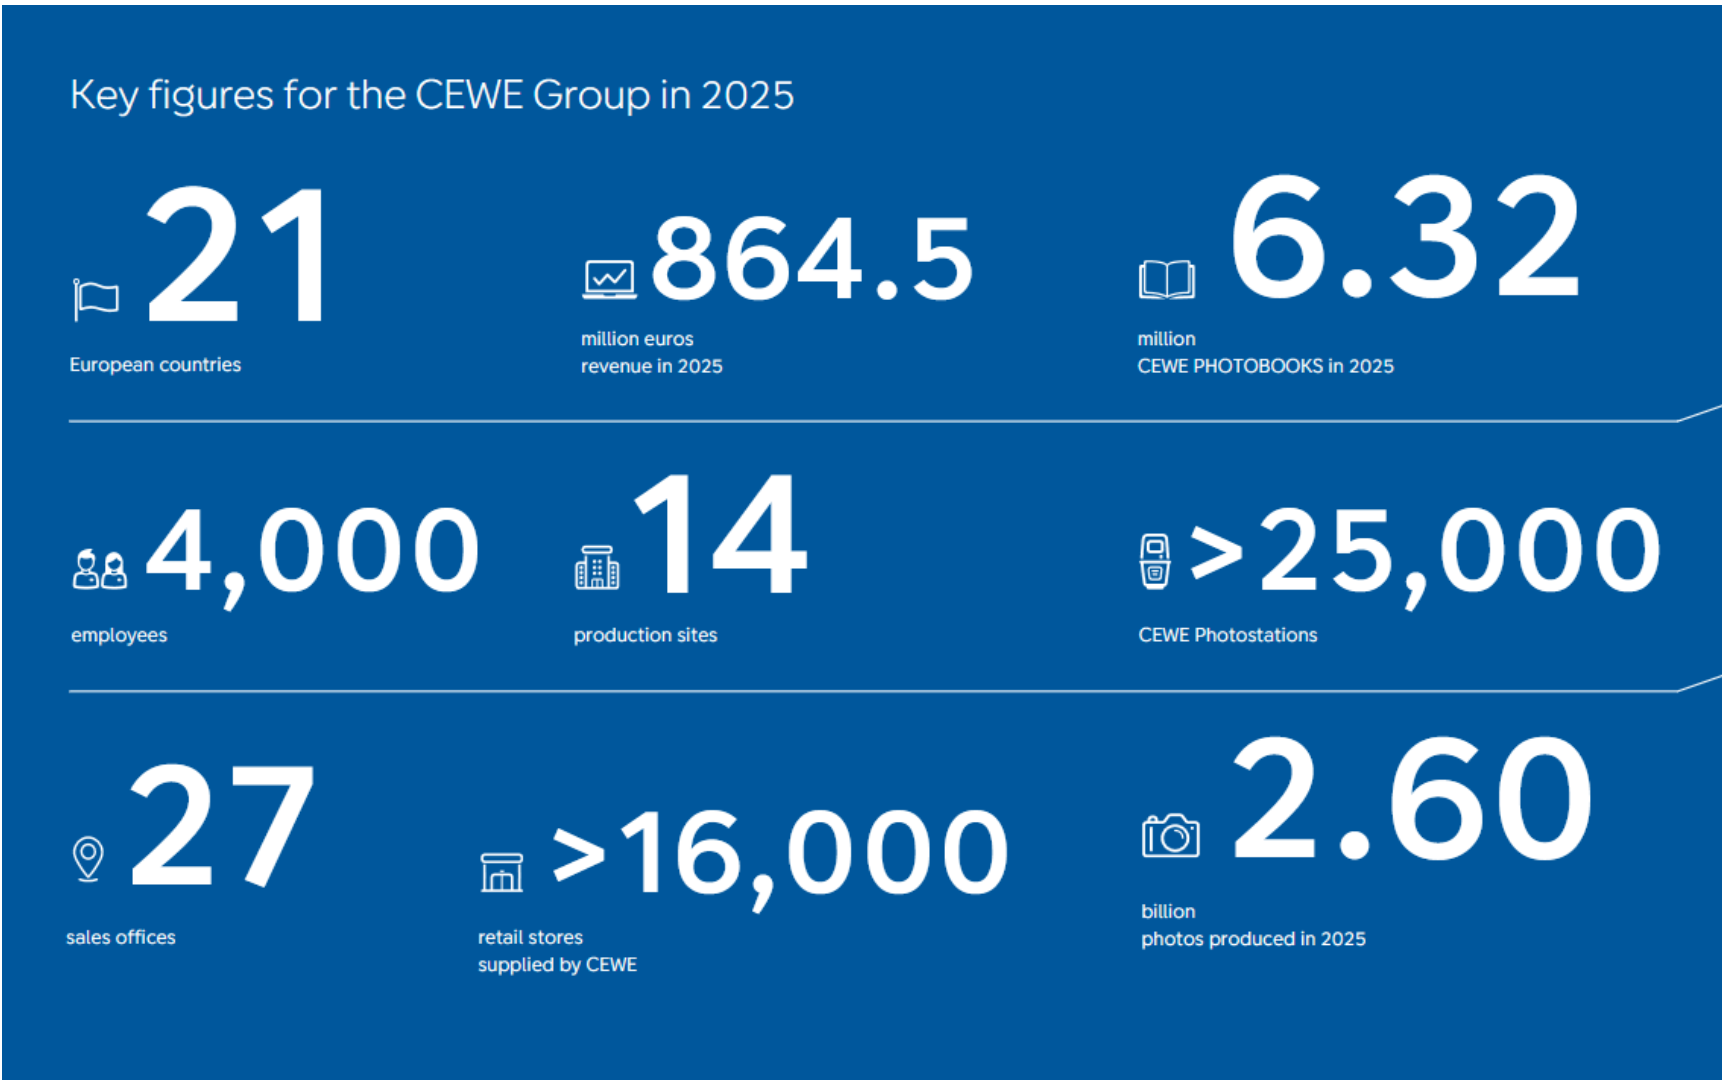
Here are some current highlights:

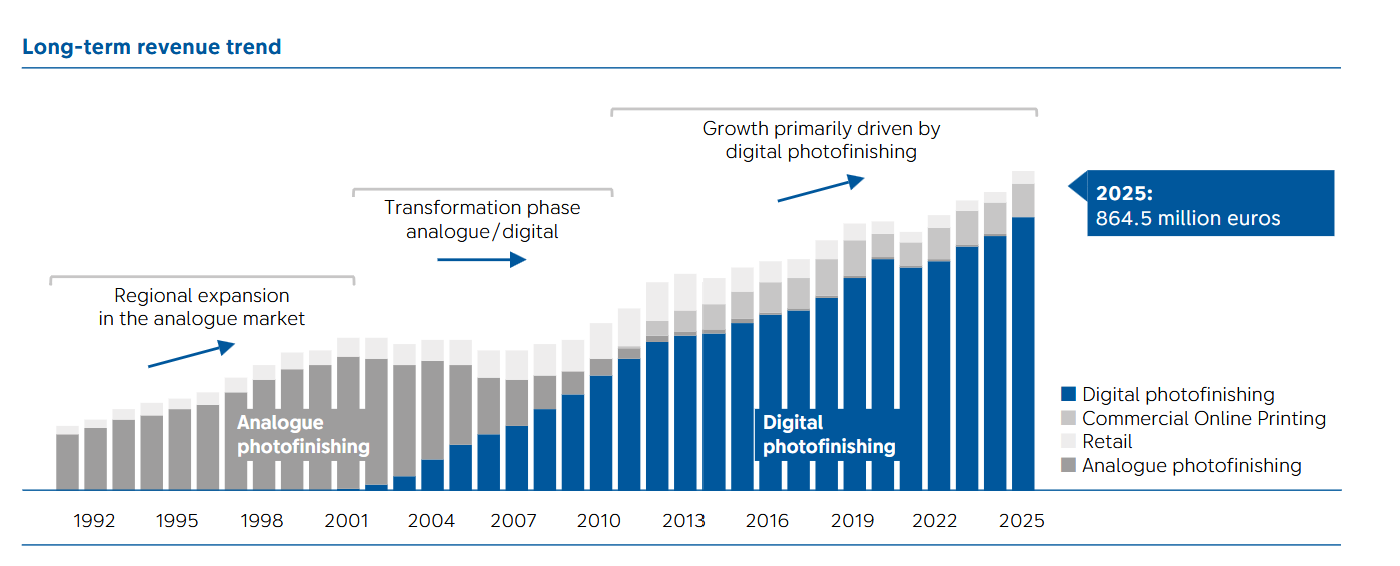
This chart from the annual report is very interesting which shows the transition from analogue to digital over the years:

When Wyser-Pratt “attacked” the company in 2007, only~50% of the business was digital, however that changed pretty rapidly.

From different sources, one gets an estimated market share for CEWE in Europe of ~30% and an estimated market share in Germany of >50%.

Recent developments: 

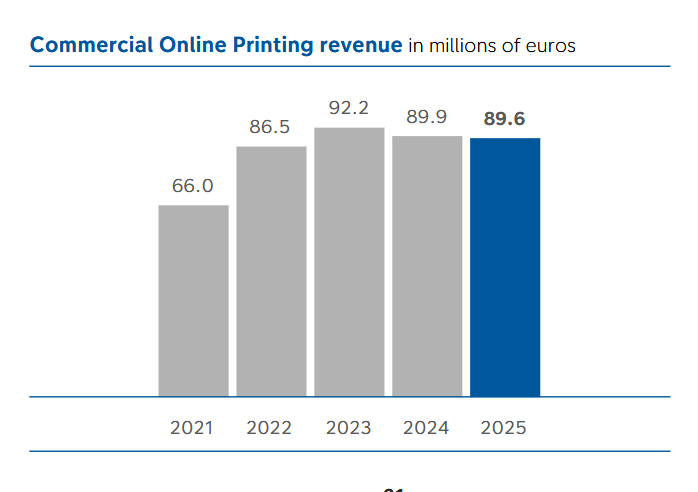
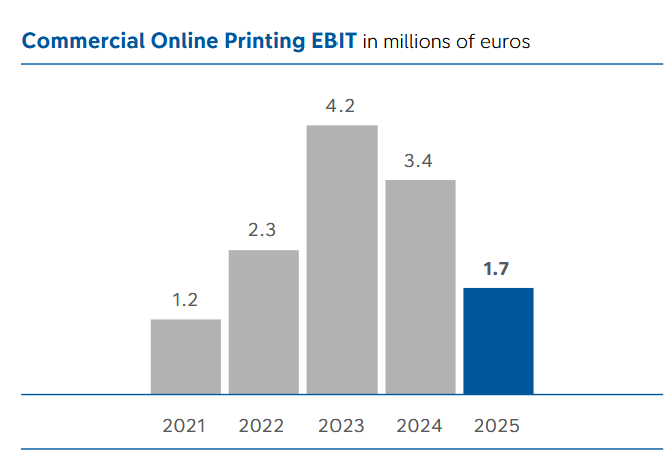
Sale of Commercial Online Printing division – This was actually very positive news: Cewe published in May that they were selling their struggling Commercial Online Printing division to Cimpress. 

This seems to result in an one-off gain of around 50 mn EUR.

As we see in the numbers, the division was barely profitable and not growing but represented 10% of total sales:

More or less at the same time, CEWE announced an acquisition: They are buying the Kodak Moments business which is basically very similar to their CEWE in-store kiosk business from a US PE fund,

This is what we know from Kodak Business:

Purchase price: 88 mn EUR (including debt)

Sales 200 mn EUR

EBIT margin “mid single digits” – lest assume 5%

That means CEWE paid an EV/EBIT 8,8x vs. 8.3x for CEWE itself. The seller seems to be an American Private Equity investor, who bought this business and another one from the bankrupt UK Kodak pension fund only 2  ago.

I found some information about the business from 2023 where it seems that 40% of the Kodak moments business seems to have been generated in Europe, 3% in the US and the rest in Australia and South America.

So CEWE sold ~2 mn in EBIT and acquired 11 mn EBIT, which seems like an OK deal. The big question s of course if and how fast they can bring the Kodak Moments business up to CEWE’s standards with double digit EBIT Margins.

The main risk that I see is that CEWE’s German Board (one exception) might struggle a bit with the non-European parts of the Kodak Moments business. I am also not 100% sure in what condition this business is after years of bankruptcy and 2 years of PE ownership.

General development

In general, looking at different sources, printing single photos still seems to be in a decline, while photo books seem to be growing, at least from a value perspective.. To my understanding, the acquired Kodak Moments business includes both.

Another question is at what stage, Agentic AI might be an issue for “branded” Photo book offerings. My feeling is that things move quickly, but I have no idea if and when this could be a threat.

Other aspects:

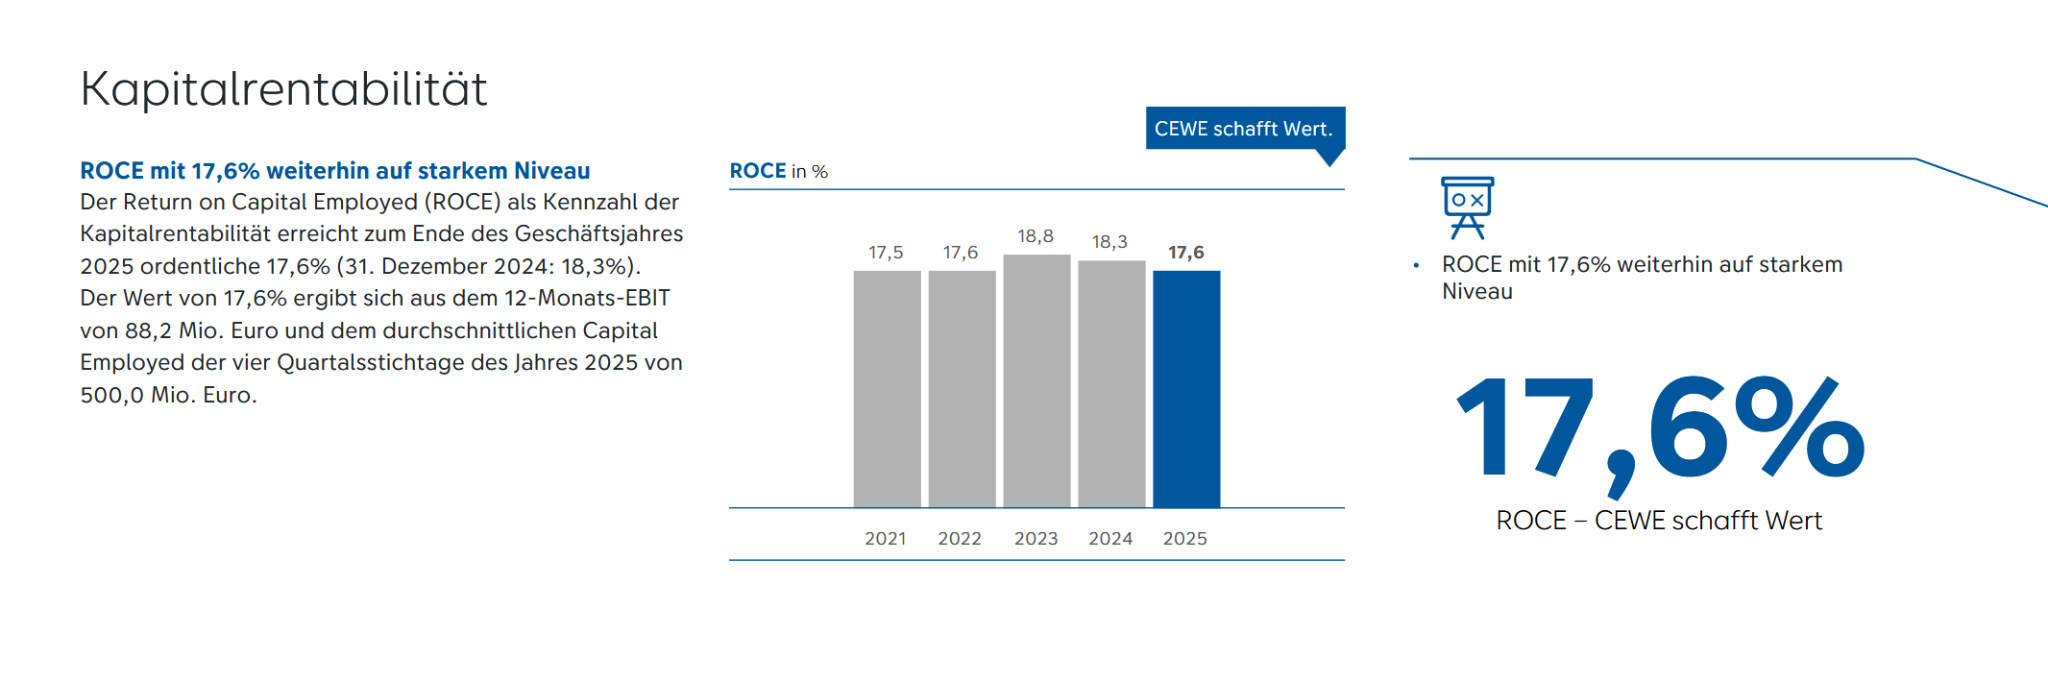
What I do like about CEWE is that they report ROCE which is rather unusual for a German small cap. ROCE numbers are pretty OK:

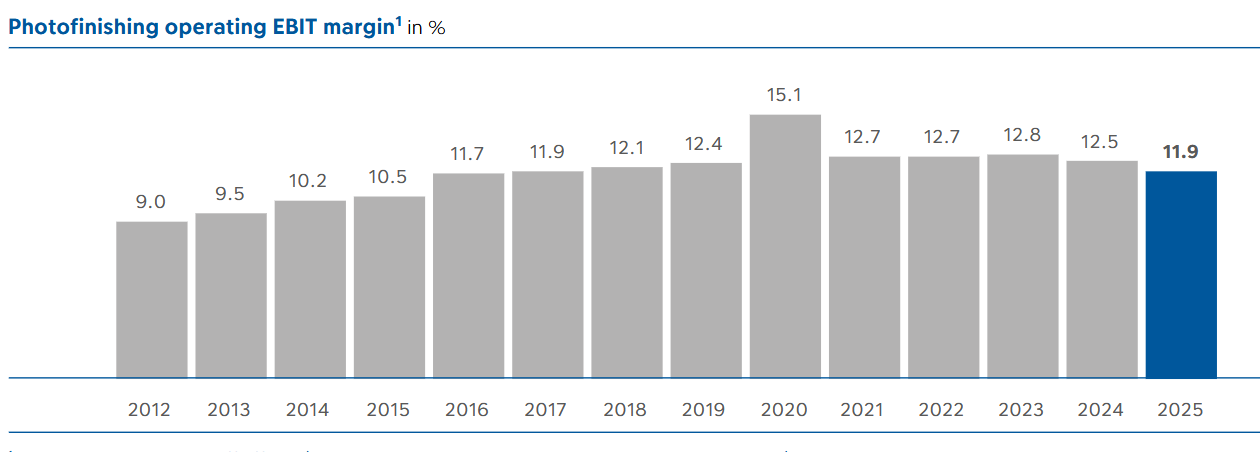
Ebit margins are double digit, however since the Covid Boom, they have been going down a little bit.

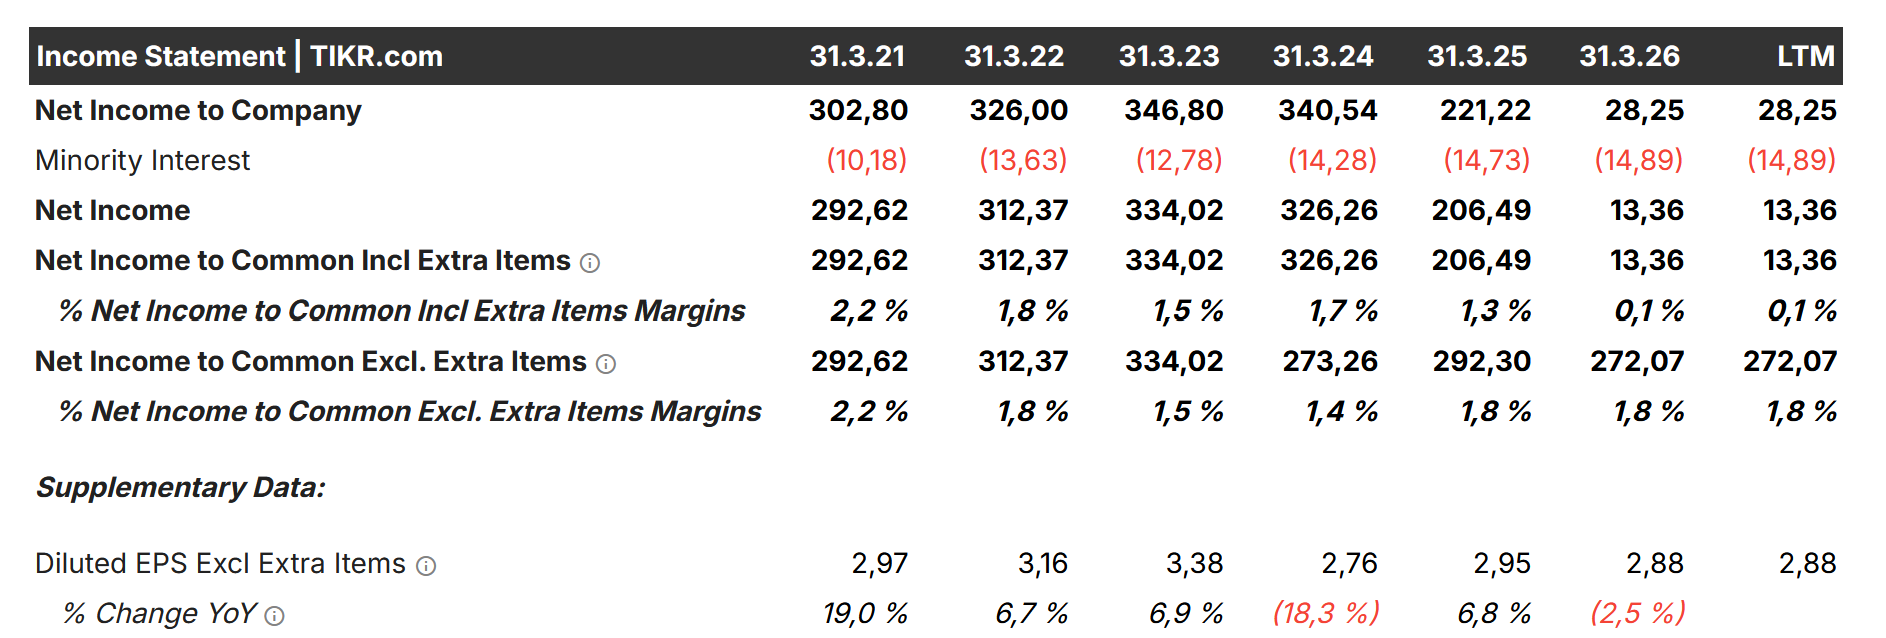
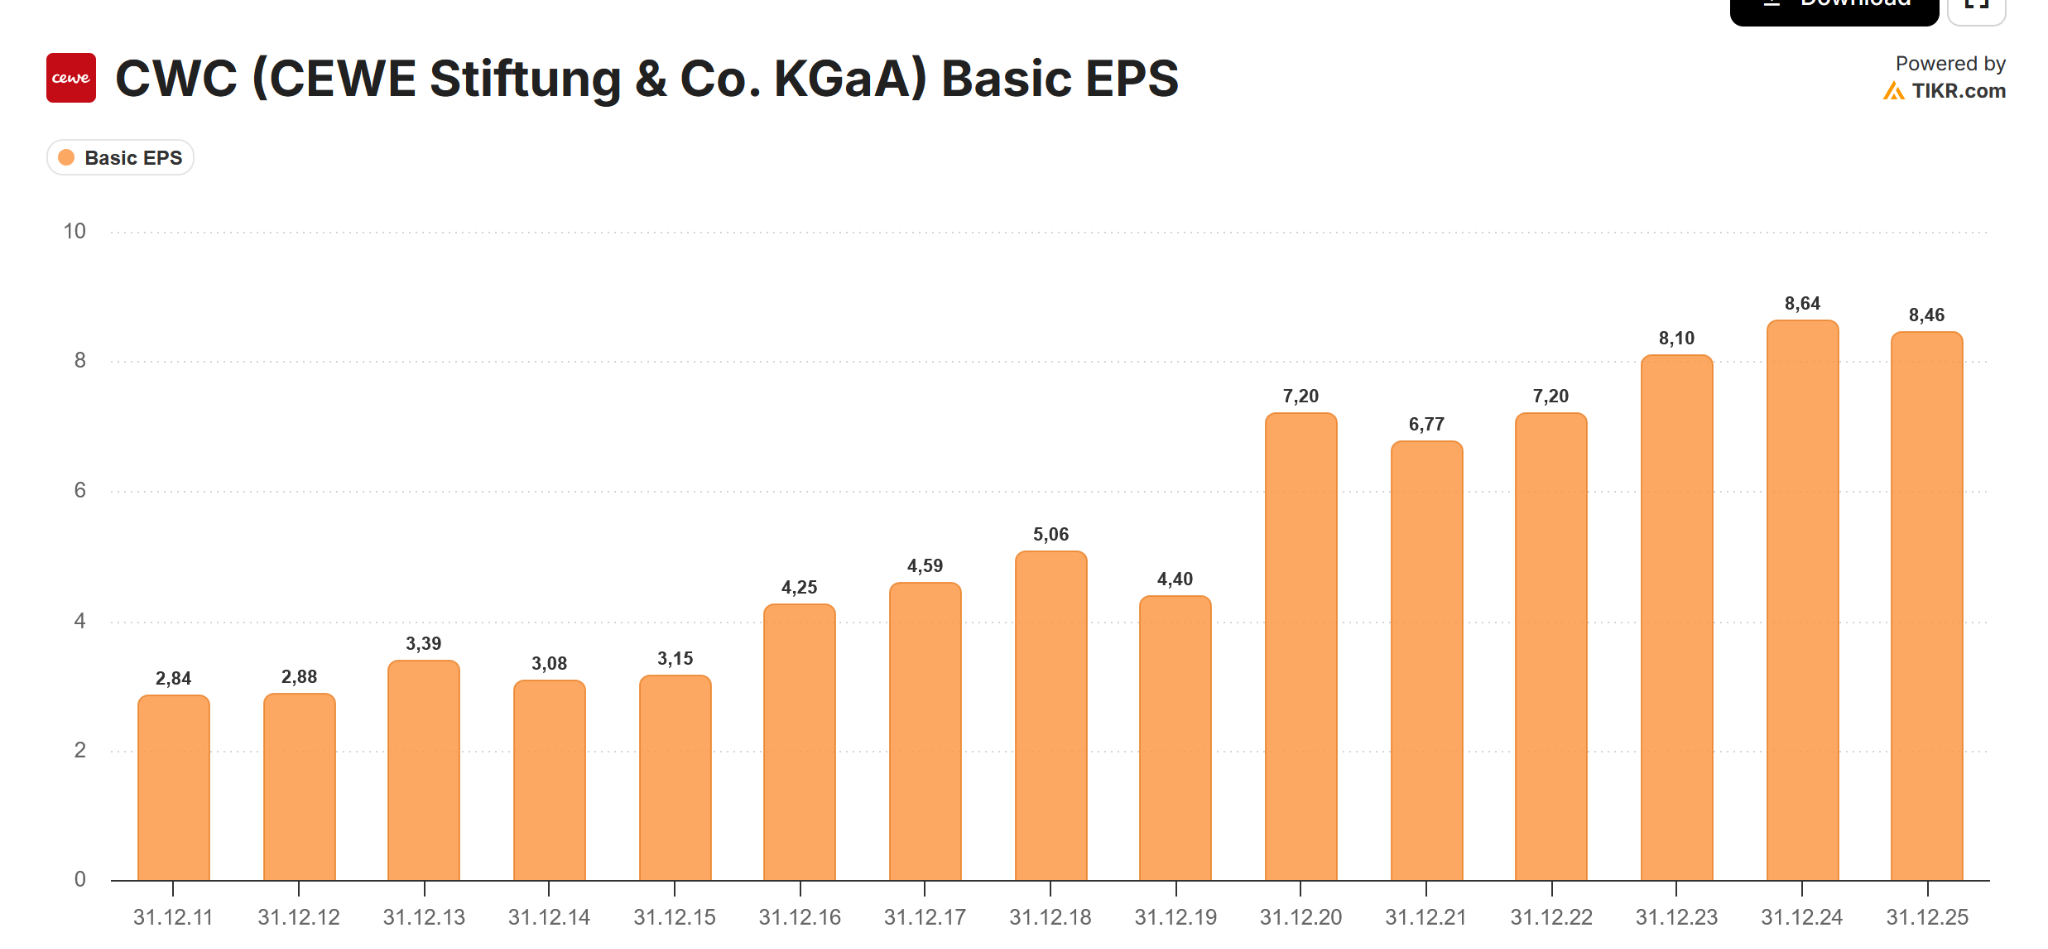
10 year EPS growth from 2015 to 2025 has been ~10,4% p.a. which is pretty impressive. However, since 2023, EPS was rather flatish. The main growth came in the years up to 2022.

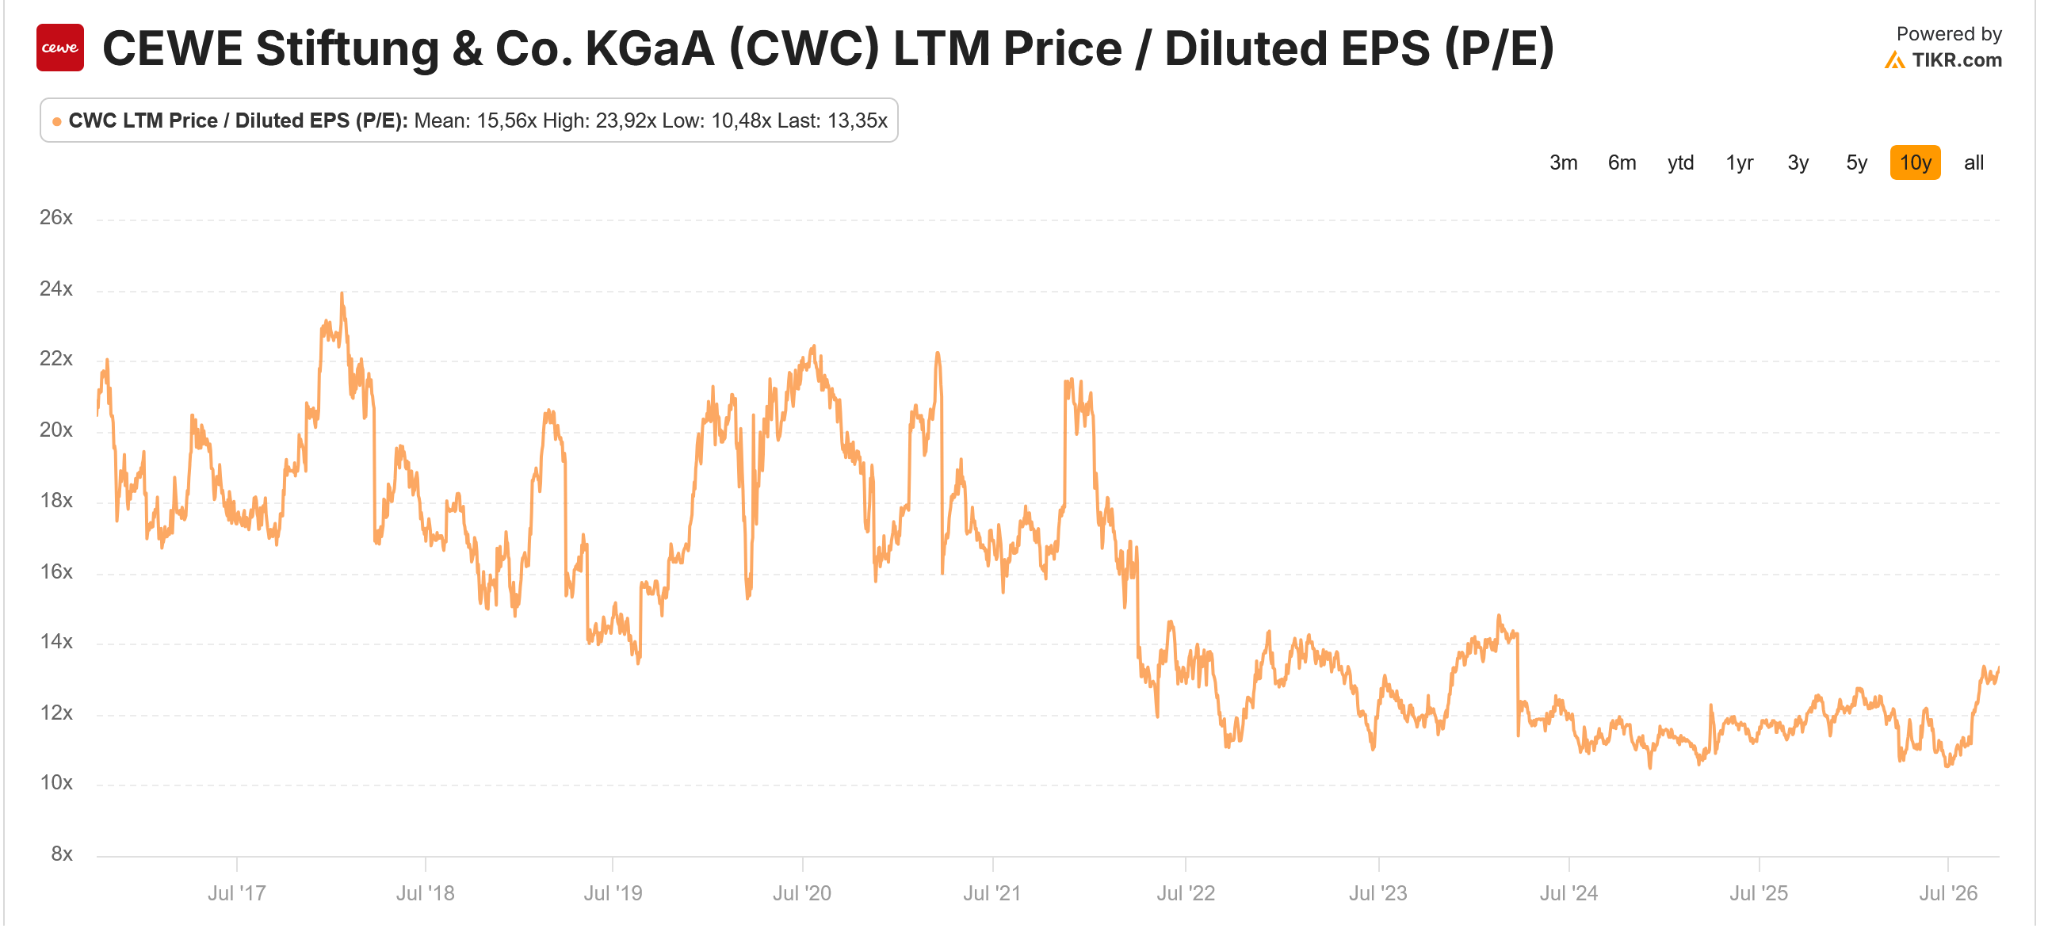
This is the EPS chart from Tikr:

Valuation & Share price:

Looking at the chart we can see that CEWE peaked during COVID and traded sideways until recently, underperforming both, SDAX and MDAX (before dividends)::

Recently the stock went up from the trading range as some market participants seem to see a better future.

Valuation wise, the stock is still relatively cheap.

Based on trailing 12M P/E, the stock trades at around 13x P/E vs. an average of 15x:

Pro’s & Con’s

  • still cheap
  • profitable
  • no debt
  • 3% dividend yield
  • sale of unprofitable division

+/- some share buy backs

  • low growth in the last 3 years
  • super seasonal business, all in Q4
  • KGAA Stiftung
  • EBIT margins creeping down
  • Kodak Moments acquisition risky
  • Large exposure to the German/European consumer

Intermediate conclusion

Although I kind of like CEWE, at this stage I don’t see myself investing into the stock on a 3-5 year horizon,

Yes, it’s cheap, quite profitable and the stock price has just trended upwards. On the other hand, I do see the risk that the recent acquisition might not go so smoothly and I am also not sure about growth prospects after that one time bump from the acquisition.

If I would be in the mood for shorter term trades, I might set up a 3-6 month trade trying to ride the current momentum, but the high interest rates make me nervous.

I also need to manage my exposure in the portfolio to the European consumer to which I am exposed directly and indirectly through stocks like Sixt, Fielmann, Thermador, Italmobiliare etc.

Therefore, for the time being, I am not investing into CEWE but keep it on the watch list.Upfront remarks & Management summary:

This is not a deep dive but more like my “first round screening” of a potential interesting investment. In the past, I would have not necessarily published it if I didn’t invest. Going forward, I will now and then publish these “initial assessments” mainly in order to receive feedback from readers who might see it differently. So please give feedback if you see things different !!!

As a Management Summary, I did not invest. Although I like the company somehow, I could not build up the conviction for a 3-5 year investment case mainly due to recent slow growth and a somewhat risky acquisition. 

Some links 25/2026

Great deep dive into Software Serial Acquirer Vitec from the Slow Compounding Substack

A nice collection of 26 different UK stock ideas from the “British Alpha” Substack

A great story on the history of the Bloomberg Terminal

Latticework with a quite contrarian pitch on Nike

The Value don’t lie Substack with a good summary of what to look for (and avoid) when investing into turn-arounds

Already a few weeks ago, the Hidden Value Research Substack had a decent write-up on CTS Eventim

A very reflected travel report from a Japanese Investor visiting the US & Canada