CEWE KGaA – Good company but not a “Buy” yet ?
Upfront remarks & Management summary:
This is not a deep dive but more like my typical “first round screening” of a potential interesting investment. In the past, I would have not necessarily published it if I didn’t invest. Going forward, I will now and then publish these “initial assessments” mainly in order to receive feedback from readers who might see it differently. So please give feedback if you see things different !!!
As a Management Summary, I did not invest. Although I like the company, I could not build up the conviction for a 3-5 year investment case mainly due to recent slow growth and a somewhat risky acquisition.
Company History:
Cewe Color traces its roots back to 1912 to a photo finishing lab in the Northern German town Oldenburg. And that’s what they did for the next ~100 years: “finishing” or “developing” Fotos from films that were given or sent to them. For the (few) younger readers: In the old days, there were real photo cameras where you took the pictures on a rol of film and you could only look at the pictures after they came back from the phot finishing lab.
In 1951 they introduced color pictures, 1994 they started to develop digital pictures and in 2025 they introduced the category that is today’s most relevant: The photo book.
in 2007/2008, CEWE became the target of US activist Guy Wyser-Pratte, who wanted CEWE to speed up its transformation into a digital player. However, in 2008, the activists lost interest.
As a consequence of this “activist attack”, CEWE changed into a KGaA structure in 2013, which makes it factually impossible to take over the company as the listed shares are effectively only non-voting shares.
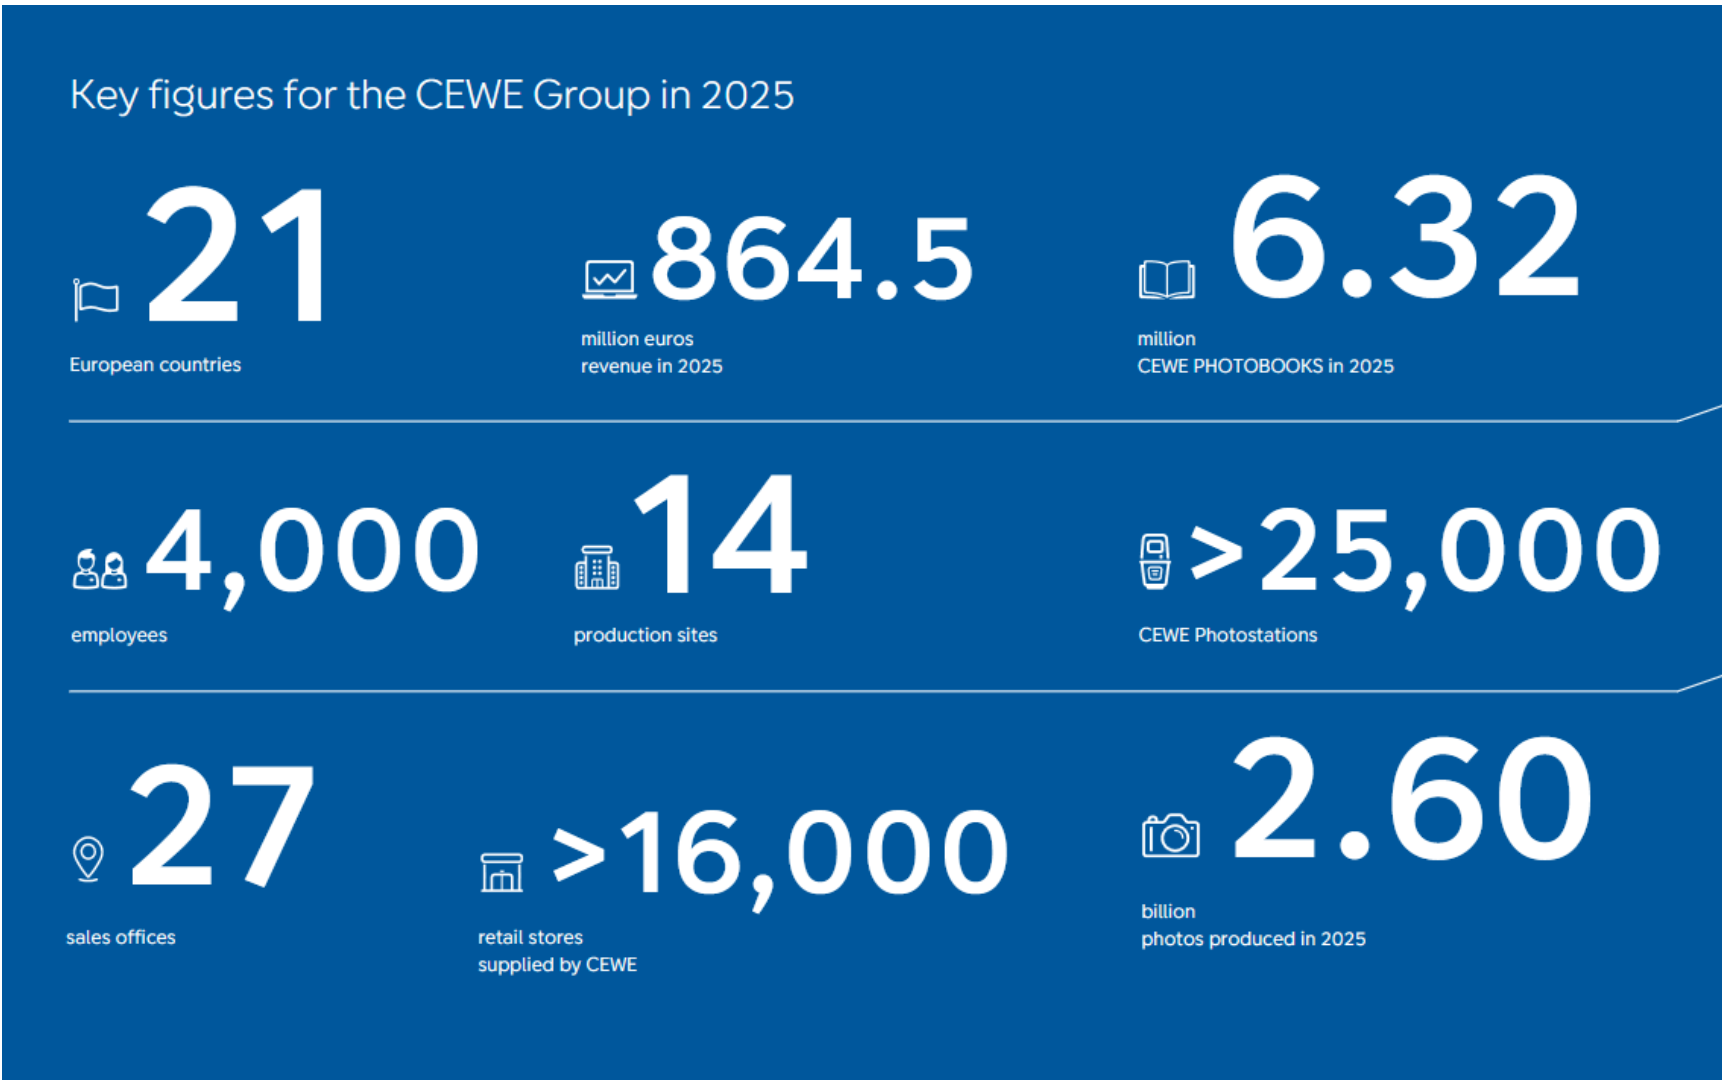
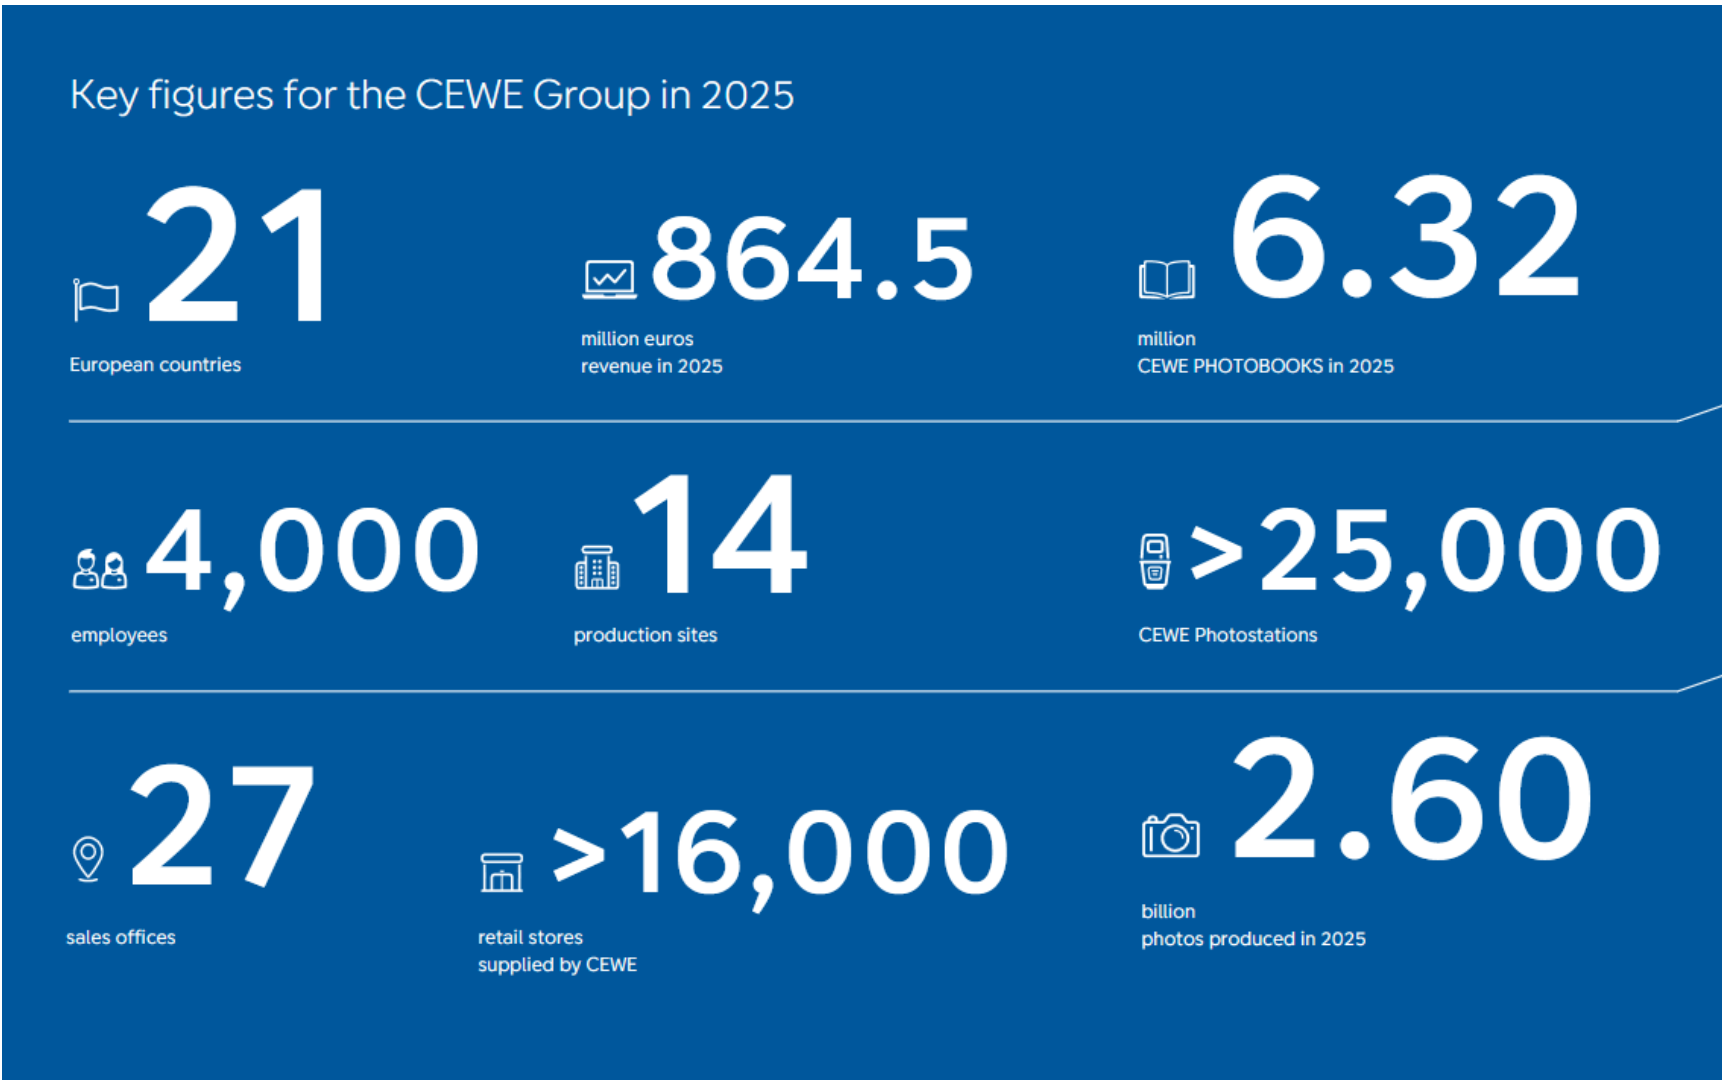
Here are some current highlights:
This chart from the annual report is very interesting which shows the transition from analogue to digital over the years:
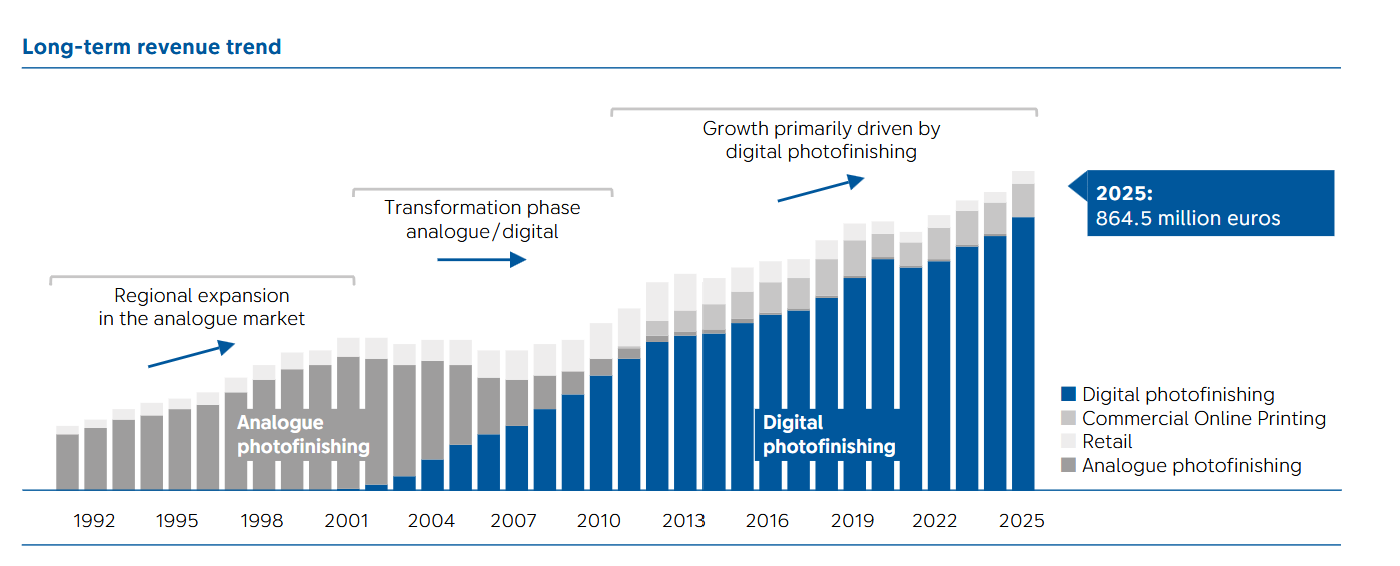
When Wyser-Pratt “attacked” the company in 2007, only~50% of the business was digital, however that changed pretty rapidly.
From different sources, one gets an estimated market share for CEWE in Europe of ~30% and an estimated market share in Germany of >50%.
Recent developments:
Sale of Commercial Online Printing division – This was actually very positive news: Cewe published in May that they were selling their struggling Commercial Online Printing division to Cimpress.
This seems to result in an one-off gain of around 50 mn EUR.
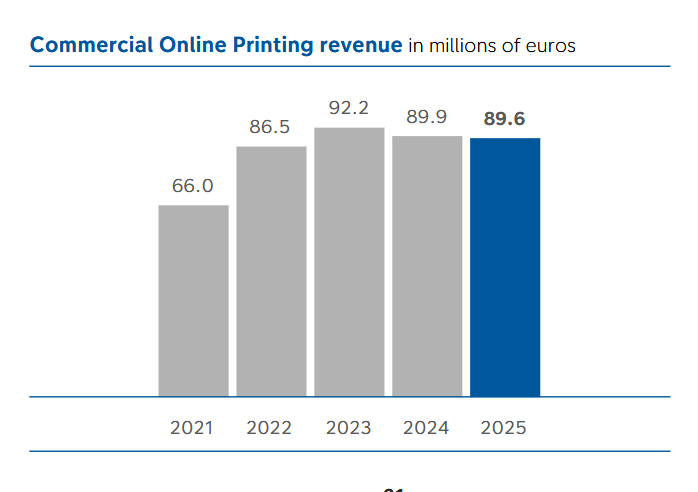
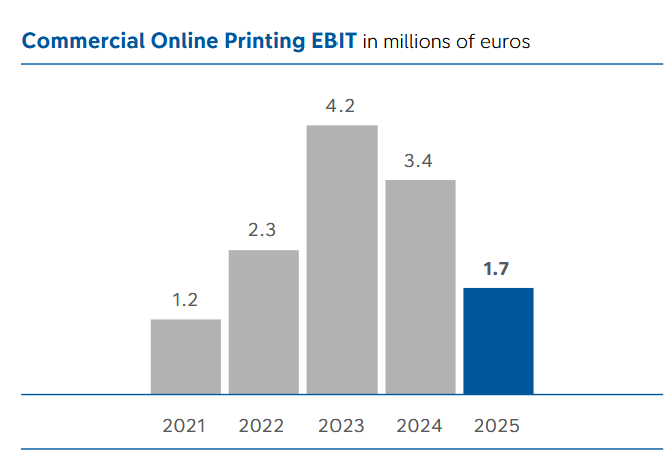
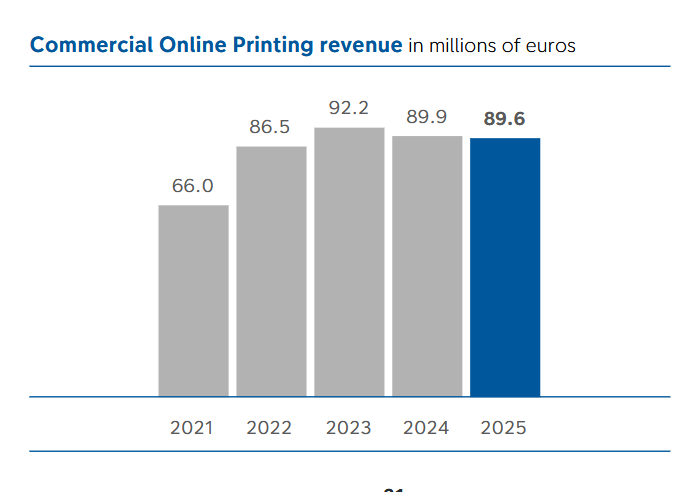
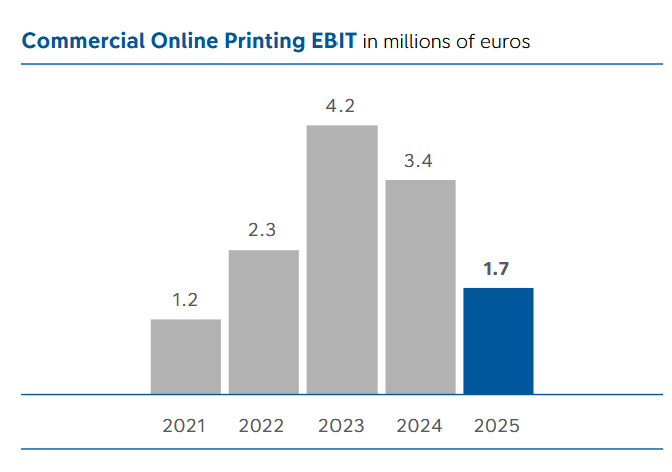
As we see in the numbers, the division was barely profitable and not growing but represented 10% of total sales:
More or less at the same time, CEWE announced an acquisition: They are buying the Kodak Moments business which is basically very similar to their CEWE in-store kiosk business from a US PE fund,
This is what we know from Kodak Business:
Purchase price: 88 mn EUR (including debt)
Sales 200 mn EUR
EBIT margin “mid single digits” – lest assume 5%
That means CEWE paid an EV/EBIT 8,8x vs. 8.3x for CEWE itself. The seller seems to be an American Private Equity investor, who bought this business and another one from the bankrupt UK Kodak pension fund only 2 ago.
I found some information about the business from 2023 where it seems that 40% of the Kodak moments business seems to have been generated in Europe, 3% in the US and the rest in Australia and South America.
So CEWE sold ~2 mn in EBIT and acquired 11 mn EBIT, which seems like an OK deal. The big question s of course if and how fast they can bring the Kodak Moments business up to CEWE’s standards with double digit EBIT Margins.
The main risk that I see is that CEWE’s German Board (one exception) might struggle a bit with the non-European parts of the Kodak Moments business. I am also not 100% sure in what condition this business is after years of bankruptcy and 2 years of PE ownership.
General development
In general, looking at different sources, printing single photos still seems to be in a decline, while photo books seem to be growing, at least from a value perspective.. To my understanding, the acquired Kodak Moments business includes both.
Another question is at what stage, Agentic AI might be an issue for “branded” Photo book offerings. My feeling is that things move quickly, but I have no idea if and when this could be a threat.
Other aspects:
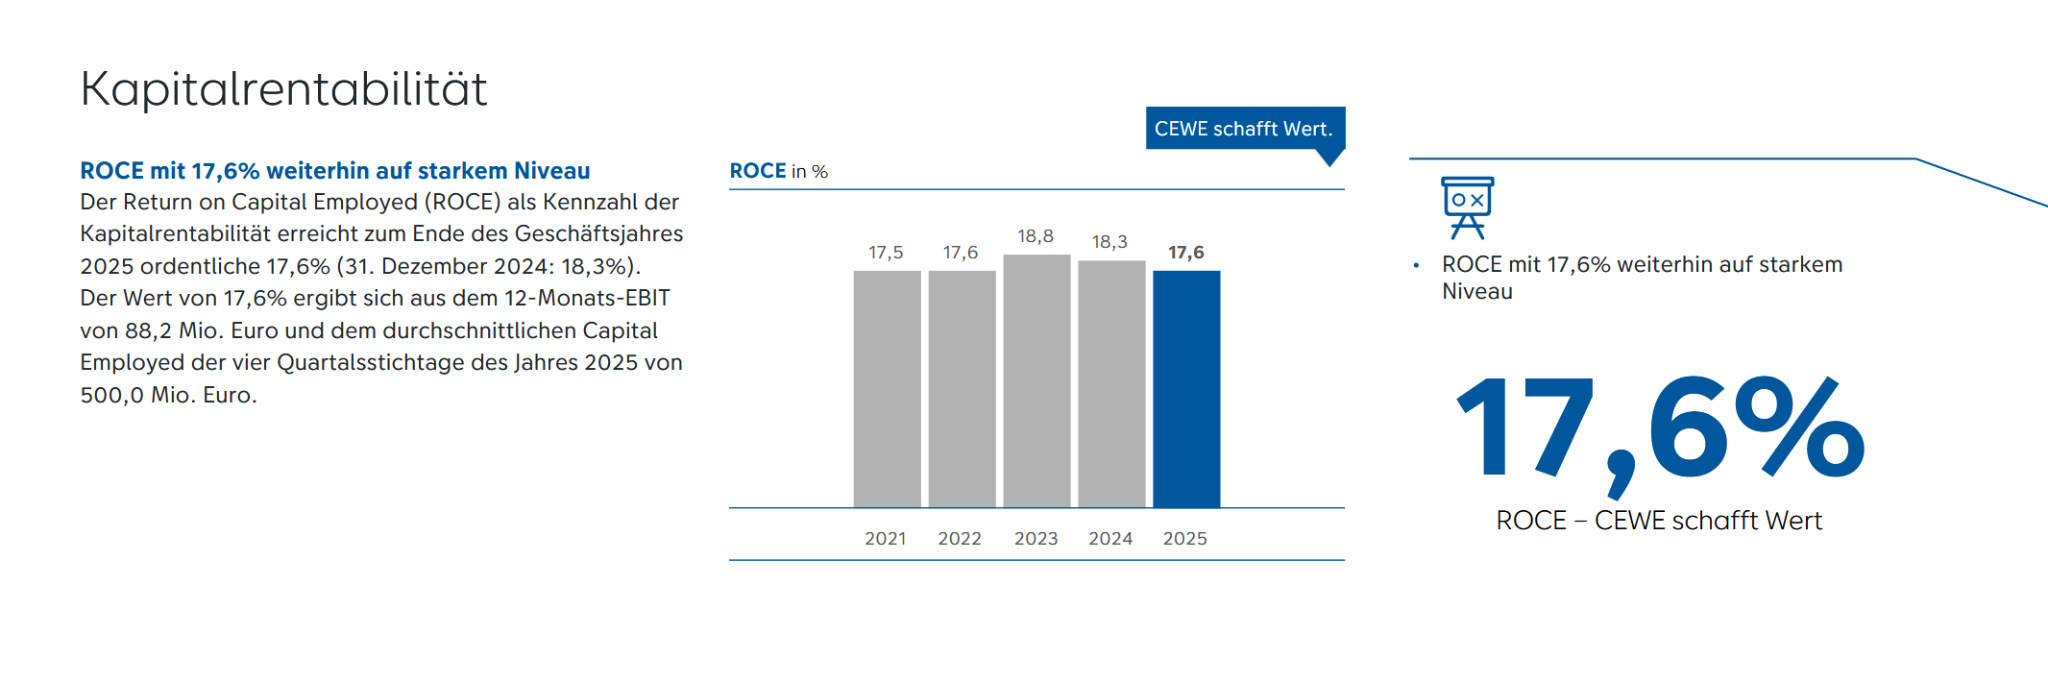
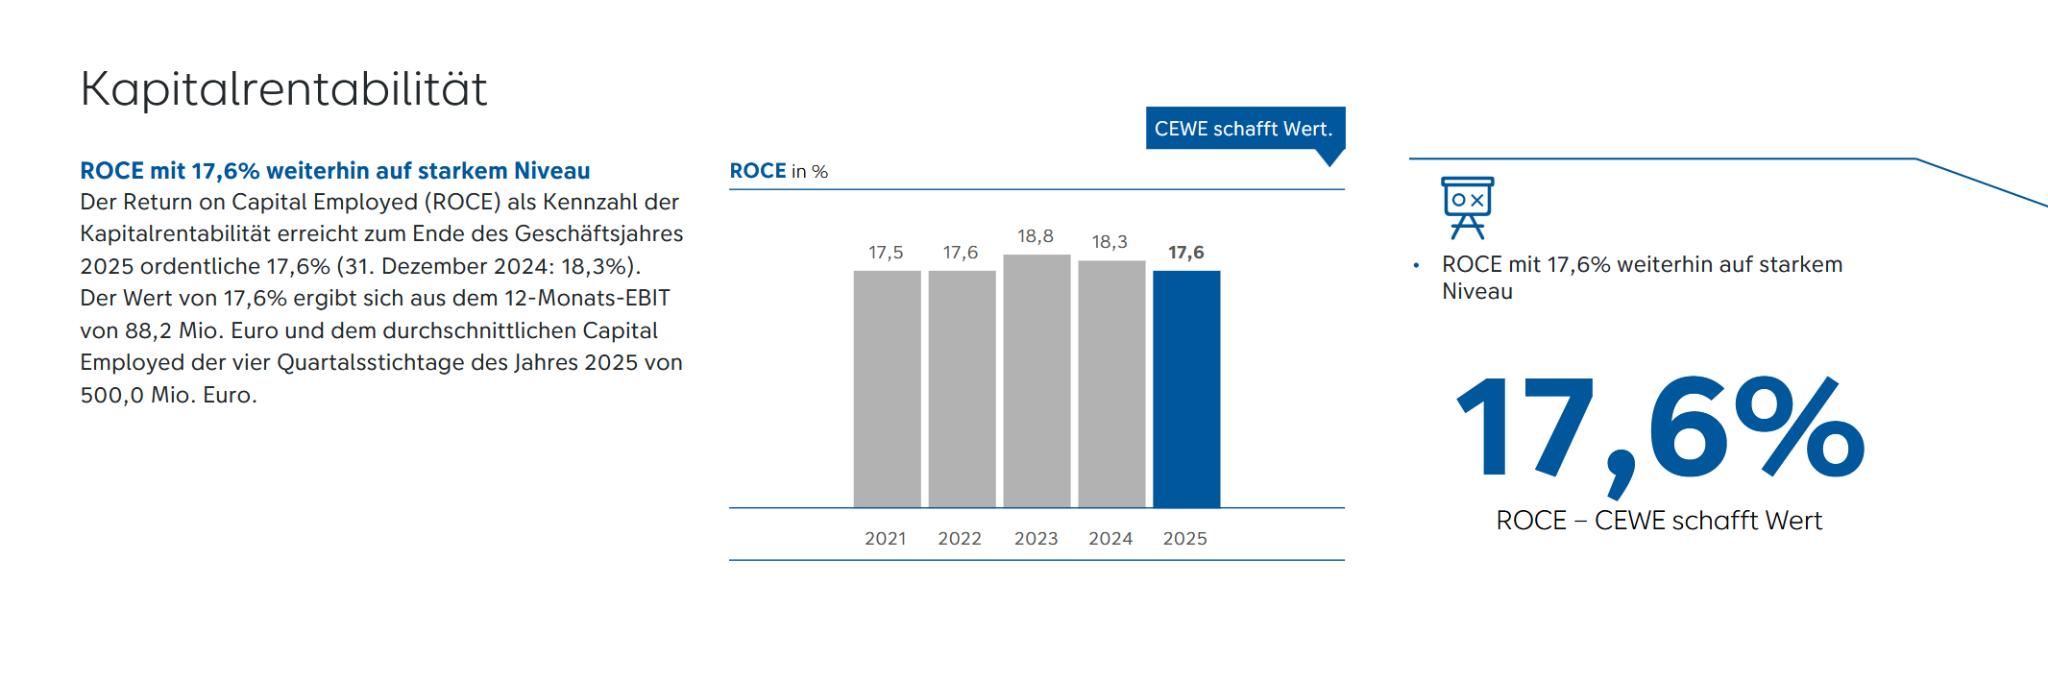
What I do like about CEWE is that they report ROCE which is rather unusual for a German small cap. ROCE numbers are pretty OK:
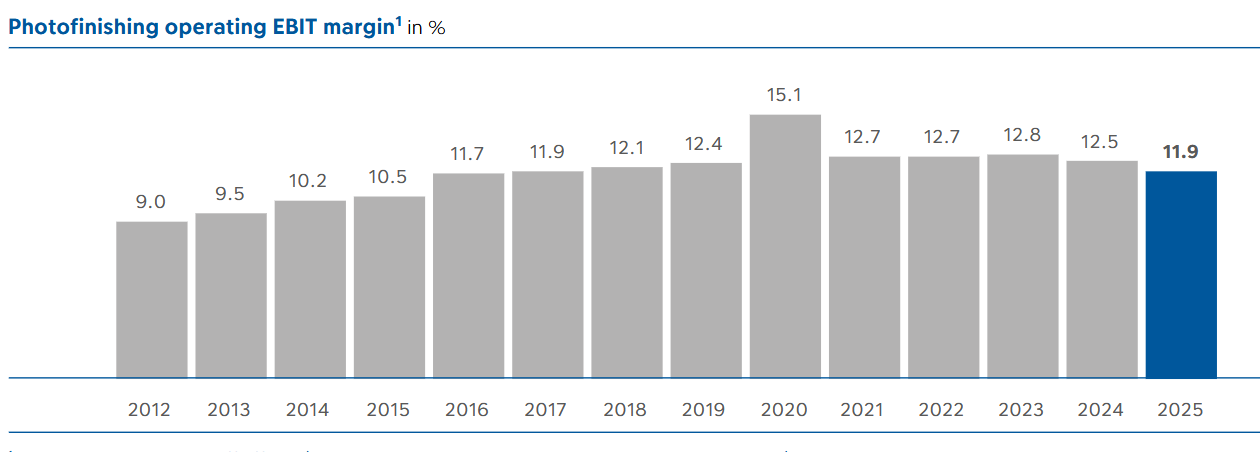
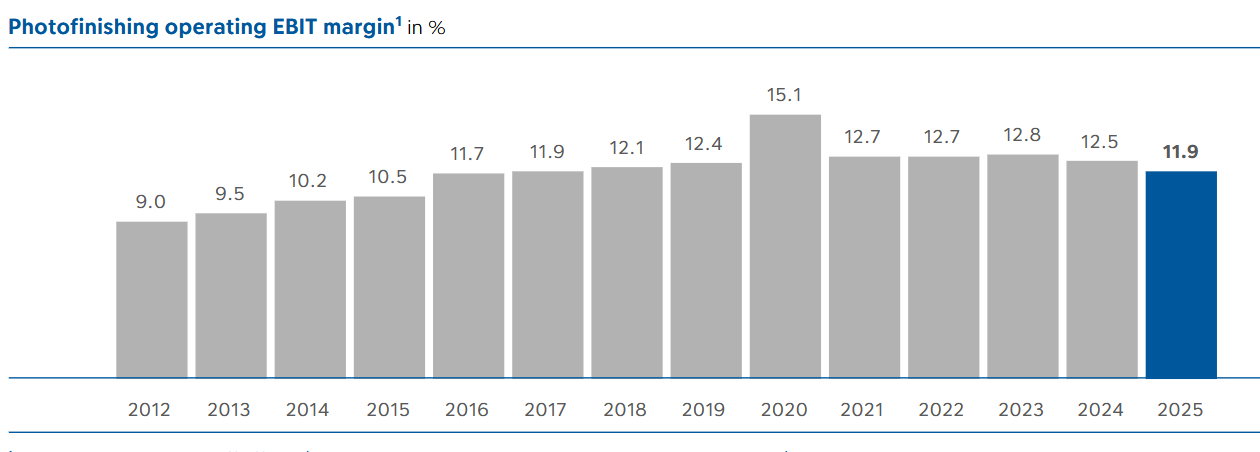
Ebit margins are double digit, however since the Covid Boom, they have been going down a little bit.
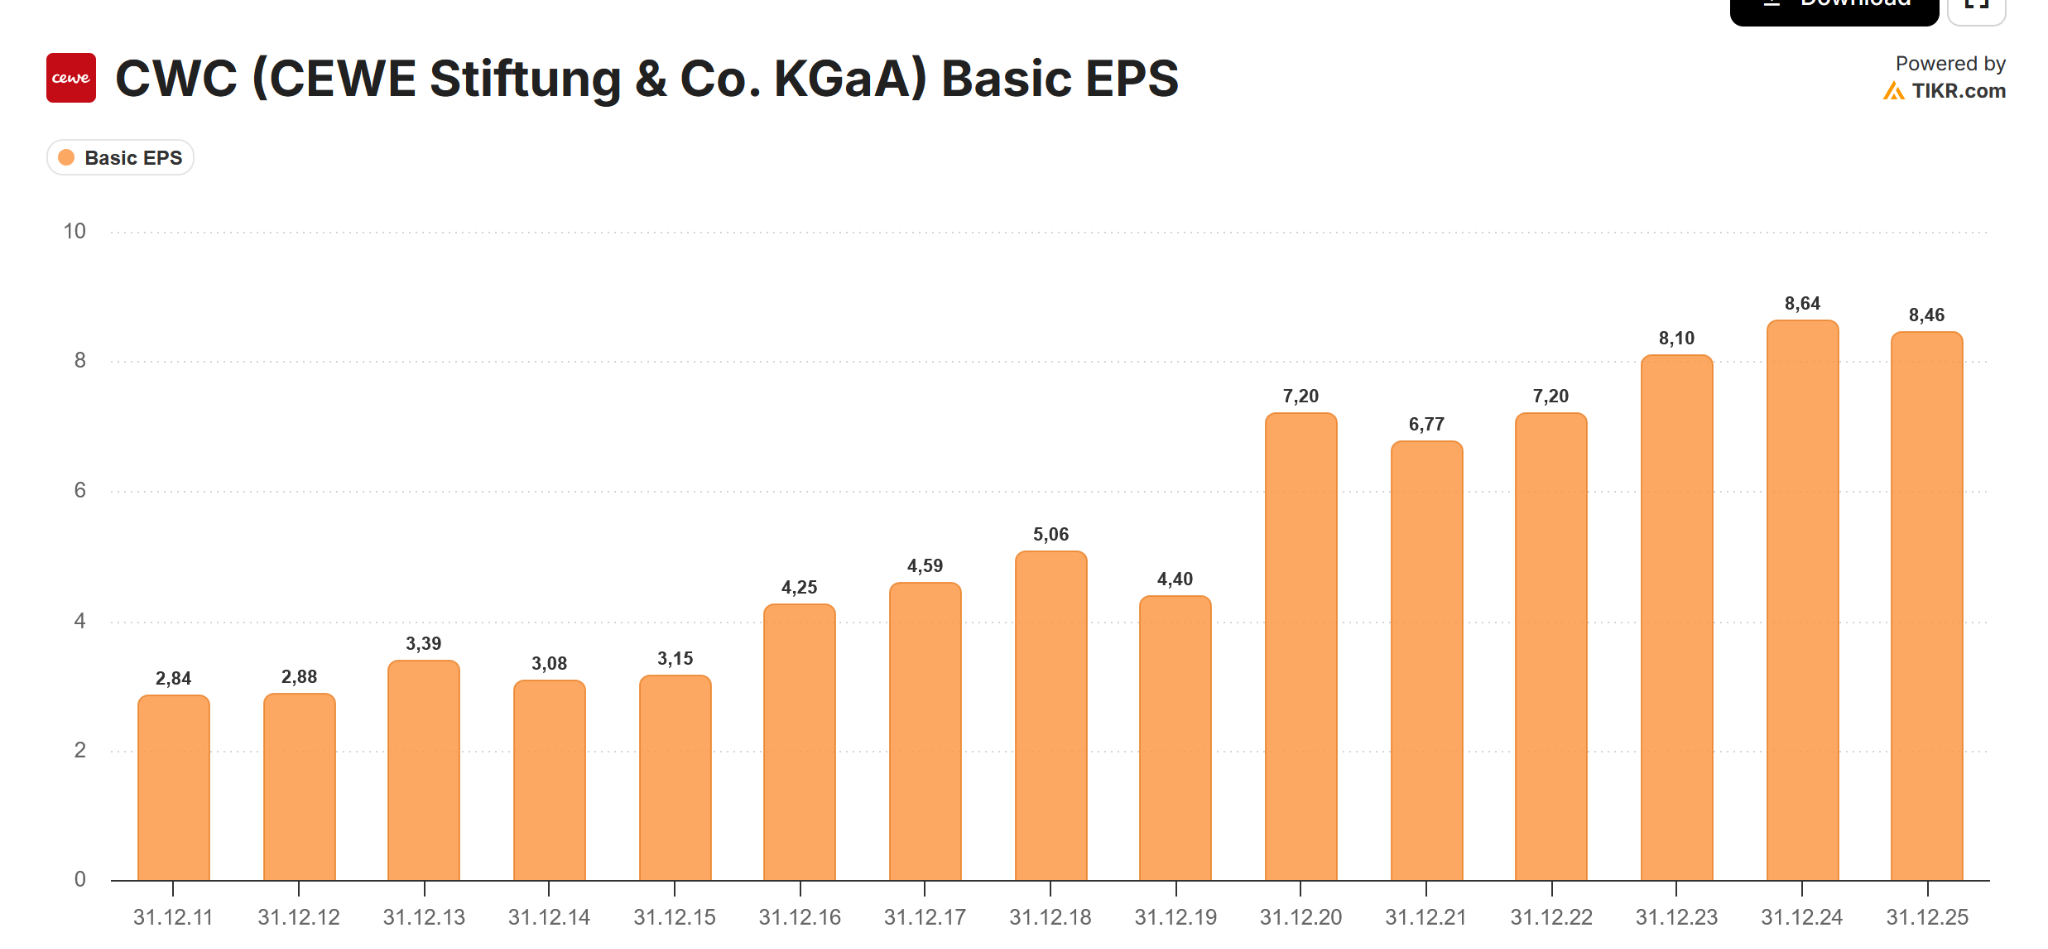
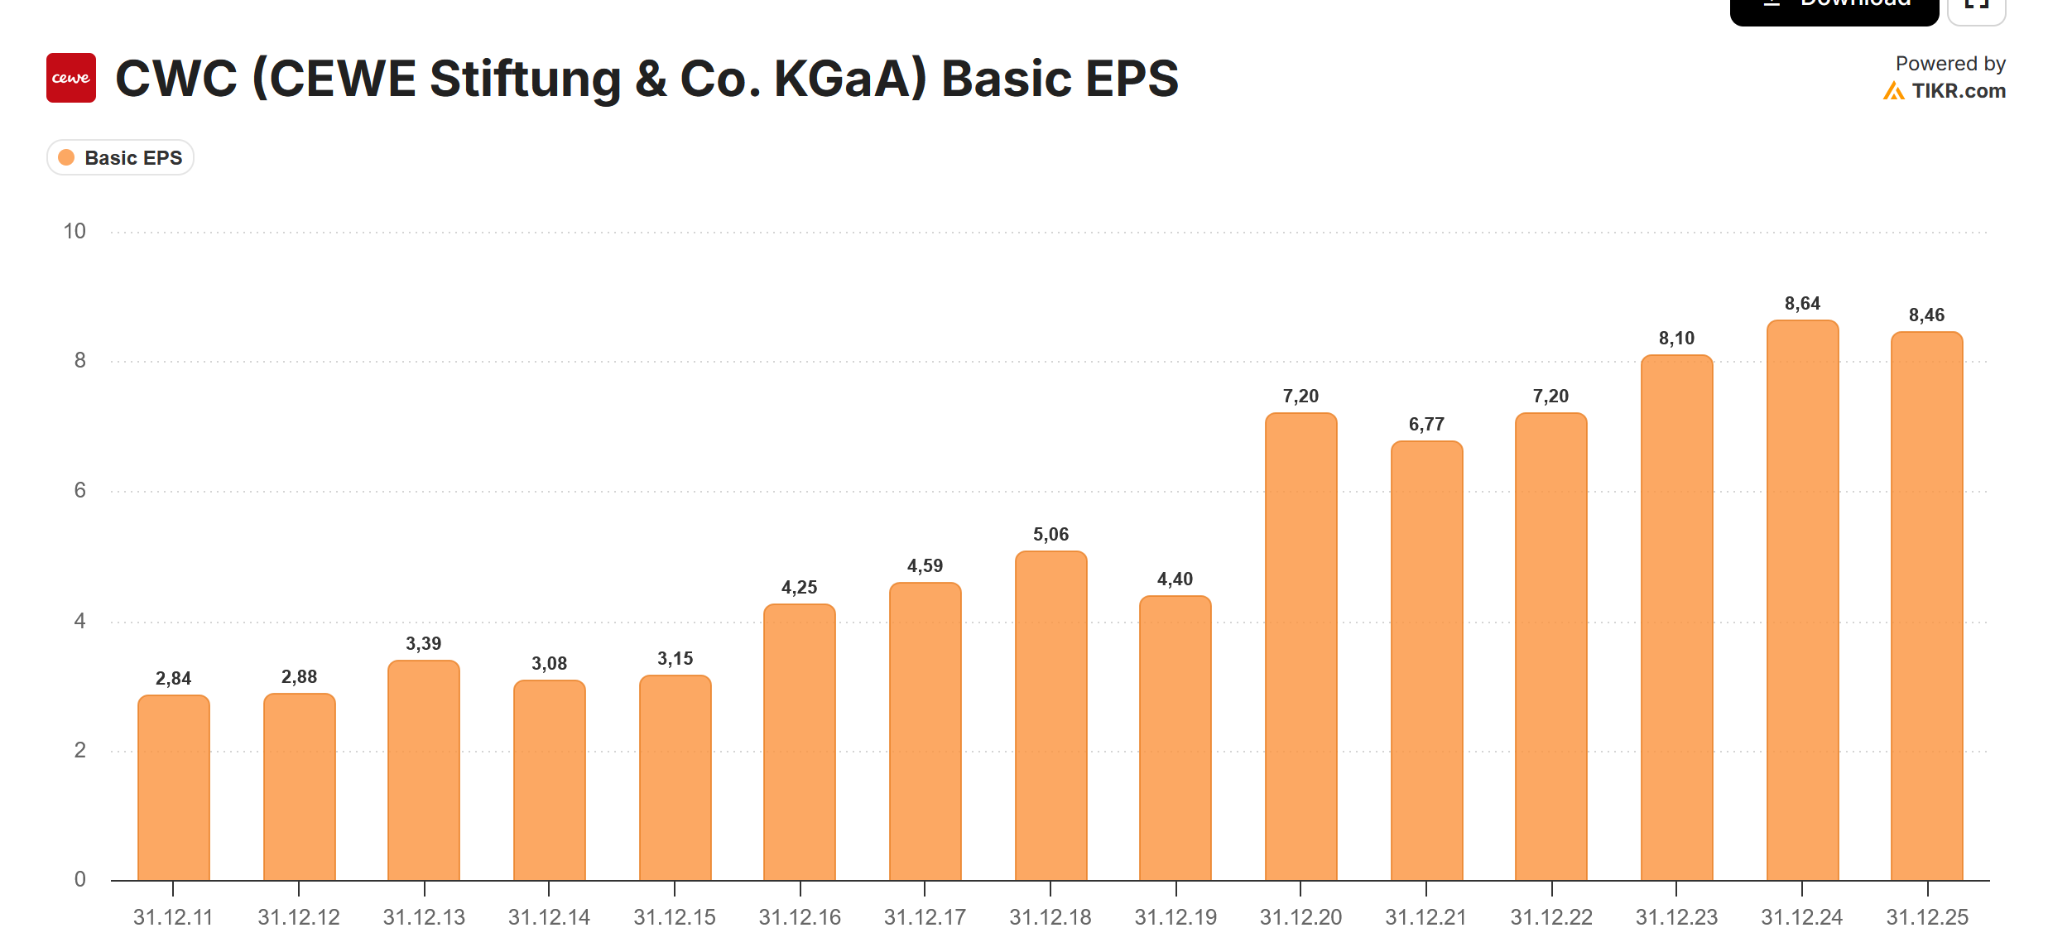
10 year EPS growth from 2015 to 2025 has been ~10,4% p.a. which is pretty impressive. However, since 2023, EPS was rather flatish. The main growth came in the years up to 2022.
This is the EPS chart from Tikr:
Valuation & Share price:
Looking at the chart we can see that CEWE peaked during COVID and traded sideways until recently, underperforming both, SDAX and MDAX (before dividends)::
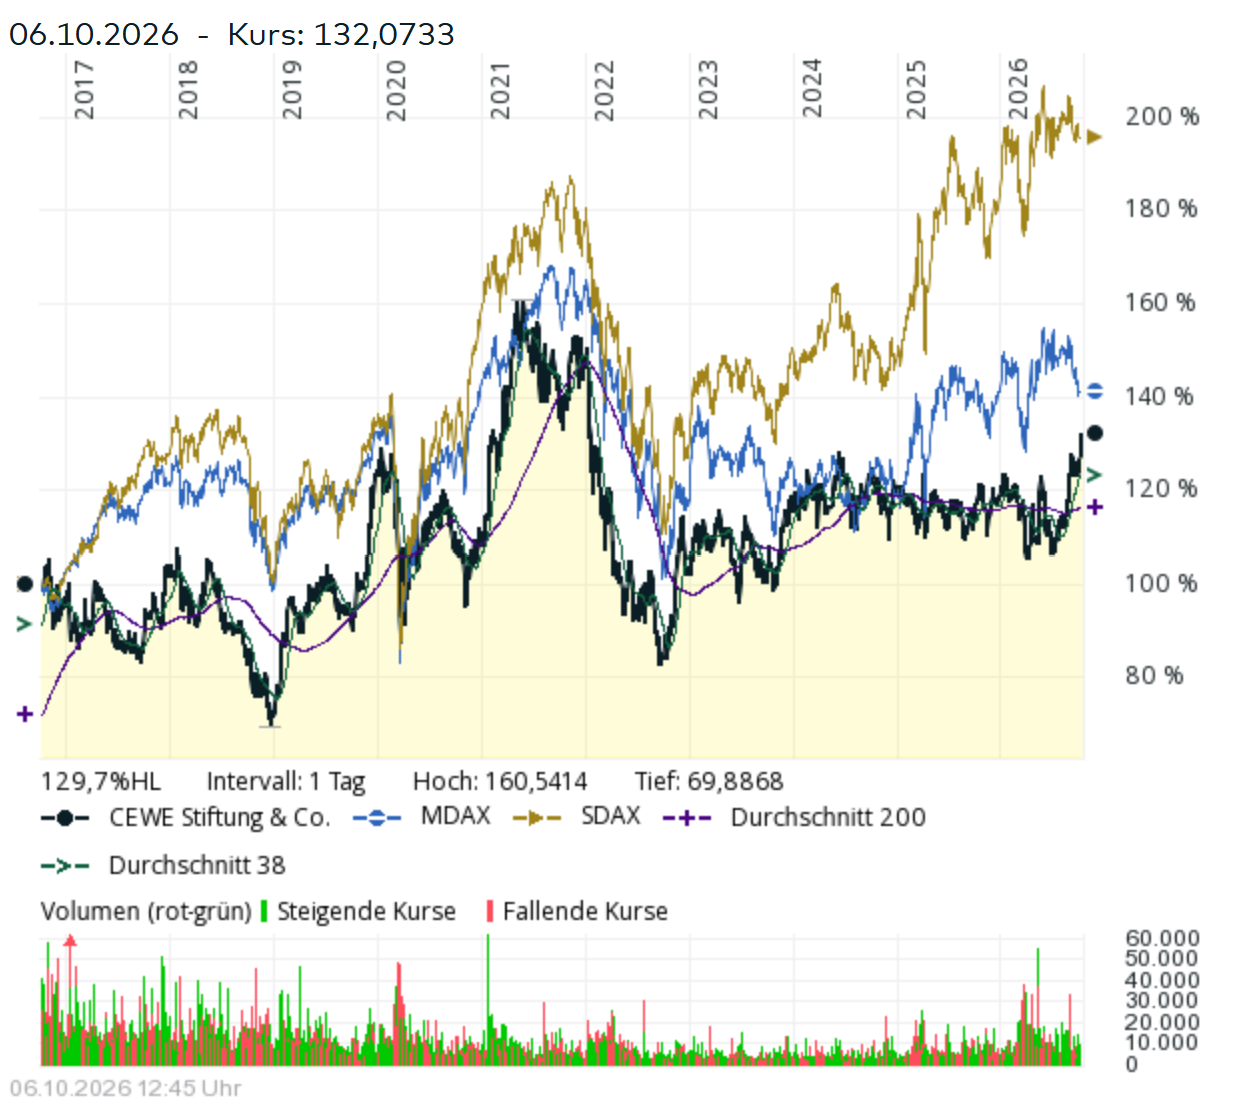
Recently the stock went up from the trading range as some market participants seem to see a better future.
Valuation wise, the stock is still relatively cheap.
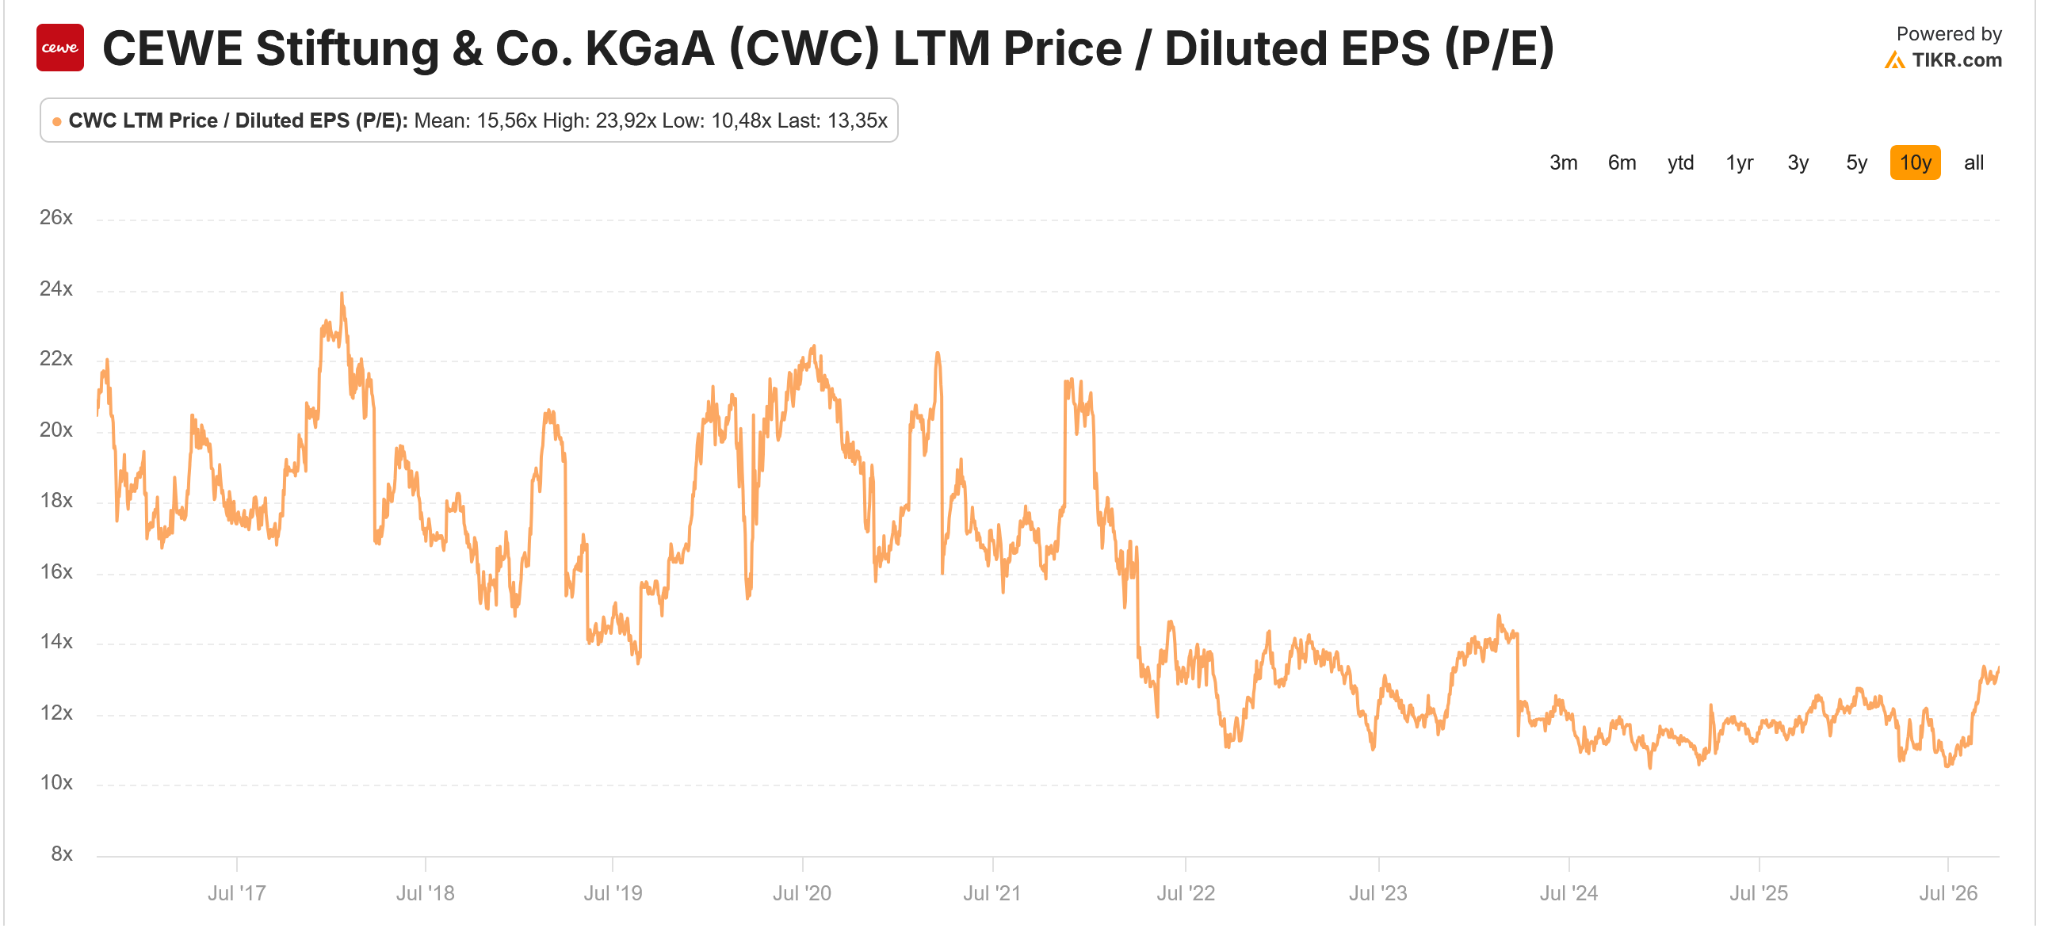
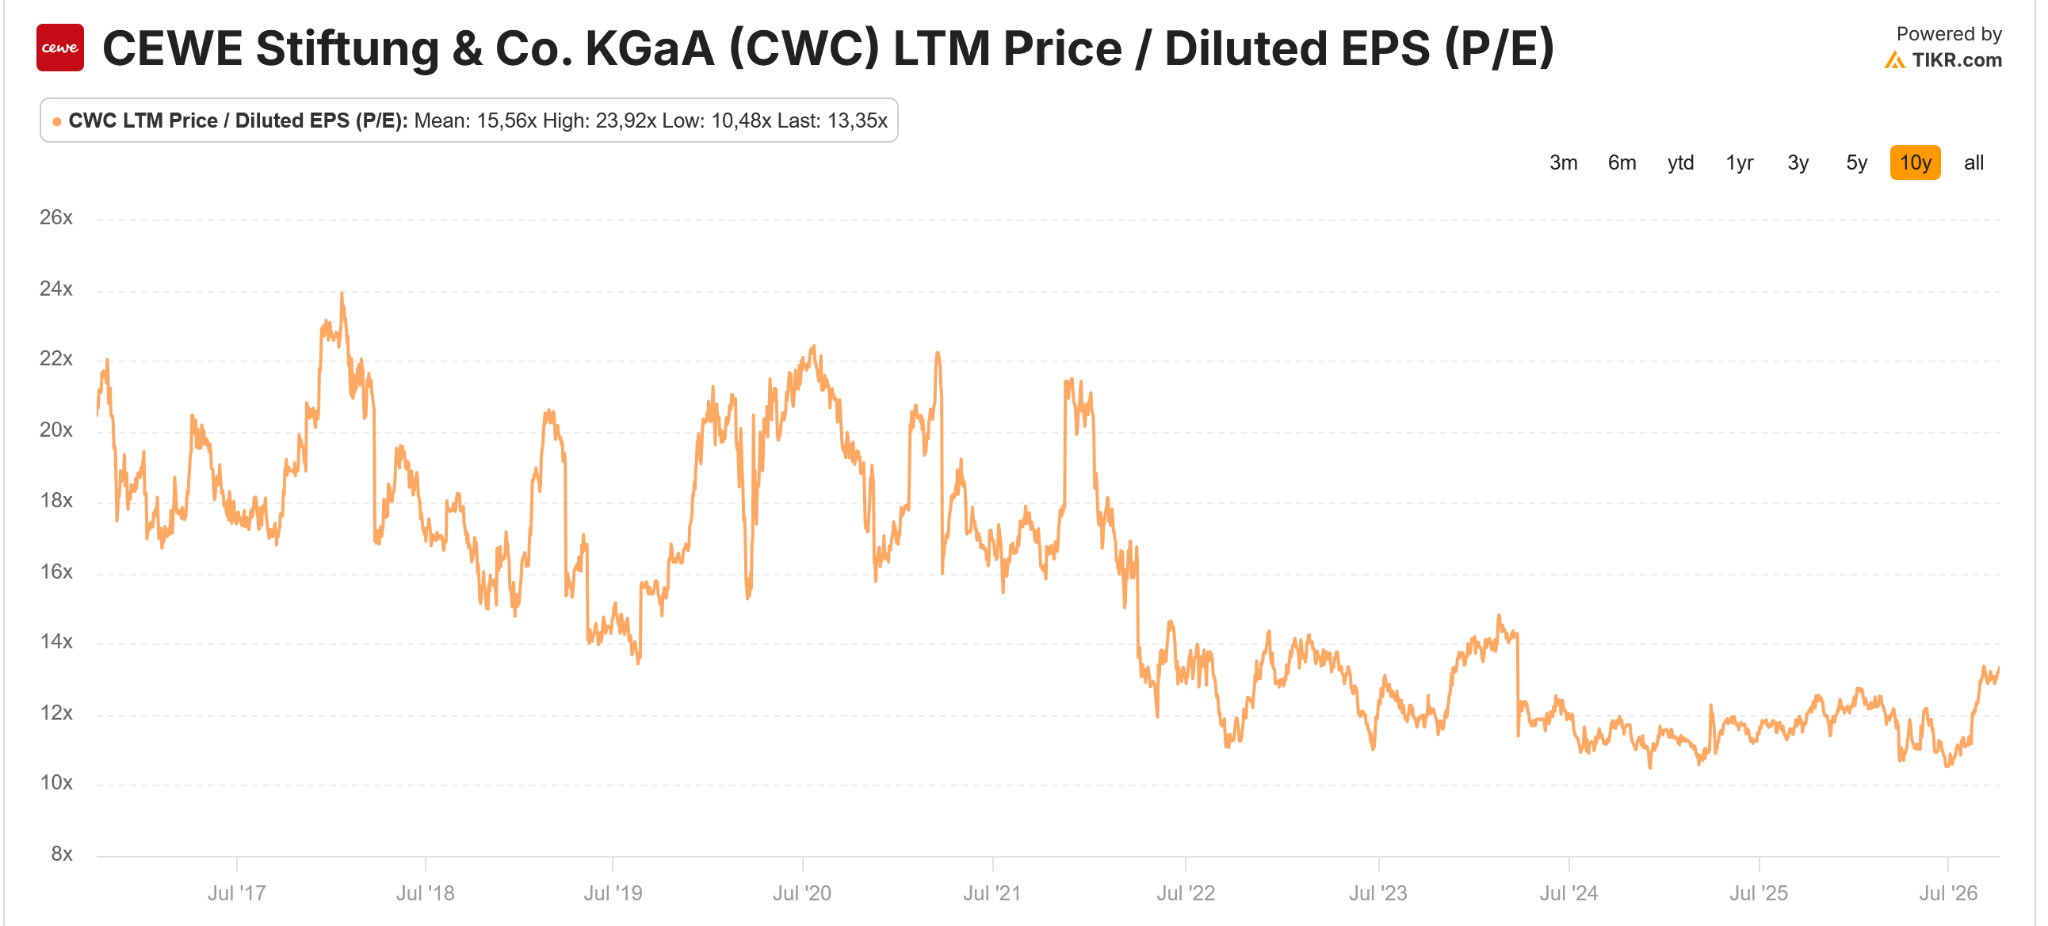
Based on trailing 12M P/E, the stock trades at around 13x P/E vs. an average of 15x:
Pro’s & Con’s
- still cheap
- profitable
- no debt
- 3% dividend yield
- sale of unprofitable division
+/- some share buy backs
- low growth in the last 3 years
- super seasonal business, all in Q4
- KGAA Stiftung
- EBIT margins creeping down
- Kodak Moments acquisition risky
- Large exposure to the German/European consumer
Intermediate conclusion
Although I kind of like CEWE, at this stage I don’t see myself investing into the stock on a 3-5 year horizon,
Yes, it’s cheap, quite profitable and the stock price has just trended upwards. On the other hand, I do see the risk that the recent acquisition might not go so smoothly and I am also not sure about growth prospects after that one time bump from the acquisition.
If I would be in the mood for shorter term trades, I might set up a 3-6 month trade trying to ride the current momentum, but the high interest rates make me nervous.
I also need to manage my exposure in the portfolio to the European consumer to which I am exposed directly and indirectly through stocks like Sixt, Fielmann, Thermador, Italmobiliare etc.
Therefore, for the time being, I am not investing into CEWE but keep it on the watch list.Upfront remarks & Management summary:
This is not a deep dive but more like my “first round screening” of a potential interesting investment. In the past, I would have not necessarily published it if I didn’t invest. Going forward, I will now and then publish these “initial assessments” mainly in order to receive feedback from readers who might see it differently. So please give feedback if you see things different !!!
As a Management Summary, I did not invest. Although I like the company somehow, I could not build up the conviction for a 3-5 year investment case mainly due to recent slow growth and a somewhat risky acquisition.
Company History:
Cewe Color traces its roots back to 1912 to a photo finishing lab in the Northern German town Oldenburg. And that’s what they did for the next ~100 years: “finishing” or “developing” Fotos from films that were given or sent to them. For the (few) younger readers: In the old days, there were real photo cameras where you took the pictures on a rol of film and you could only look at the pictures after they came back from the phot finishing lab.
In 1951 they introduced color pictures, 1994 they started to develop digital pictures and in 2025 they introduced the category that is today’s most relevant: The photo book.
in 2007/2008, CEWE became the target of US activist Guy Wyser-Pratte, who wanted CEWE to speed up its transformation into a digital player. However, in 2008, the activists lost interest.
As a consequence of this “activist attack”, CEWE changed into a KGaA structure in 2013, which makes it factually impossible to take over the company as the listed shares are effectively only non-voting shares.
Here are some current highlights:
This chart from the annual report is very interesting which shows the transition from analogue to digital over the years:
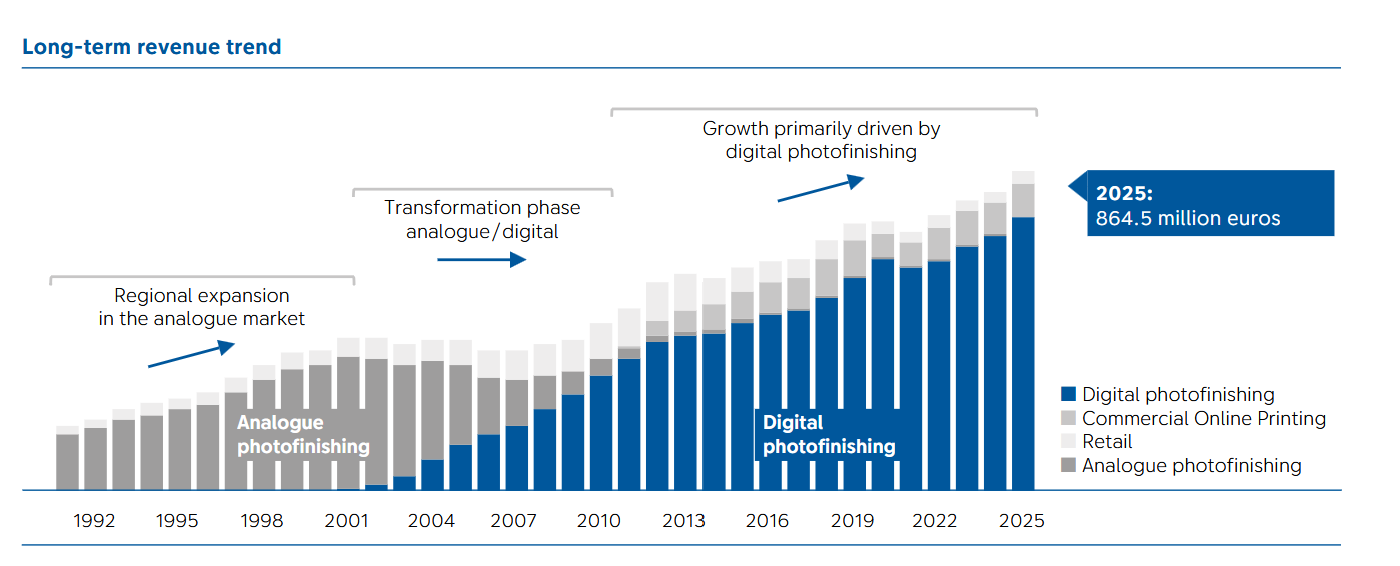
When Wyser-Pratt “attacked” the company in 2007, only~50% of the business was digital, however that changed pretty rapidly.
From different sources, one gets an estimated market share for CEWE in Europe of ~30% and an estimated market share in Germany of >50%.
Recent developments:
Sale of Commercial Online Printing division – This was actually very positive news: Cewe published in May that they were selling their struggling Commercial Online Printing division to Cimpress.
This seems to result in an one-off gain of around 50 mn EUR.
As we see in the numbers, the division was barely profitable and not growing but represented 10% of total sales:
More or less at the same time, CEWE announced an acquisition: They are buying the Kodak Moments business which is basically very similar to their CEWE in-store kiosk business from a US PE fund,
This is what we know from Kodak Business:
Purchase price: 88 mn EUR (including debt)
Sales 200 mn EUR
EBIT margin “mid single digits” – lest assume 5%
That means CEWE paid an EV/EBIT 8,8x vs. 8.3x for CEWE itself. The seller seems to be an American Private Equity investor, who bought this business and another one from the bankrupt UK Kodak pension fund only 2 ago.
I found some information about the business from 2023 where it seems that 40% of the Kodak moments business seems to have been generated in Europe, 3% in the US and the rest in Australia and South America.
So CEWE sold ~2 mn in EBIT and acquired 11 mn EBIT, which seems like an OK deal. The big question s of course if and how fast they can bring the Kodak Moments business up to CEWE’s standards with double digit EBIT Margins.
The main risk that I see is that CEWE’s German Board (one exception) might struggle a bit with the non-European parts of the Kodak Moments business. I am also not 100% sure in what condition this business is after years of bankruptcy and 2 years of PE ownership.
General development
In general, looking at different sources, printing single photos still seems to be in a decline, while photo books seem to be growing, at least from a value perspective.. To my understanding, the acquired Kodak Moments business includes both.
Another question is at what stage, Agentic AI might be an issue for “branded” Photo book offerings. My feeling is that things move quickly, but I have no idea if and when this could be a threat.
Other aspects:
What I do like about CEWE is that they report ROCE which is rather unusual for a German small cap. ROCE numbers are pretty OK:
Ebit margins are double digit, however since the Covid Boom, they have been going down a little bit.
10 year EPS growth from 2015 to 2025 has been ~10,4% p.a. which is pretty impressive. However, since 2023, EPS was rather flatish. The main growth came in the years up to 2022.
This is the EPS chart from Tikr:
Valuation & Share price:
Looking at the chart we can see that CEWE peaked during COVID and traded sideways until recently, underperforming both, SDAX and MDAX (before dividends)::
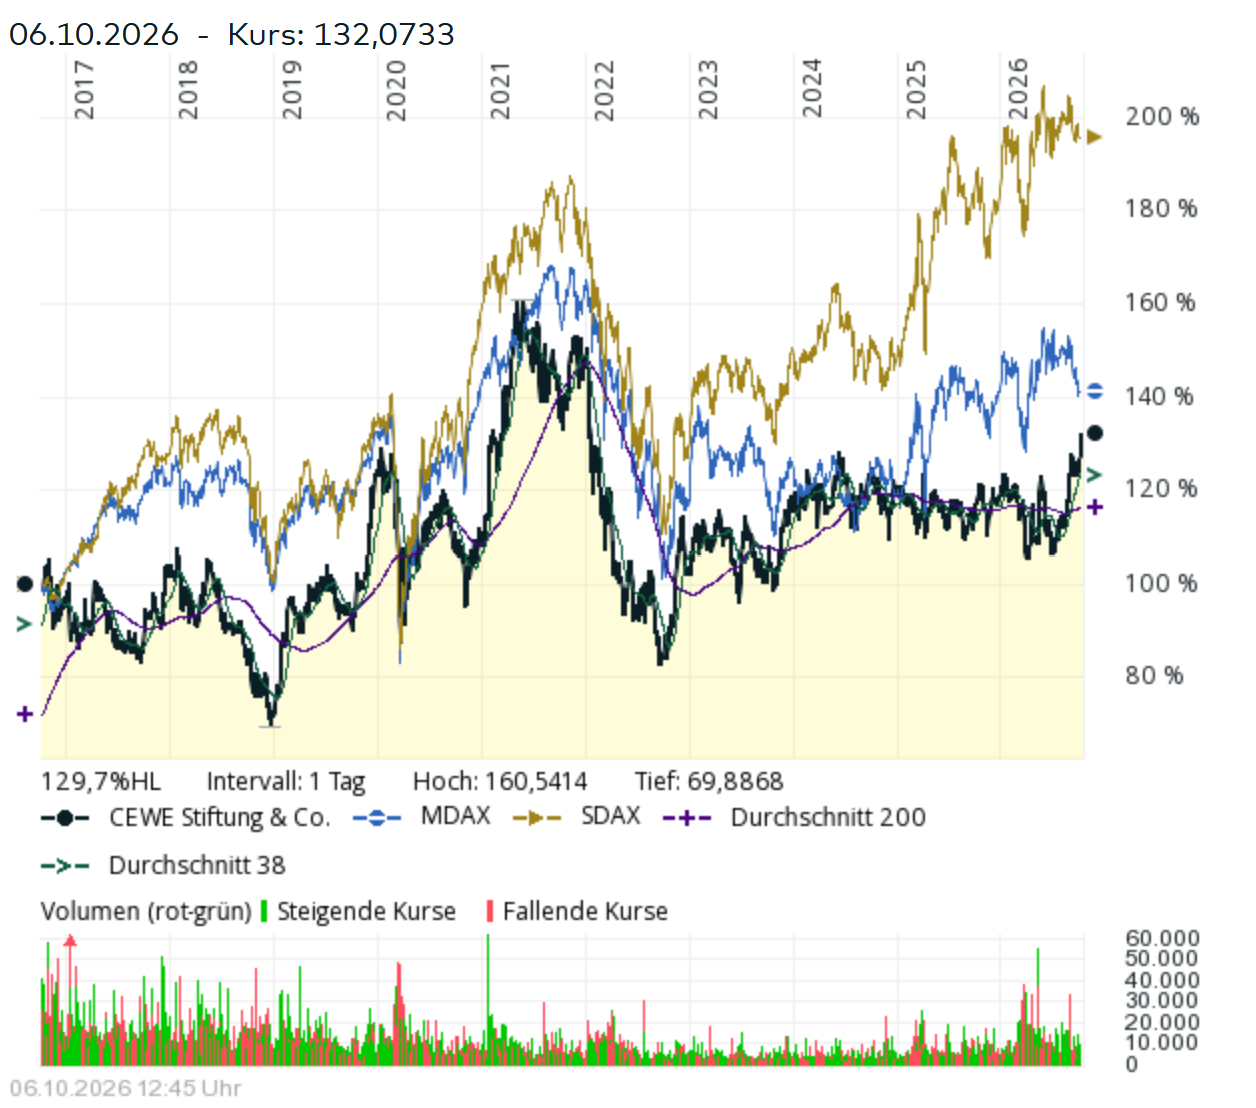
Recently the stock went up from the trading range as some market participants seem to see a better future.
Valuation wise, the stock is still relatively cheap.
Based on trailing 12M P/E, the stock trades at around 13x P/E vs. an average of 15x:
Pro’s & Con’s
- still cheap
- profitable
- no debt
- 3% dividend yield
- sale of unprofitable division
+/- some share buy backs
- low growth in the last 3 years
- super seasonal business, all in Q4
- KGAA Stiftung
- EBIT margins creeping down
- Kodak Moments acquisition risky
- Large exposure to the German/European consumer
Intermediate conclusion
Although I kind of like CEWE, at this stage I don’t see myself investing into the stock on a 3-5 year horizon,
Yes, it’s cheap, quite profitable and the stock price has just trended upwards. On the other hand, I do see the risk that the recent acquisition might not go so smoothly and I am also not sure about growth prospects after that one time bump from the acquisition.
If I would be in the mood for shorter term trades, I might set up a 3-6 month trade trying to ride the current momentum, but the high interest rates make me nervous.
I also need to manage my exposure in the portfolio to the European consumer to which I am exposed directly and indirectly through stocks like Sixt, Fielmann, Thermador, Italmobiliare etc.
Therefore, for the time being, I am not investing into CEWE but keep it on the watch list.
By the way, please also let me know if you find this format helpful/interesting or not.

