Category Archives: Capital allocation

Updates: DCC (sold), TFF (sold), EVS (hammered) & Rightmove (rumours)

DCC – post mortem

Let’s start with the positive case. I realized my DCC position recently as the share price (~64,4 GBP) approached the bid value (66,72 GBP) and the remaining upside was not so attractive anymore, especially considering potential GBP volatility for me as a EUR investor.

Looking back at the initial write-up, the result was pretty Ok.  

I made slightly over +50% over 3 ¾ years plus some more on the additional portion I bought after the first bid in May this year. This was within the expected range of outcomes:
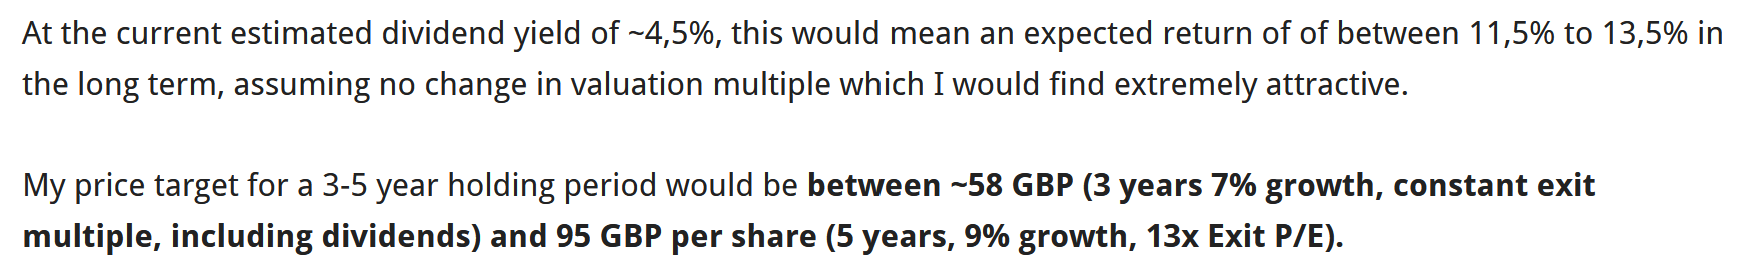
However, and this is a big HOWEVER, this positive result was not driven by the business case that I had underwritten, but purely a function of the premium paid by the acquirer KKR.

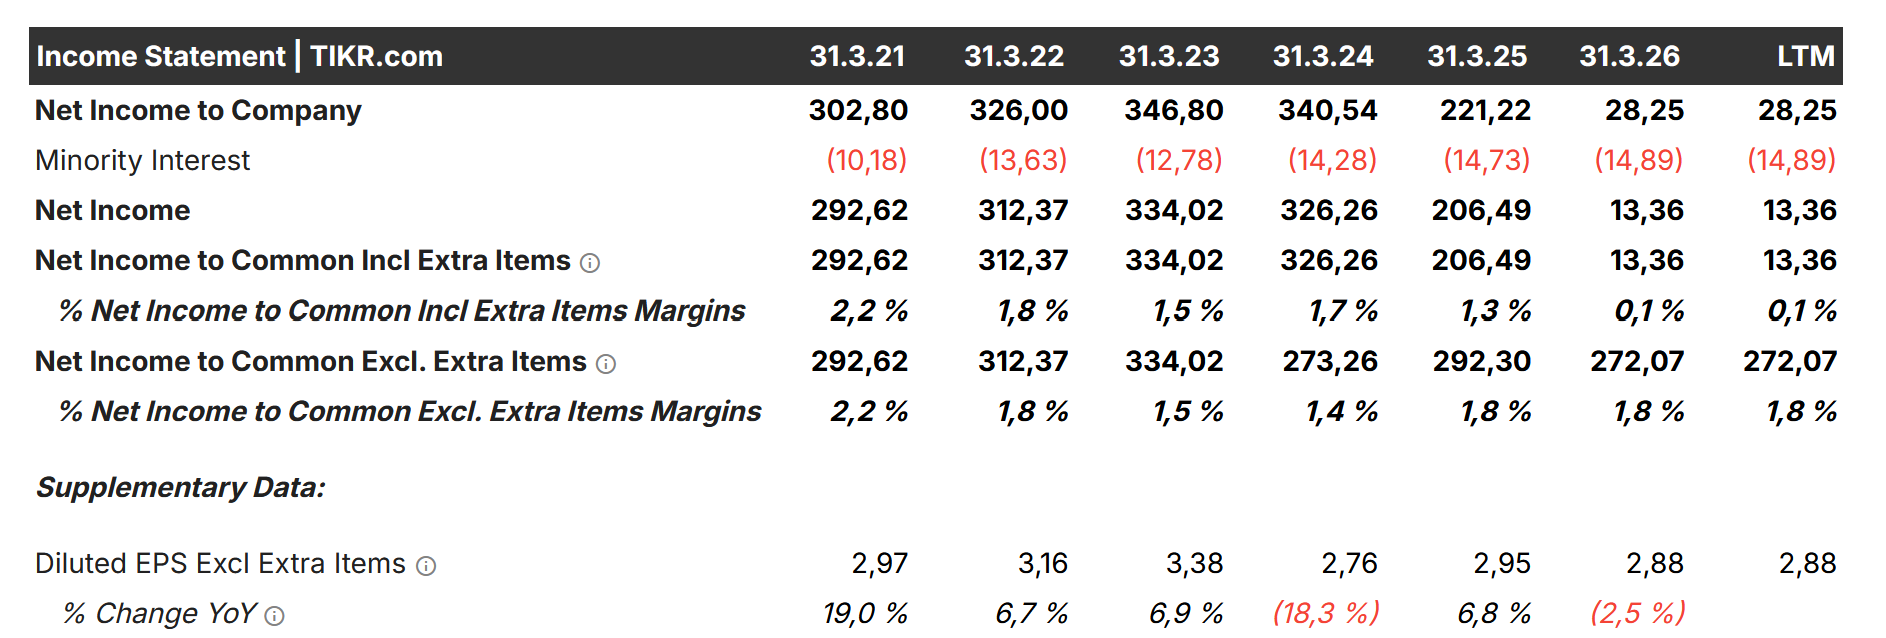
Looking at the earnings history, we can see that DCC’s earnings didn’t improve at all since my purchase in late 2022:
DCC rather had to go through a painful restructuring because they found out that everything they acquired outside their core business Energy was rather not good.

To be honest, I didn’t see this when I invested back then. I rather thought that having 3 different “platforms” gives them a lot of flexibility to allocate capital.

Looking at the stock chart we can see that my entry timing was quite lucky, but then not much happened until very recently:
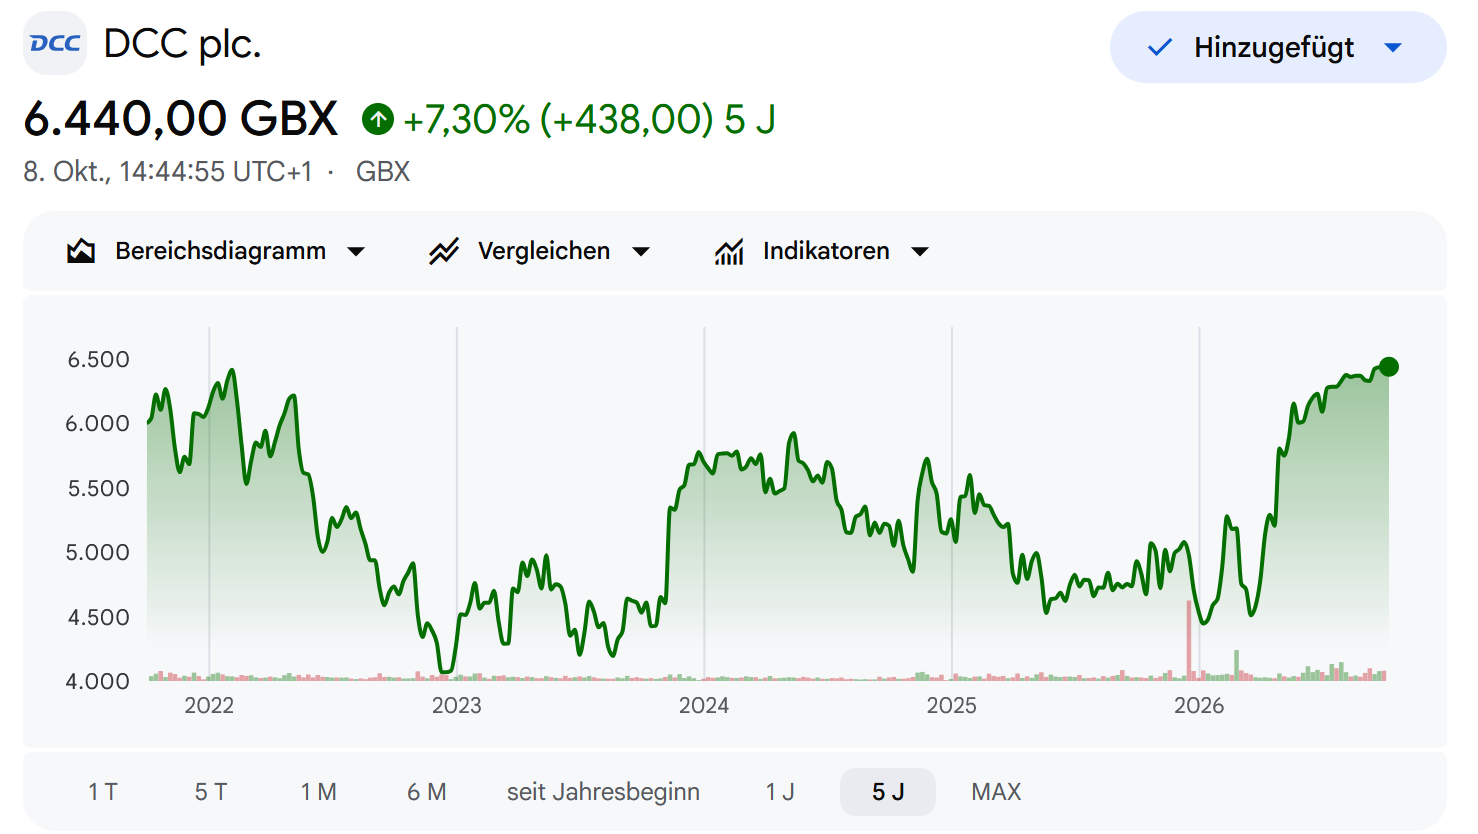
So the positive outcome of this investment was much more luck than my ability to pick an undervalued company with a great past that performed well.

I think this is/was maybe a major weakness of my investment approach: Just assuming that a successful past is a good indicator for an equally successful future, depsite some temporary headwinds. This can work, but it clearly doesn’t have to work.

What went well though was the decision to increase the position after the first bid. While this was not a huge performance driver for the overall position, it was a very low risk Special situation add-on.

Quick update: Just an hour ago, DCC announced that they sold the remaining business from the Technology segment for a rather “lowish” price. From a potential 125 pence “Sweetener” for this deal the actual outcome seems to be “only” 42 pence now.

TFF post mortem

Funnily enough, I funded part of my DCC position as mentioned above with a partial sale of TFF, which back then was my largest position. I just checked my files and I sold ~11% of my position back then for ~39,70 EUR per share.

TFF was my oldest position and the only stock remaining from the initial portfolio from December 2010.

So why did I decide to sell now ? To be honest, i had been thinking about reducing/selling for quite some time. I wrote about my doubts already in the 2026 performance review in January 2026 and subsequently sold my Laurent Perrier shares.

With regard to TFF,  I cautiously thought that maybe the worst is behind us.

And:
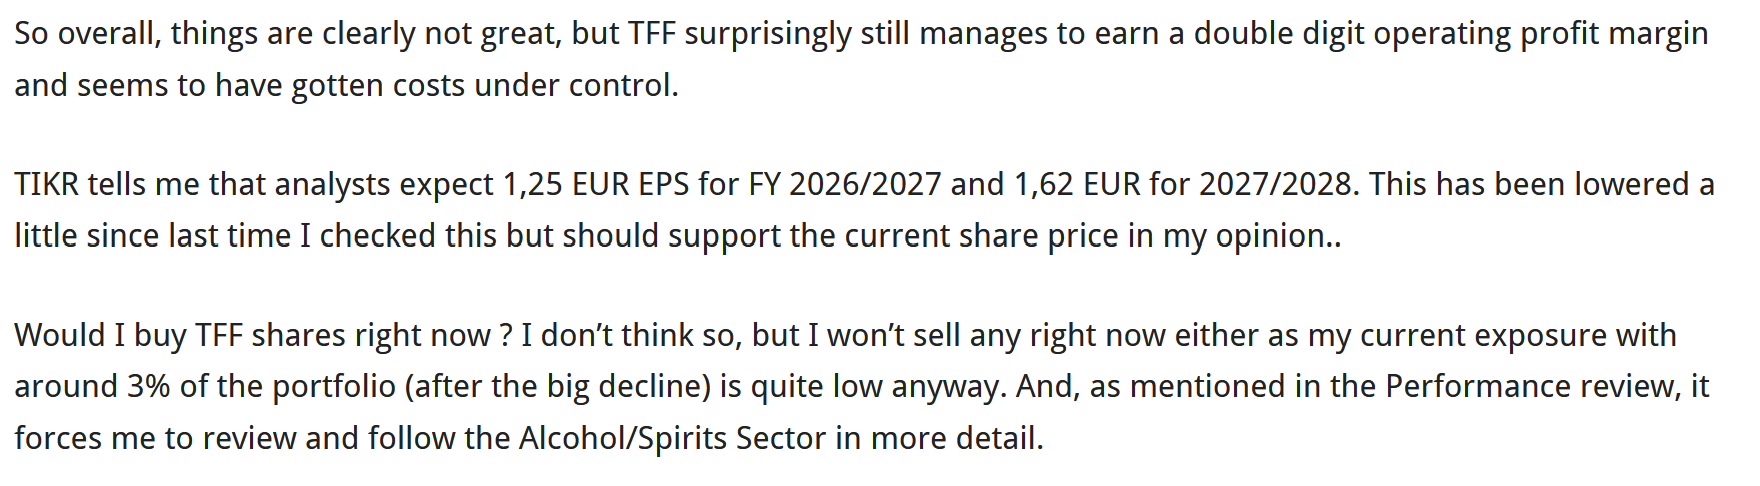
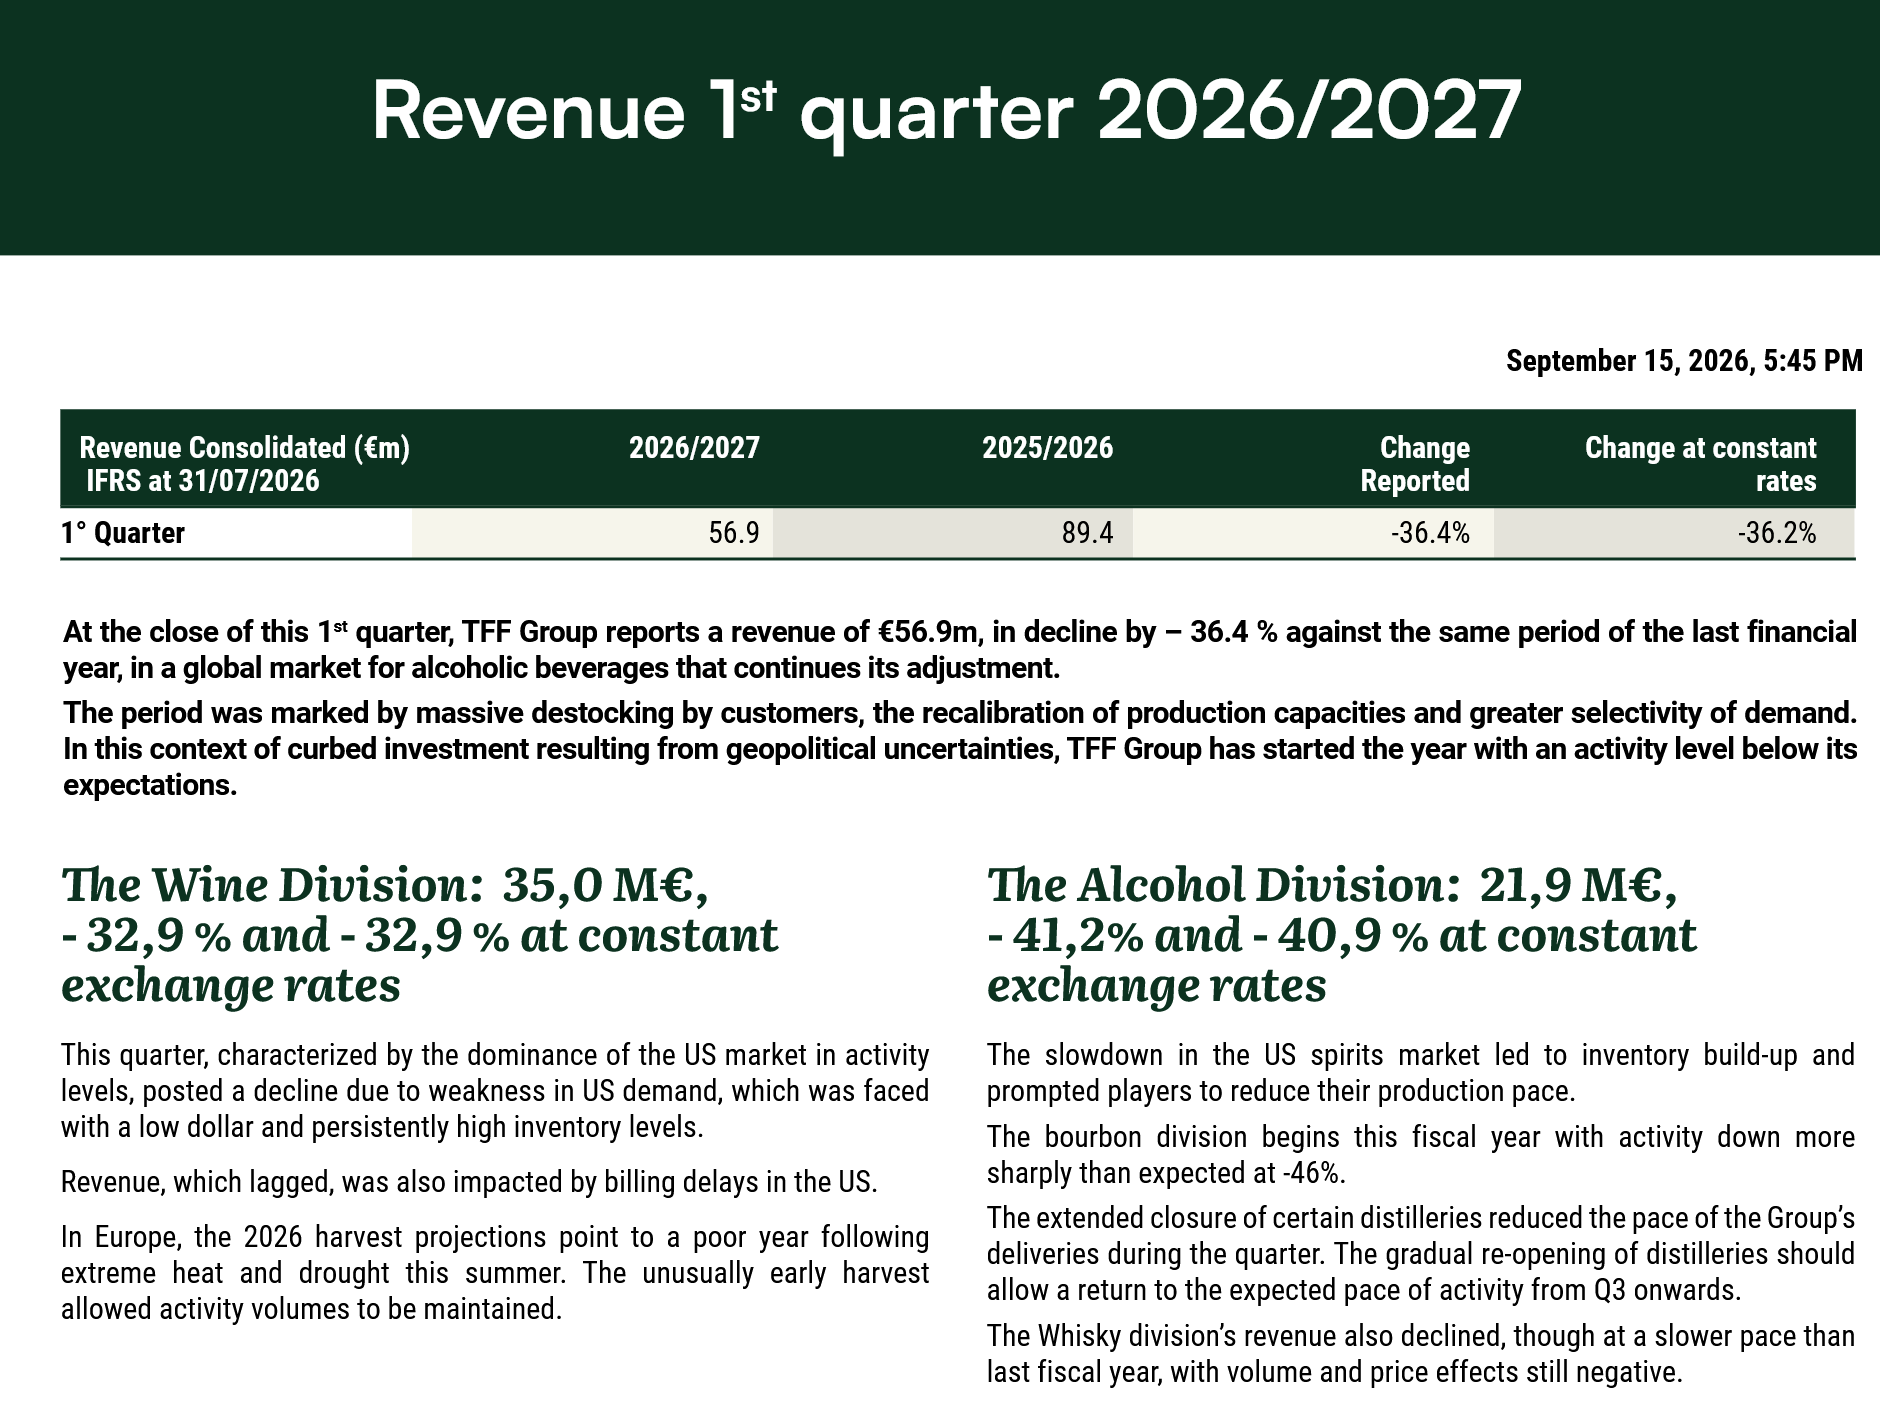
Then however came the horrible horrible Q1 (2026/2027) report in mid Septmeber which showed once again an acceleration of the sales decline, both in Wine and Whisky:
What really worries me now is the debt level of TFF. With declining Sales and profits, the 300 mn in net debt will become a larger and larger burden and refinancing this with the rapidly increasing interest rates especially in France is clearly not so easy.

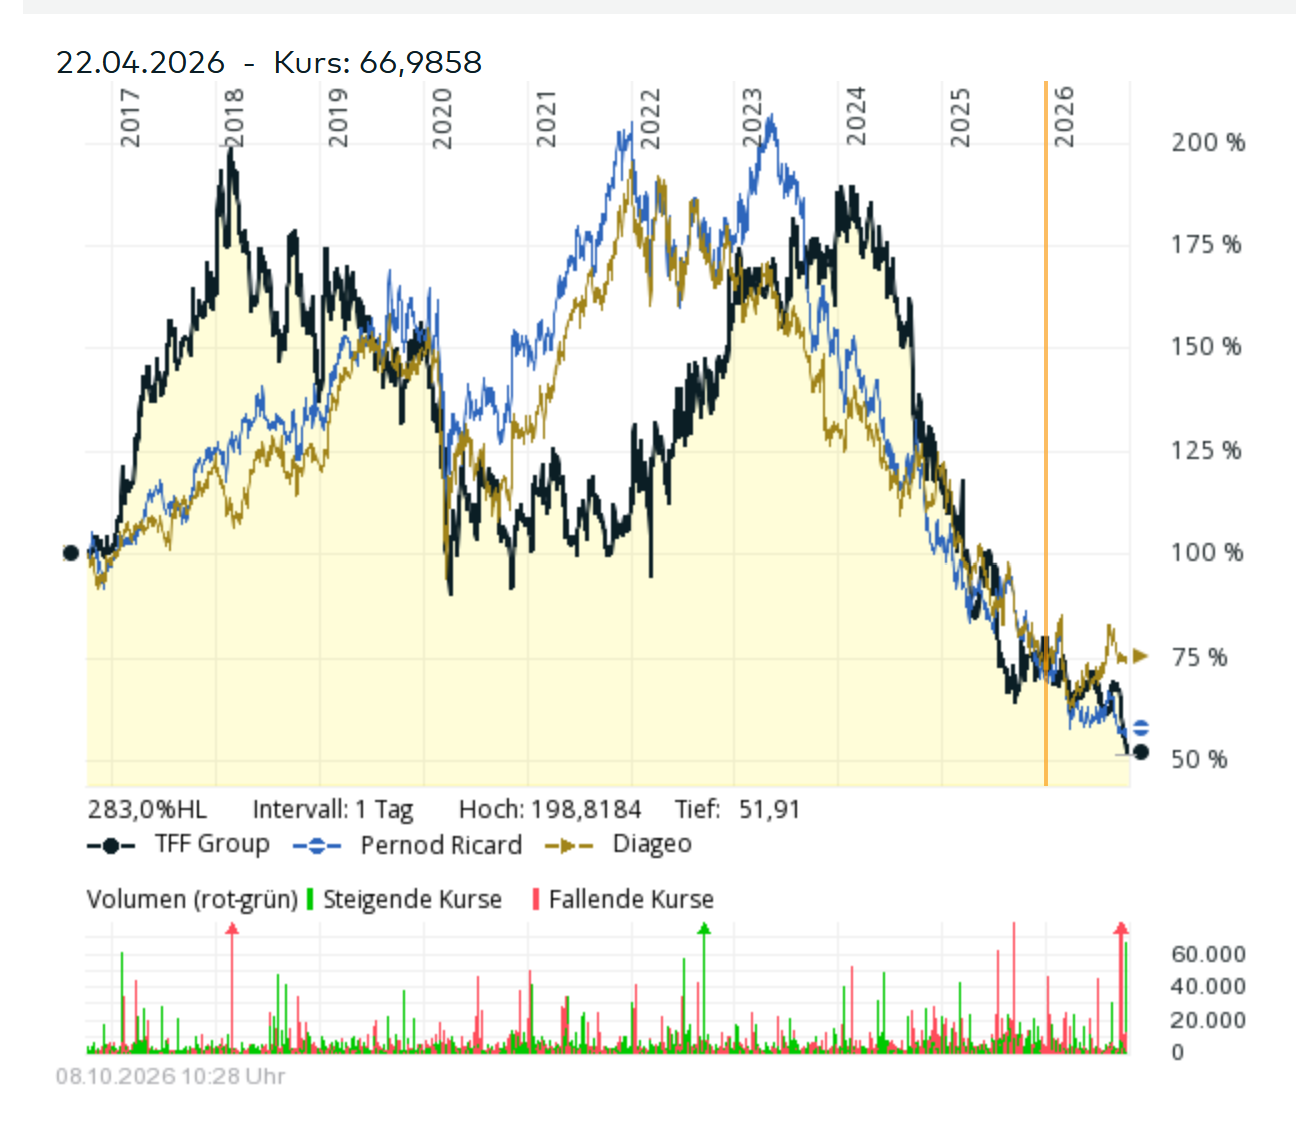
What I find interesting, looking at the charts of TFF  vs. Pernod and Diageo, is that TFF’s share price for some reason kept up longer than the actual spirits makers:
One of the disadvantages of writing a blog is that when I write about a decision like this one, the risk is relatively high that I look like a complete idiot if the stock rebounds within a short period of time. Then the usual group of trolls will make nasty comments that I delete (of course).

I think that was also one of the implicit reasons why I didn’t sell earlier. Going forward, I think I will move from a “real time blog portfolio” to something like a “quarterly rebalanced watchlist” in order to avoid such “mental traps”.

In any case, after almost 17 years, I sold my TFF position which now was only 2% of the portfolio. My average purchase price (including a later purchase at a higher price ) was 11,75 EUR and I collected 4 EUR in dividends per share. That’s about 2% p.a. over almost 17 years. It improves a little bit taking into account the mentioned partial sale in 2022. But overall, the result was not great.

EVS

Luckily, I sold EVS in July because I didn’t feel comfortable after the CFO suddenly disappeared and numbers looked weak in an “event year” with Olympics and the Football Worldcup.

Yesterday, EVS drastically reduced their sales outlook for 2026 and the stock got hit really hard and was down -30% at the end of the day:
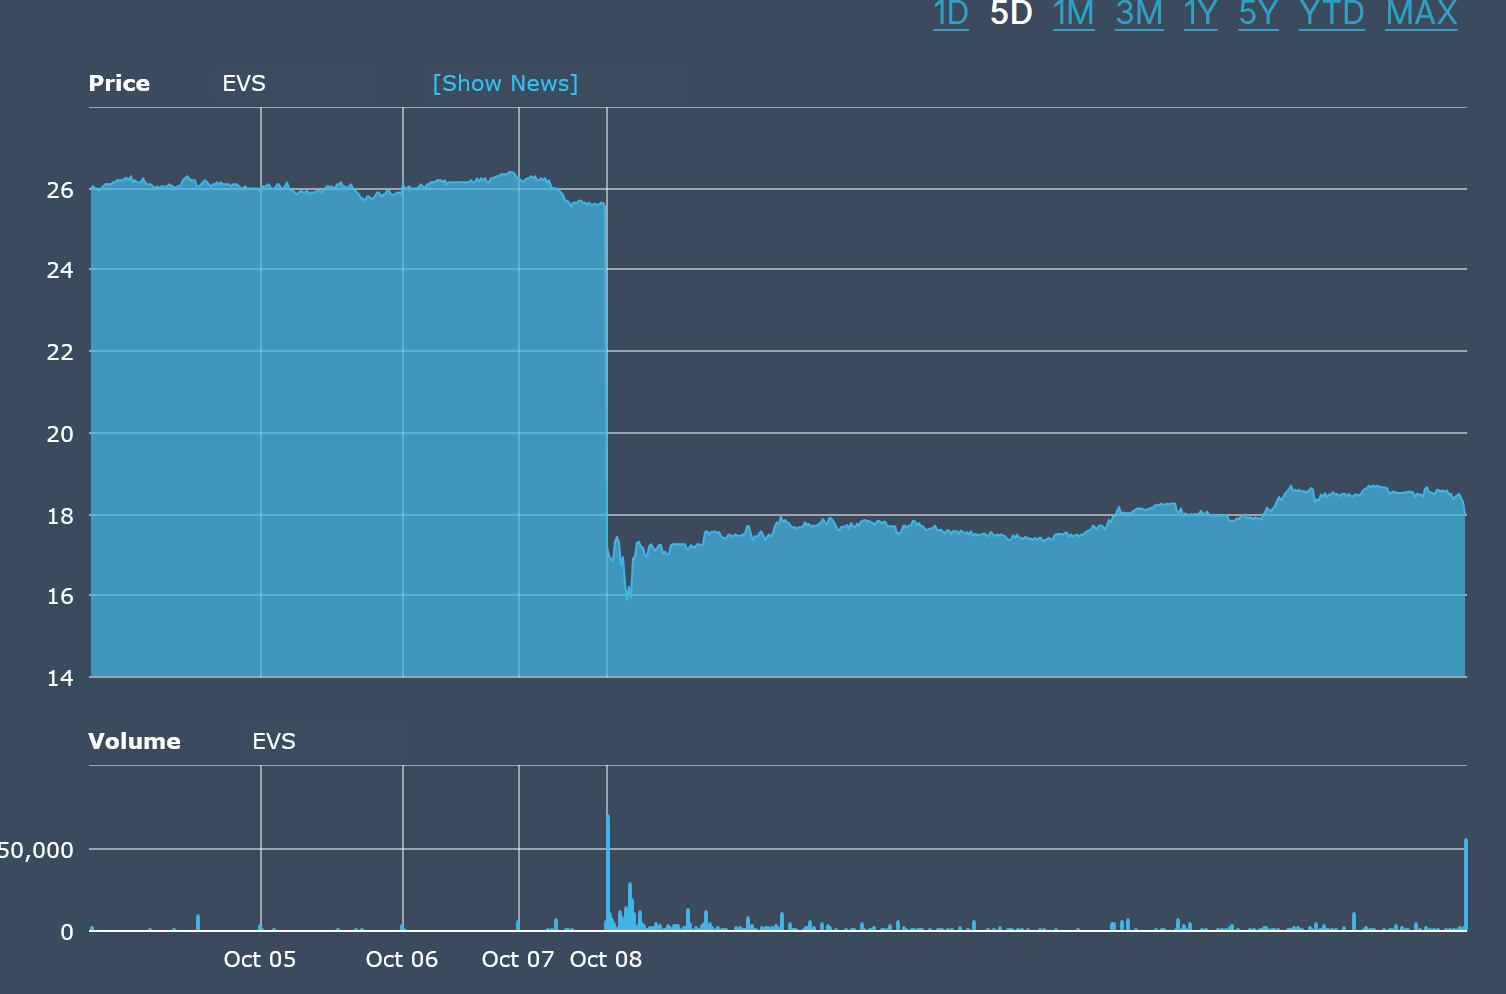
And this after being already down -30% YTD.

In this case, my timing was fortunately better than usual. 

Rightmove 

Yesterday around 4 pm my time, Rightmove suddenly jumped almost 15% because an outlet called “Betaville” mentioned that they heard about a rumor of take over interest for Rightmove.
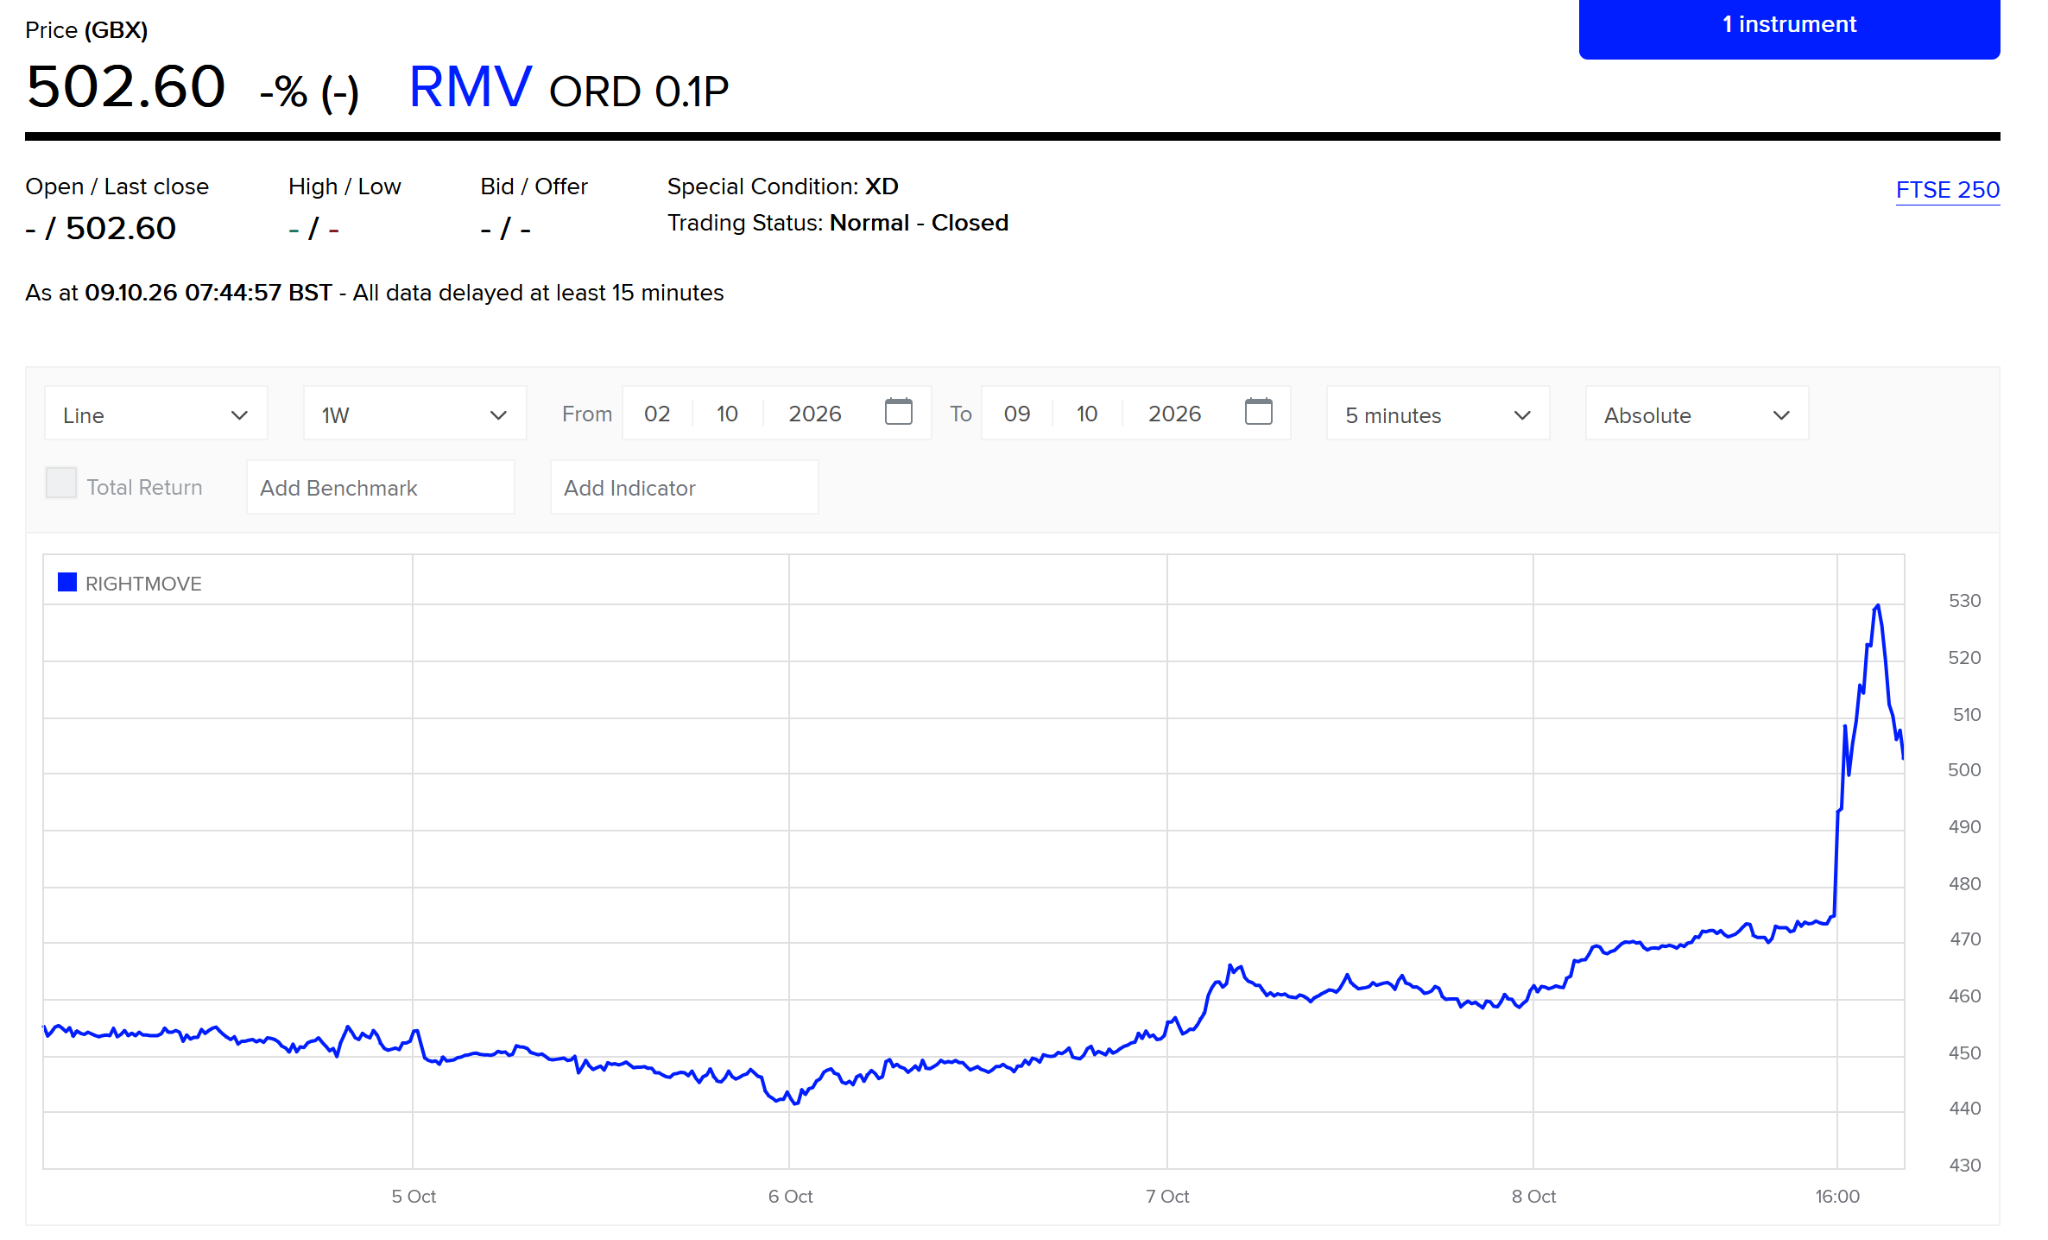
No one knows if there is any truth in that or not, but the significant reaction in the share price in my opinion shows that maybe (and this is a big maybe), the worst is behind for the major classified/marketplace players.
CEWE KGaA – Good company but not a “Buy” yet ?

Upfront remarks & Management summary:

This is not a deep dive but more like my typical “first round screening” of a potential interesting investment. In the past, I would have not necessarily published it if I didn’t invest. Going forward, I will now and then publish these “initial assessments” mainly in order to receive feedback from readers who might see it differently. So please give feedback if you see things different !!!

As a Management Summary, I did not invest. Although I like the company, I could not build up the conviction for a 3-5 year investment case mainly due to recent slow growth and a somewhat risky acquisition. 

Company History:

Cewe Color traces its roots back to 1912 to a photo finishing lab in the Northern German town Oldenburg. And that’s what they did for the next ~100 years: “finishing” or “developing” Fotos from films that were given or sent to them. For the (few) younger readers: In the old days, there were real photo cameras where you took the pictures on a rol of film and you could only look at the pictures after they came back from the phot finishing lab.

In 1951 they introduced color pictures, 1994 they started to develop digital pictures and in 2025 they introduced the category that is today’s most relevant: The photo book.

in 2007/2008, CEWE became the target of US activist Guy Wyser-Pratte, who wanted CEWE to speed up its transformation into a digital player. However, in 2008, the activists lost interest.

As a consequence of this “activist attack”, CEWE changed into a KGaA structure in 2013, which makes it factually impossible to take over the company as the listed shares are effectively only non-voting shares.

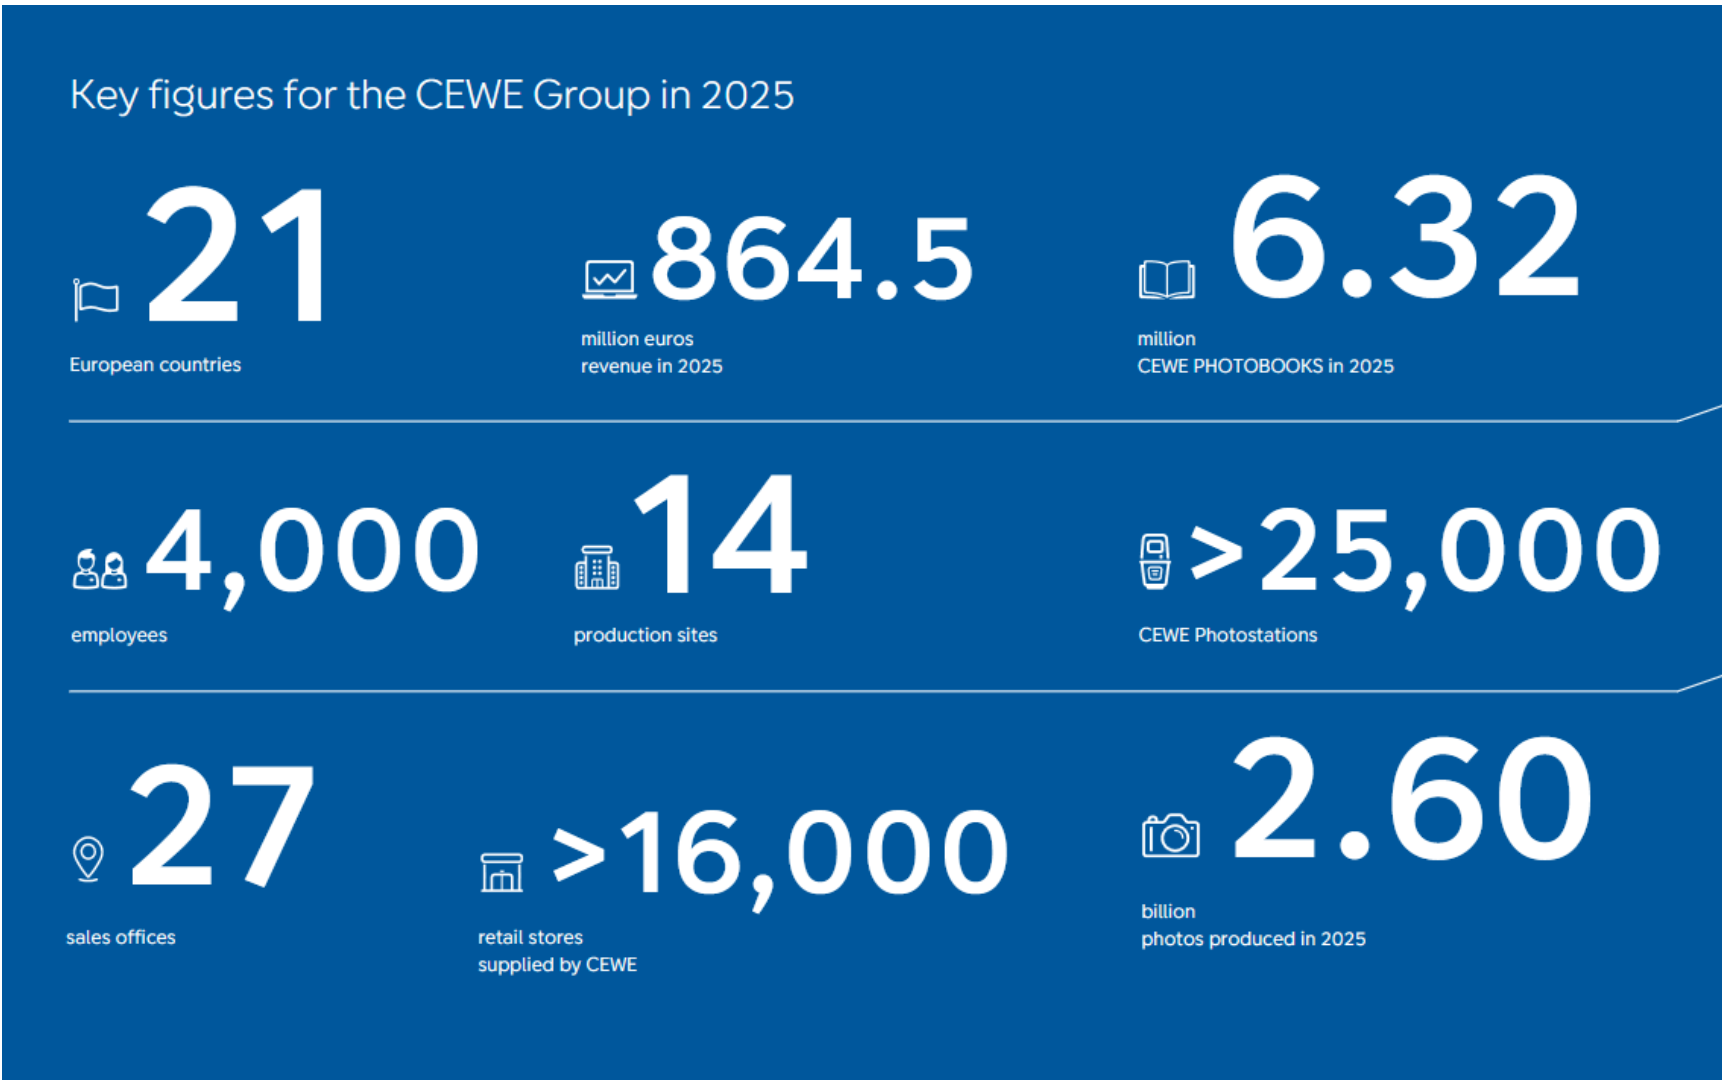
Here are some current highlights:

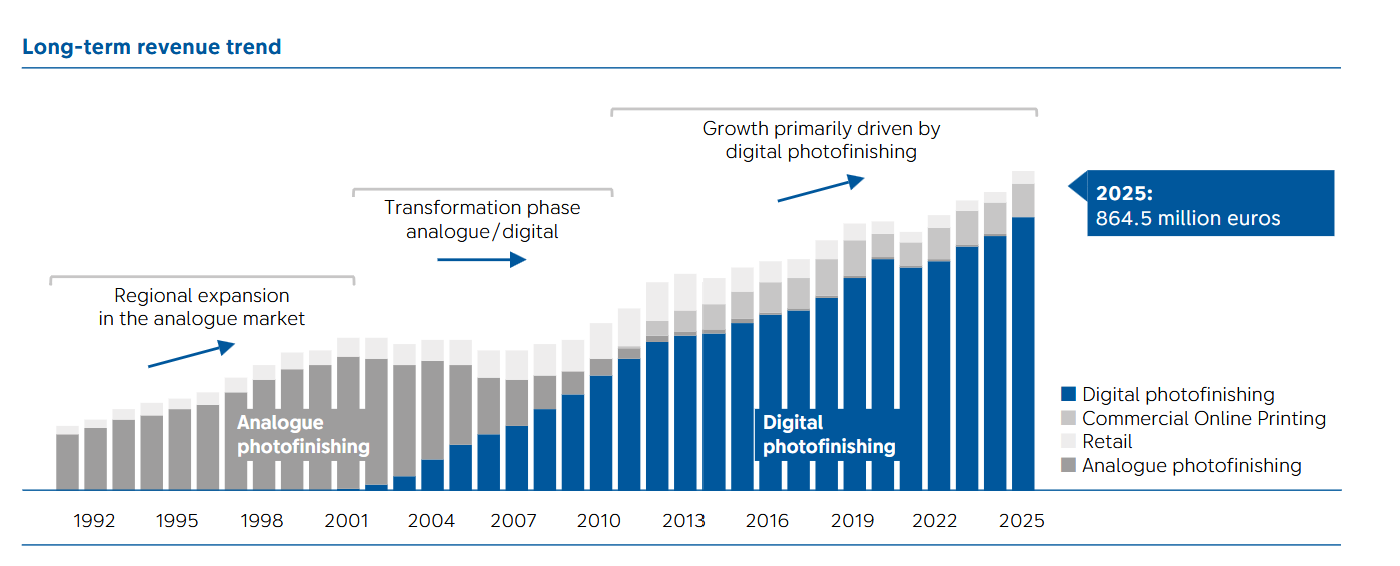
This chart from the annual report is very interesting which shows the transition from analogue to digital over the years:

When Wyser-Pratt “attacked” the company in 2007, only~50% of the business was digital, however that changed pretty rapidly.

From different sources, one gets an estimated market share for CEWE in Europe of ~30% and an estimated market share in Germany of >50%.

Recent developments: 

Sale of Commercial Online Printing division – This was actually very positive news: Cewe published in May that they were selling their struggling Commercial Online Printing division to Cimpress. 

This seems to result in an one-off gain of around 50 mn EUR.

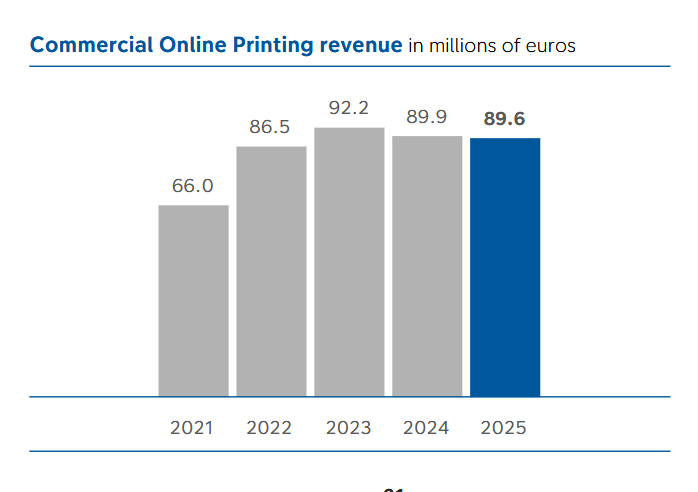
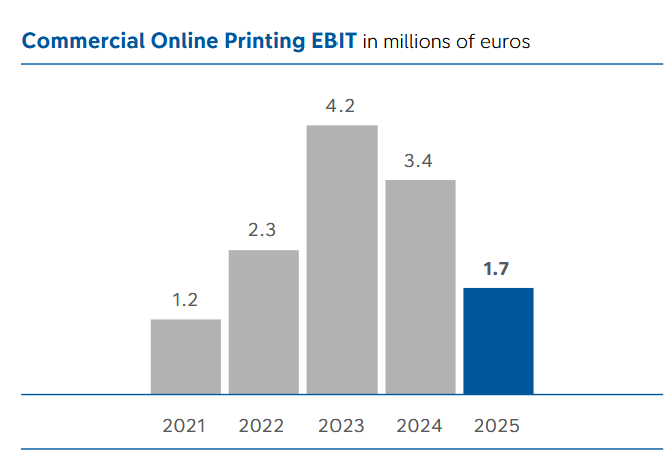
As we see in the numbers, the division was barely profitable and not growing but represented 10% of total sales:

More or less at the same time, CEWE announced an acquisition: They are buying the Kodak Moments business which is basically very similar to their CEWE in-store kiosk business from a US PE fund,

This is what we know from Kodak Business:

Purchase price: 88 mn EUR (including debt)

Sales 200 mn EUR

EBIT margin “mid single digits” – lest assume 5%

That means CEWE paid an EV/EBIT 8,8x vs. 8.3x for CEWE itself. The seller seems to be an American Private Equity investor, who bought this business and another one from the bankrupt UK Kodak pension fund only 2  ago.

I found some information about the business from 2023 where it seems that 40% of the Kodak moments business seems to have been generated in Europe, 3% in the US and the rest in Australia and South America.

So CEWE sold ~2 mn in EBIT and acquired 11 mn EBIT, which seems like an OK deal. The big question s of course if and how fast they can bring the Kodak Moments business up to CEWE’s standards with double digit EBIT Margins.

The main risk that I see is that CEWE’s German Board (one exception) might struggle a bit with the non-European parts of the Kodak Moments business. I am also not 100% sure in what condition this business is after years of bankruptcy and 2 years of PE ownership.

General development

In general, looking at different sources, printing single photos still seems to be in a decline, while photo books seem to be growing, at least from a value perspective.. To my understanding, the acquired Kodak Moments business includes both.

Another question is at what stage, Agentic AI might be an issue for “branded” Photo book offerings. My feeling is that things move quickly, but I have no idea if and when this could be a threat.

Other aspects:

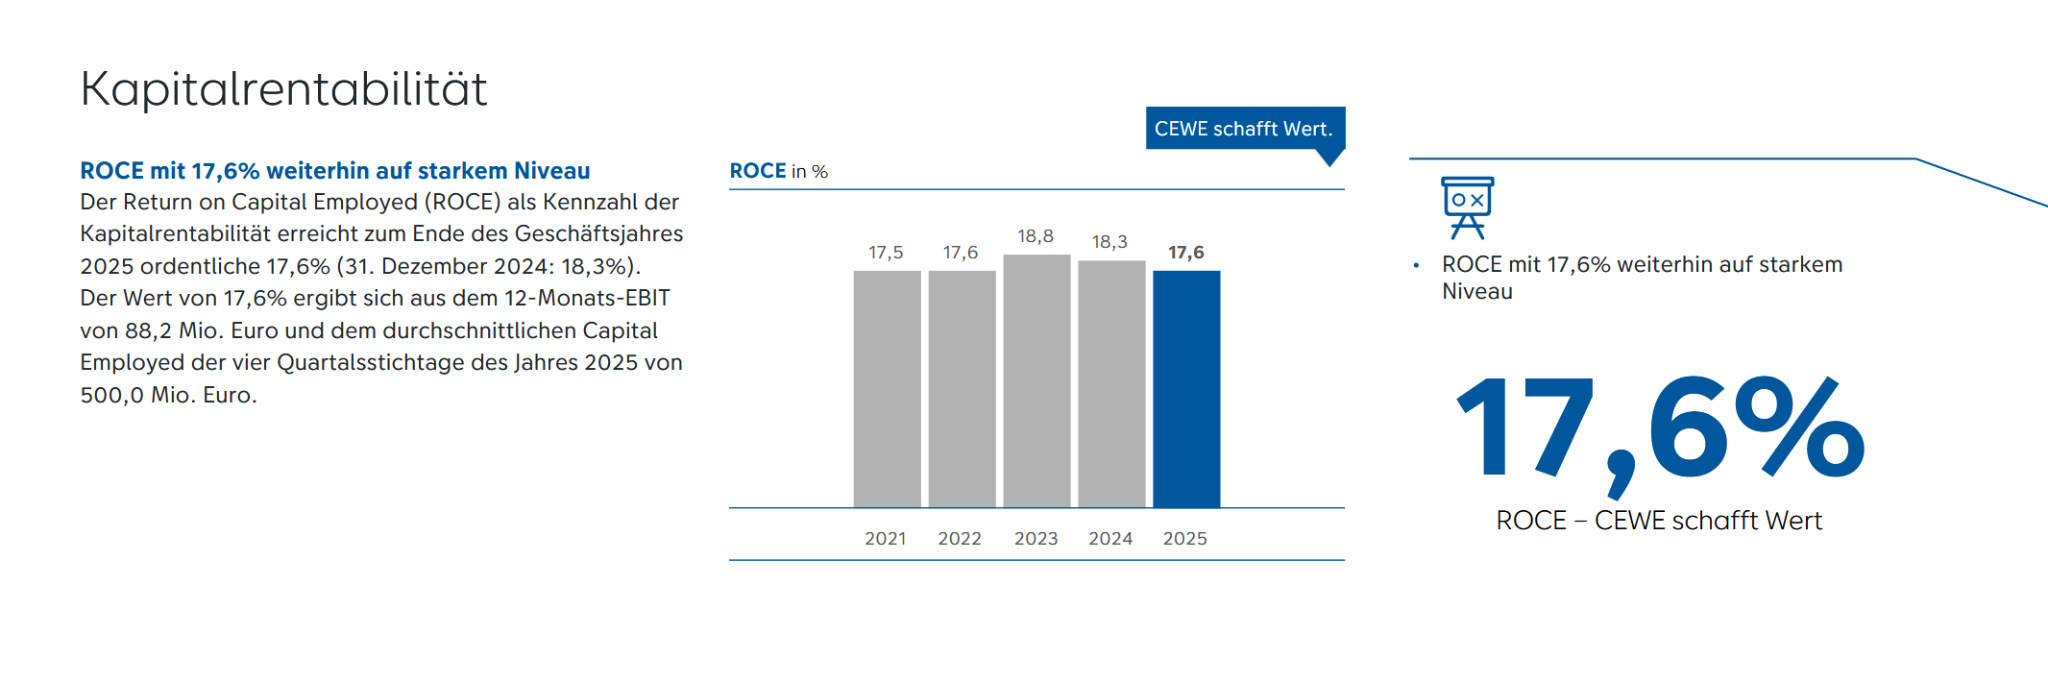
What I do like about CEWE is that they report ROCE which is rather unusual for a German small cap. ROCE numbers are pretty OK:

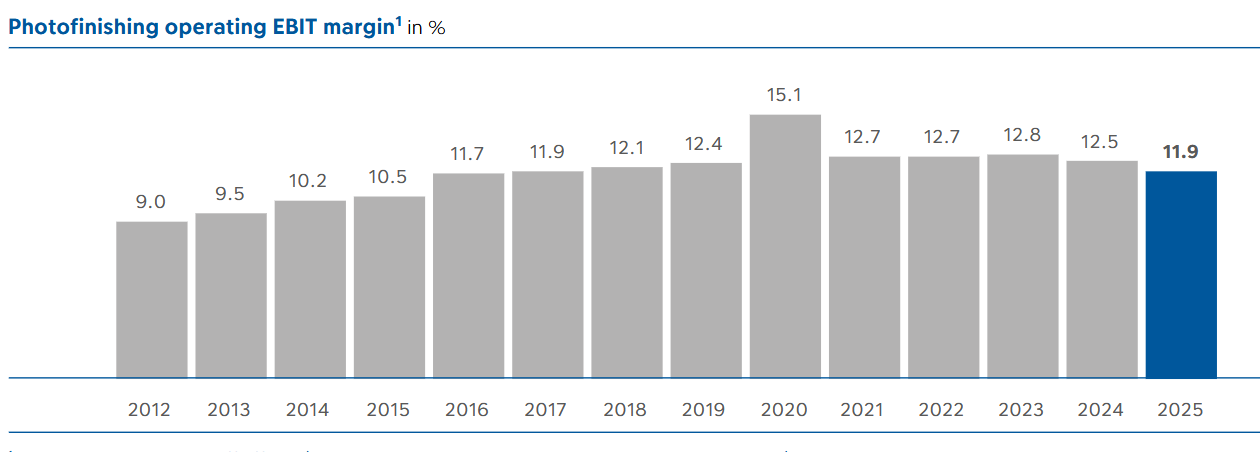
Ebit margins are double digit, however since the Covid Boom, they have been going down a little bit.

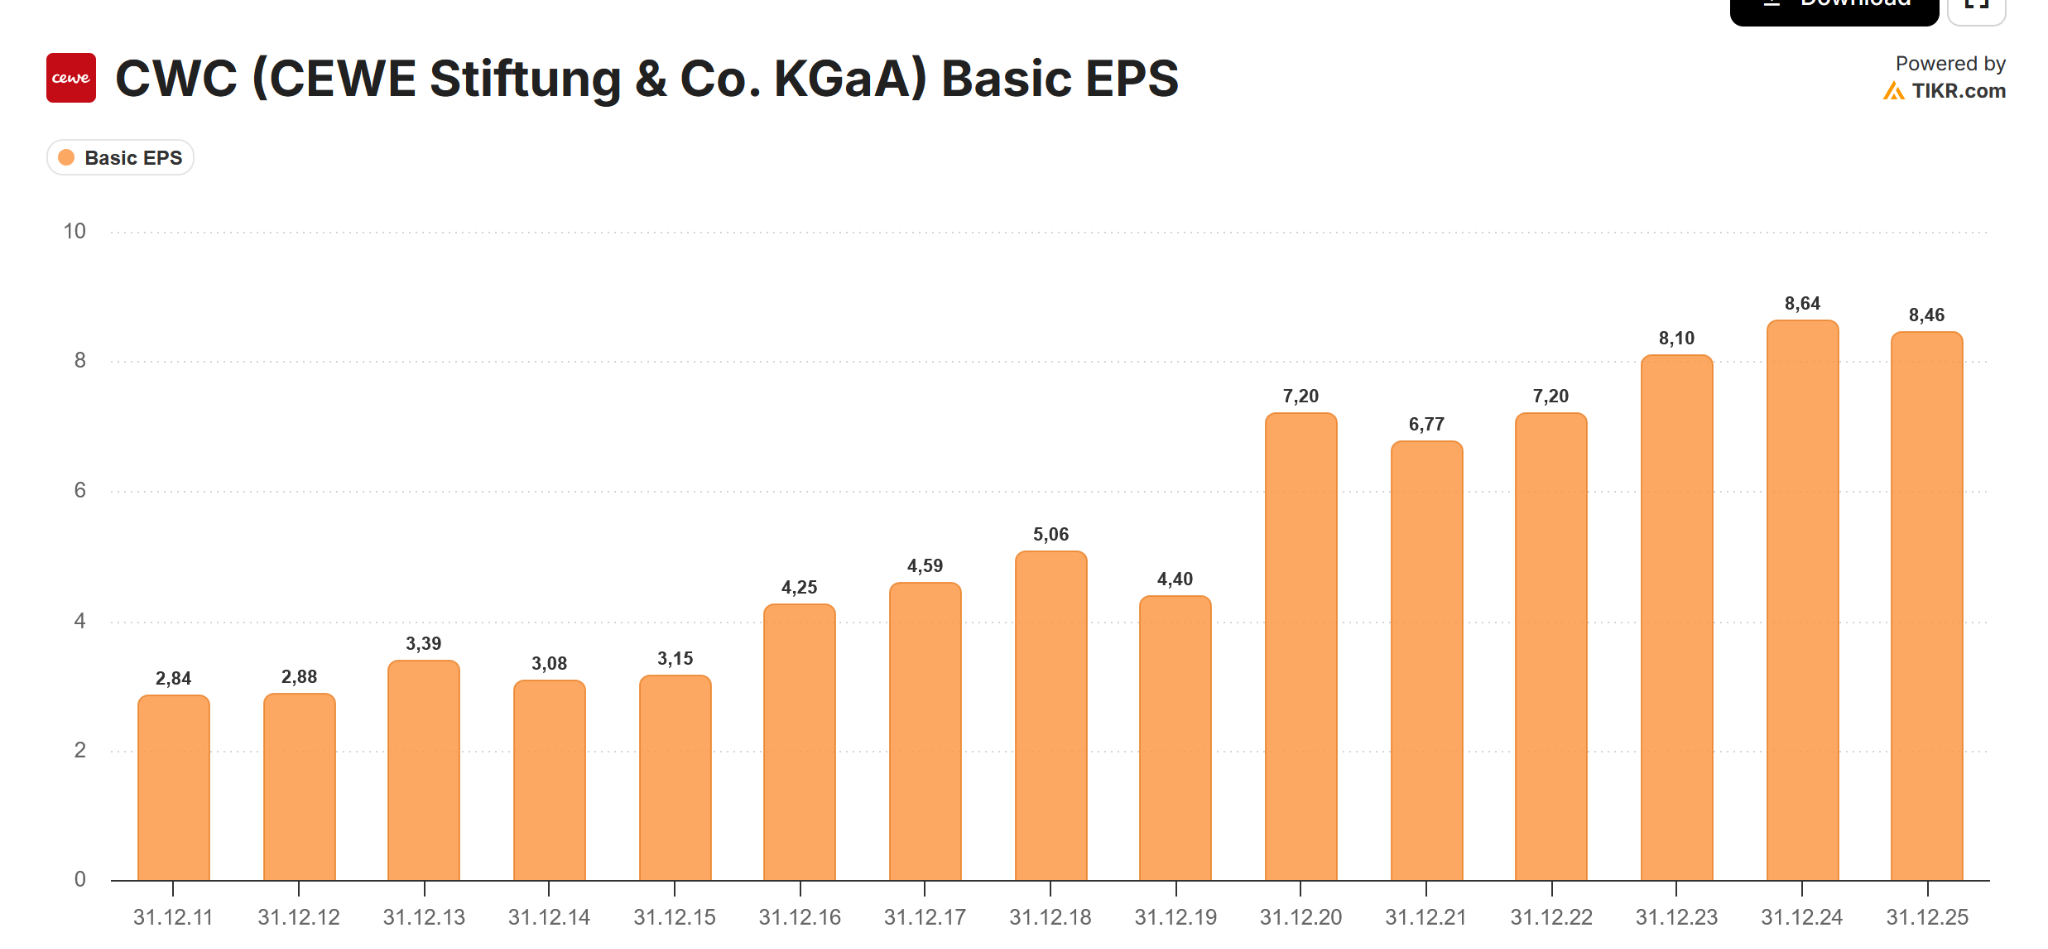
10 year EPS growth from 2015 to 2025 has been ~10,4% p.a. which is pretty impressive. However, since 2023, EPS was rather flatish. The main growth came in the years up to 2022.

This is the EPS chart from Tikr:

Valuation & Share price:

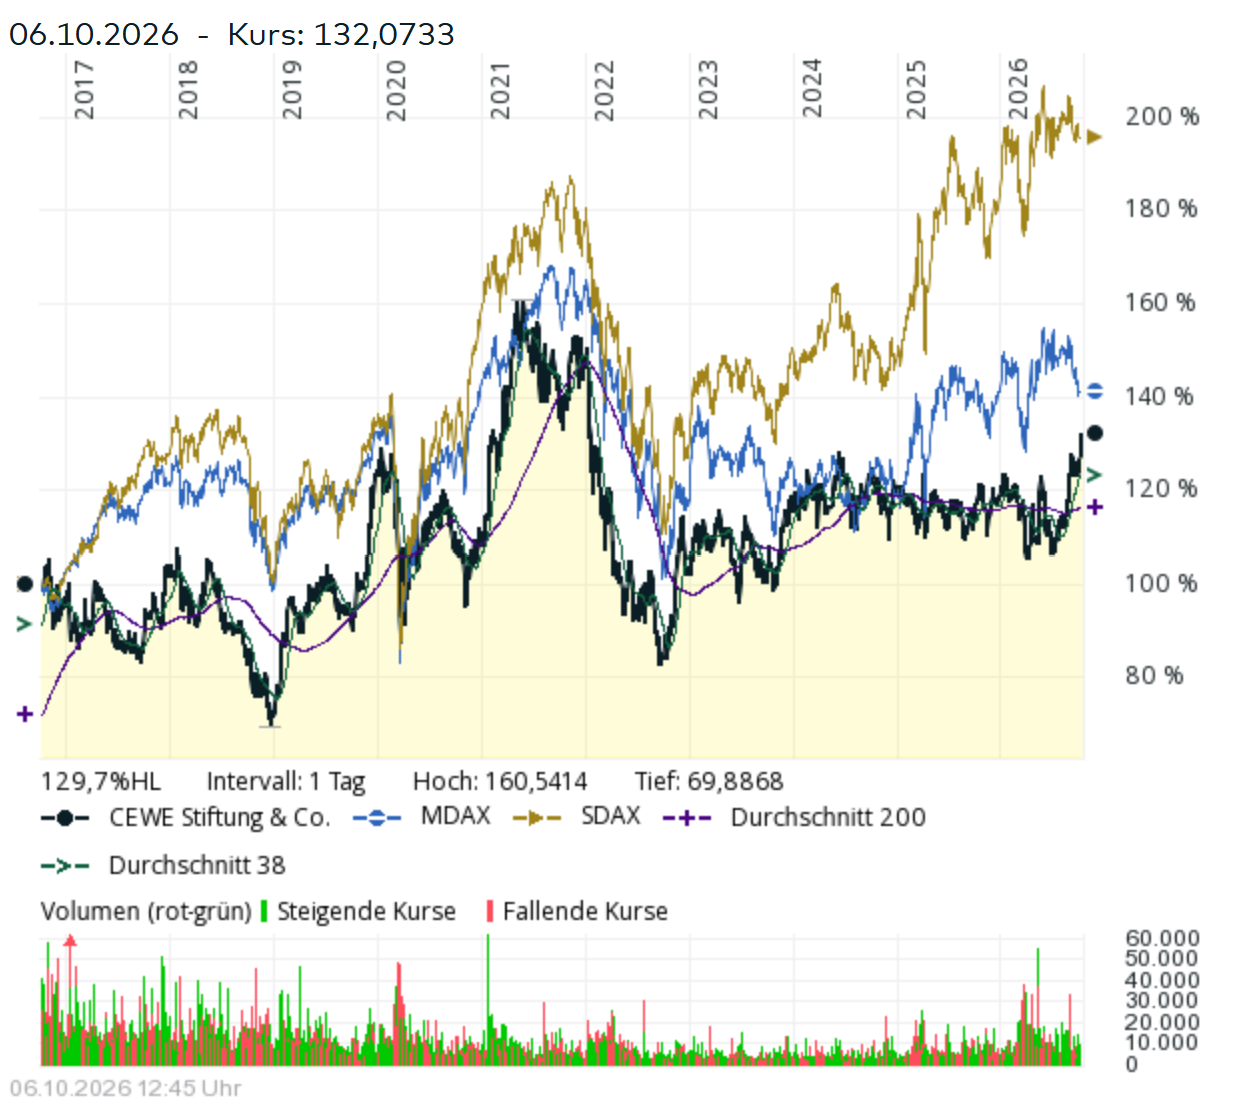
Looking at the chart we can see that CEWE peaked during COVID and traded sideways until recently, underperforming both, SDAX and MDAX (before dividends)::

Recently the stock went up from the trading range as some market participants seem to see a better future.

Valuation wise, the stock is still relatively cheap.

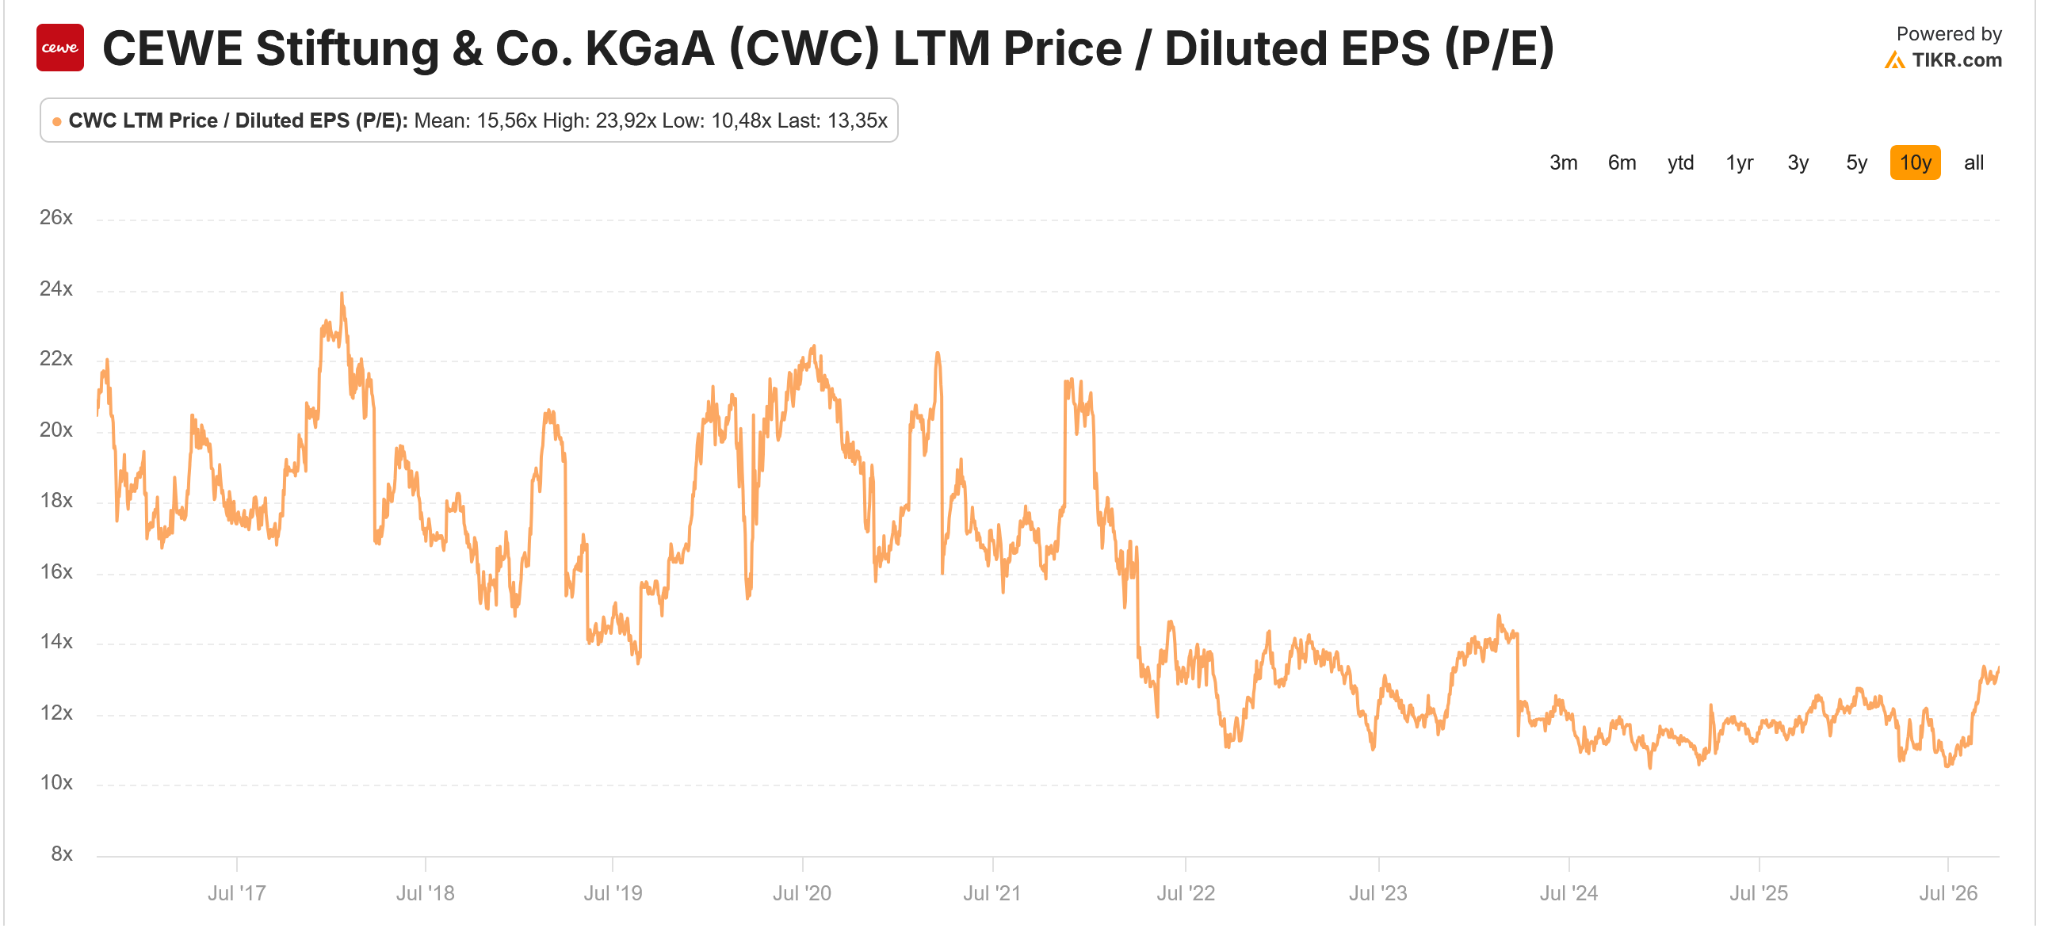
Based on trailing 12M P/E, the stock trades at around 13x P/E vs. an average of 15x:

Pro’s & Con’s

  • still cheap
  • profitable
  • no debt
  • 3% dividend yield
  • sale of unprofitable division

+/- some share buy backs

  • low growth in the last 3 years
  • super seasonal business, all in Q4
  • KGAA Stiftung
  • EBIT margins creeping down
  • Kodak Moments acquisition risky
  • Large exposure to the German/European consumer

Intermediate conclusion

Although I kind of like CEWE, at this stage I don’t see myself investing into the stock on a 3-5 year horizon,

Yes, it’s cheap, quite profitable and the stock price has just trended upwards. On the other hand, I do see the risk that the recent acquisition might not go so smoothly and I am also not sure about growth prospects after that one time bump from the acquisition.

If I would be in the mood for shorter term trades, I might set up a 3-6 month trade trying to ride the current momentum, but the high interest rates make me nervous.

I also need to manage my exposure in the portfolio to the European consumer to which I am exposed directly and indirectly through stocks like Sixt, Fielmann, Thermador, Italmobiliare etc.

Therefore, for the time being, I am not investing into CEWE but keep it on the watch list.Upfront remarks & Management summary:

This is not a deep dive but more like my “first round screening” of a potential interesting investment. In the past, I would have not necessarily published it if I didn’t invest. Going forward, I will now and then publish these “initial assessments” mainly in order to receive feedback from readers who might see it differently. So please give feedback if you see things different !!!

As a Management Summary, I did not invest. Although I like the company somehow, I could not build up the conviction for a 3-5 year investment case mainly due to recent slow growth and a somewhat risky acquisition. 

Fielmann Group – Will “Junior” be able to execute the 5 year plan once again ?

DISCLAIMER: This is not Investment Advice. PLEASE DO YOUR OWN RESEARCH !!!!

Soundtrack:

There were quite a few songs that fit the topic, but in the end I really like Disco so ”Sexy Eyes” from Dr. Hook is my favorite;

Dr. Hook – Sexy Eyes • TopPop

Editorial Notes on AI use:

I do use AI tools (Gemini, Claude, NotebookLM) extensively during the research but I write everything “by hand”. In some cases, I will however copy & paste a summary or result table from a query after checking that the content is plausible. But I will always explicitly mention if I do this explicitly.

Management Summary:

Fielmann Group, the majority family owned German optical retailer has seen a significant multiple compression over the past 10 years despite a very decent operational performance since the Covid lows.

Based on a credible 5 year plan laid out in 2025, Fielmann is attractively priced and if they continue to execute under the leadership of the second generation family CEO, the stock offers significant potential over the next 4-5 years.

For this high margin, high return on capital business with a rock solid balance sheet and strong cashflow generation,  the current valuation of ~15 NTM P/E and ~3,3% dividend yield looks attractive. 

And here is the full write-up:

Frosta AG – Defining their own Category the Hard Way

Disclaimer: This is not Investment advice. The stock discussed is very illiquid and trades at the unregulated market (Freiverkehr). If you want to buy this stock, work very carefully with strict limits. The author owns the stock and might buy/sell it without giving prior notice. And as always: PLEASE DO YOUR OWN RESEARCH !!

After having two (relatively) exciting stocks in the last two weeks with Rocket Internet and Innoscripta, I decided to tune down the exitement a little bit and focus on a very boring, family run German small cap this time. In order to not fall asleep, you might want to listen to the Soundtrack while reading:

Elevator Pitch:

This write-up is special in two ways. For one, I have privately bought the stock already a few months ago. Secondly, I base this write-up on another write-up from my friend Jon from abilitato.de. So please read that one before you read my “mini-writeup” where I only focus on a few specific aspects.

In a nutshell, Frosta is a boring, under-the-rader German family owned and run frozen Food company that does not do a lot of investor relations but runs a very convincing strategy focusing on additive-free ready made frozen meals. Inventing this category more than 20 years ago, the main Frosta brand is now growing with solid “mid teens” percentage rates p.a., has succesfully managed to enter and grow in neighbouring countries and with profitability that is steadily increasing. For the quality of the company and the potential growth prospects, the stock is still relatively cheap in my opinion at around 12×2025 P/E (ex net cash).

Here ist the write-up. Best read it after having a decent “Chicken Paella” from Frosta 😉

The German Mittelstand is maybe Down but not Out: Hermle AG – Hidden Automation Champion from the “Ländle”

As always with my longer write-ups, I will attach the full PDF below. In the post itself I will focus on the Exec summary, Pro’s and Con’s and the conclusion. And the Bonus Track of course at the end.

Executive Summary

Hermle AG is a typical “Hidden Champion” Mittelstand company from Southwestern Germany (Baden Wuerttemberg, the “Ländle”) that managed to carve out a very nice niche in 5- Axis CNC machines and connected production automation.  The company is able to earn industry leading EBIT margins (>20%) and Returns on Capital (>30%), has a Fortress Balance sheet and trades only at a relatively modest valuation of around 7,7x EV/EBIT.

The business is exposed to the economic cycle, but a combination of competitive advantages, a flexible cost base and a structural tailwind (Automation) make the stock attractive in the mid- to long term

Full PDF can be read & downloaded here:

Read more

Eurokai KGaA (ISIN DE0005706535) – Playing the “Time arbitrage game” with the possibly cheapest Port Stock in the World 

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!

Some reason for not reading this post:

  • You have already posted YTD Performance numbers on FinTwit
  • You don’t like capital intensive stocks
  • You don’t like cyclical stocks
  • You prefer stocks that have positive share price and/or fundamental momentum
  • You require short term catalysts/Share buy backs/activists etc.
  • You like simple businesses with simple structures
  • You think Germany/Italy/Europe is going down the drain anyway

In such a case, do yourself and myself a favor and move on.

Read more

My 22 (+1) investments for 2024

Following an annual tradition, by the end of the year, I review my portfolio by writing/updating very short summaries for each individual position.  16 of the 23 positions from last year are still in the portfolio and I have added 7 new positions. That turnover has been partially driven by exits/take-overs (Schaffner, Logistec) and by finding new ideas. A more comprehensive Performance review will follow in early January 2024.

A short user guide:
My preferred style of investing is a bottom up approach, focusing on 20-30 small/midcap stocks that in my opinion have a good return/risk profile over the next 3-5 (or more) years. Many of these stocks are not household names and are unlikely to make spectacular gains in any single year. Many of them look interesting only after the second or third glance and are rather boring, which is exactly what I am looking for. So if you are looking for a “Hot stock for 2024”, this post won’t help you much.

And always remember: THIS IS NOT INVESTMENT ADVICE. PLEASE DO YOUR OWN RESEARCH.

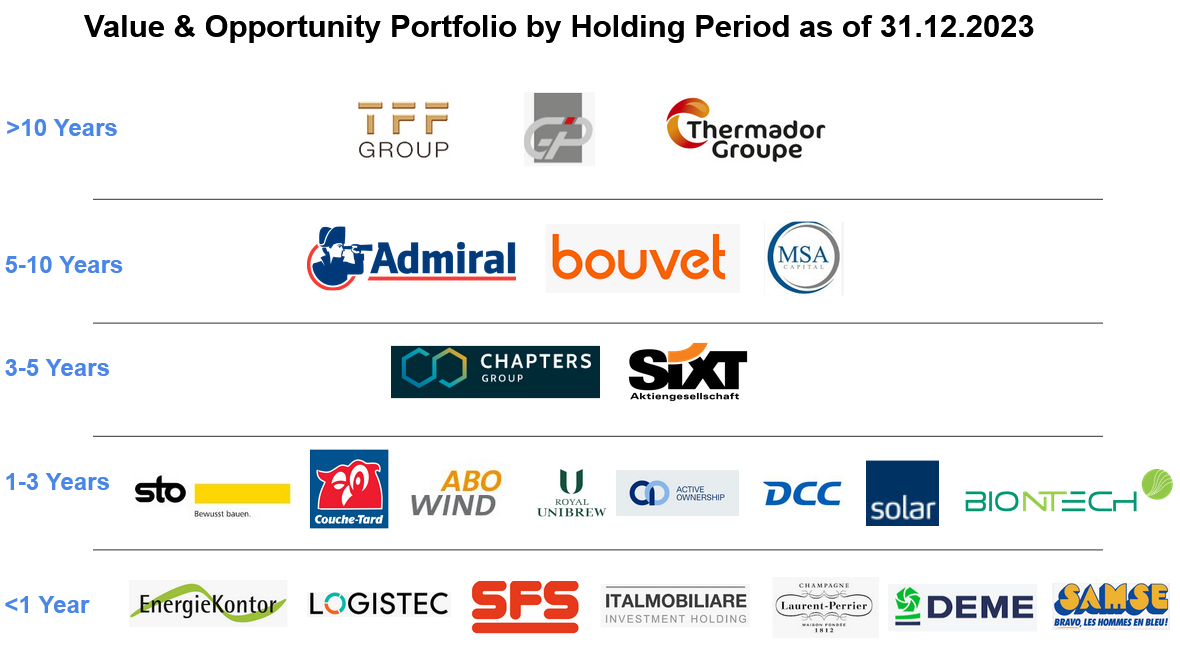
As a special service and to offer something “fresh”, I have created a new portfolio overview chart based on holding periods which I proudly present here:

The summaries of the previous years can be found here:

My 23 Investments for 2023
My 28 Investments for 2022
My 21 (+6) Investments for 2021
My 20 investments for 2020
My 22(+1) Investments for 2019
My 21 investments for 2018
My 27 investments for 2017
My 27 investments for 2016
My 28 investments for 2015
My 24 investments for 2014
My 22 investments for 2013

Let’s go:

1. TFF Group (Portfolio weight 7,4%, Holding period 13,0 years)

Read more

Samse Group (ISIN FR0000060071) – A Hidden French Compounder that is as exciting as watching Paint dry ?

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!

As in the past, due to the bad WordPress editor, I’ll post a summary here and attach the full write-up as PDF.

After teasing a new position in the Nabaltec “Post Mortem”, I proudly present the next (hopefully) super boring company for my boring portfolio.

SAMSE SA is a French company that distributes building materials to “professional” customers like contractors, craftsmen etc. It also has a smaller “Direct to consumer” DYI store segment, which represents around 20% of sales. Samse is active only in France and No. 2 after Saint Gobain, which, however is much bigger even only in this specific sector (2000 outlets vs. 350).

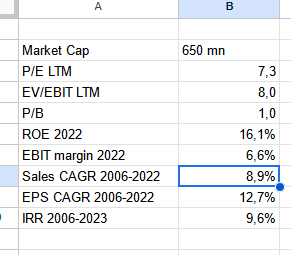
Here is an overview of relevant “KPIs” at a share price of 190 EUR (time of writing):

Read more

Italmobiliare (ISIN IT0005253205) – Buying “Italy’s Finest” for only 50 Cents on the Euro ?

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!

What better day to publish a post about an Italian company than Ferragosto, the Italian Public Holiday where virtually any Italian family is somewhere close to a beach and Italian offices only are staffed with the most junior person to take up the telefone in order to say: “No one here, please call next week/next month”.

With Italmobiliare, I fell deeply into a rabbit hole, which lead to a quite extensive analysis. Due to some problems with the WordPress editor, I wrote it with a different Editor and have attached the PDF with the full version. In the blog post I’ll focus on the executive summary, the Pro’s and Con’s and the return expectations. The rest of the gory details can be read in the attached PDF document.

Executive summary:

Italmobiliare (IM) is an Italian Holding company with a market cap of ~1 bn EUR that underwent 2 pivots in its 40 year history as a listed company. The first pivot, in the 1990s, from conglomerate to Cement (Italcementi) and then once again in 2017 after a 2 bn sale to Heidelberger into an Italy focused, “Quality-growth small/mid cap PE” style investment company.

What makes the company very attractive to me, is a very interesting portfolio (including at least two potential “Super Star” holdings), decent value creation, good strategy/transparency  and especially a 50% Discount to NAV. 

Read more

Mikron Group AG – Super Cheap (EV/EBIT ~4) and +33% EBIt 6M 2023- what is not to like ?

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!

Spoiler: If you are short on time: I did not buy a position here. No need to read everything.

Mikron is a company that I had on my (passive) radar since my “All Swiss shares” series some years ago (since I passed on it, it made around +100%, so keep this in mind for the rest of the post). It is a Swiss based machinery manufacturer with a market cap of 200 mn CHF and has some connection to SFS (SFS is a client, same Chairman in the past).

These were the main items that motivated me to looks deeper into Mikron this time:

+ currently very (very !!) cheap (P/E 7,5, EV/EBIT 3,5)
+ currently VERY good business momentum (6M 2023: Sales +22%, EBIT +33%)
+ better customer/product mix than in the past
+ Rock solid balance sheet (100 mn CHF cash vs 200 mn CHF market cap)
+ good share price momentum

Read more

« Older Entries