Category Archives: Capital allocation

“Freedom Insulation” – Follow up and Basket Update (Sto, Steico)

Disclaimer: This is not investment advice. PLEASE DO YOU OWN RESEARCH !!!

Some days ago, I made the case for a significant increase in demand for insulation in Europe for the next several years. In this post, I want to dig a little bit deeper into the main listed players and which I find more interesting. In general, even only for the German speaking region there are many companies that offer insulation, among them very large, diversified groups such as BASF, Dow Chemical and St. Gobain.

However, the following listed companies are those who do the majority of sales in insulation to my knowledge:

Kingspan, Irleand/UK
Rockwool, Denmark
Recticel, Belgium
Steico, Germany
Sto SE, Germany

Sto, Rockwool and Recticel are already in my portfolio with relatively small weights.

Before jumping into the companies, I have compiled a table with a few KPIs that i find interesting. One quick coment upfront: As Recticel is undergoing a signifcant transformation, their numbers are curently not comparable.
Read more

Schaffner Group AG (ISIN CH0009062099) – Is this “Meier & Tobler 2.0” ?

Disclaimer: This is not Investment advice. PLEASE DO YOUR OWN RESEARCH !!

Summary:

If you would ask me about the most boring stock of my generally very boring portfolio, I would possibly name Schaffner Group. I had bought a first position back in 2021 during my “All Swiss Stocks” series.

However, I have never written a more detailed write-up despit my annual summaries (2021/2022 , 2022/2023), maybe becasue I always got bored when I started writing about it ? Over time I added to the position and after the most recent 6 months numbers, I decided to increase into a full position. Time to explain the investment case a little bit better.

  1. The Company – Transformation

Read more

SFS Group AG (ISIN CH0239229302) – Super boring but sexy “Hidden Champion” from Switzerland

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!!!

Summary:

In my relentless effort to create the most boring and unremarkable stock portfolio imaginable, I think I identified an ideal  candidate with SFS Group from Switzerland.  Despite having a market cap of ~4 bn CHF, this majority family-owned company is not very well known and its products and B2B business model look similarily unremarkable.

The company doesn’t have an easily identifiable moat, doesn’t pay high dividends or buys back stock, is not super cheap and also not super profitable, doesn’t grow like crazy and doesn’t have sexy products that one can see in the supermarket.

Nevertheless I do think it is an great addtion to my portfolio as it is attractively priced and both, the business as well as the management are of high (Swiss) quality. Based on my own estimates, the stock trades at a PE of ~12x for 2023, despite having delivered EPS growth in EUR of around 15% p.a. since its IPO in 2014 and maintaing double digit EBIT margins across the cycle.

Read more

Hannover Re: An overlooked Reinsurance Compounder & Comparison with Munich Re

Spoiler: This rather long post contains no actionable investment ideas.

Background:

Hannover Re is a stock that for some reason I have ignored for some time although I consider Insurance stocks as part of my circle of competence. Why did I ignore them ? I was always put off from the ownership structure. Hannover Re is majority owned by Talanx, which itself is also listed. Talanx again is owned ~80% bei HDI, which is owned by …I don’t know.

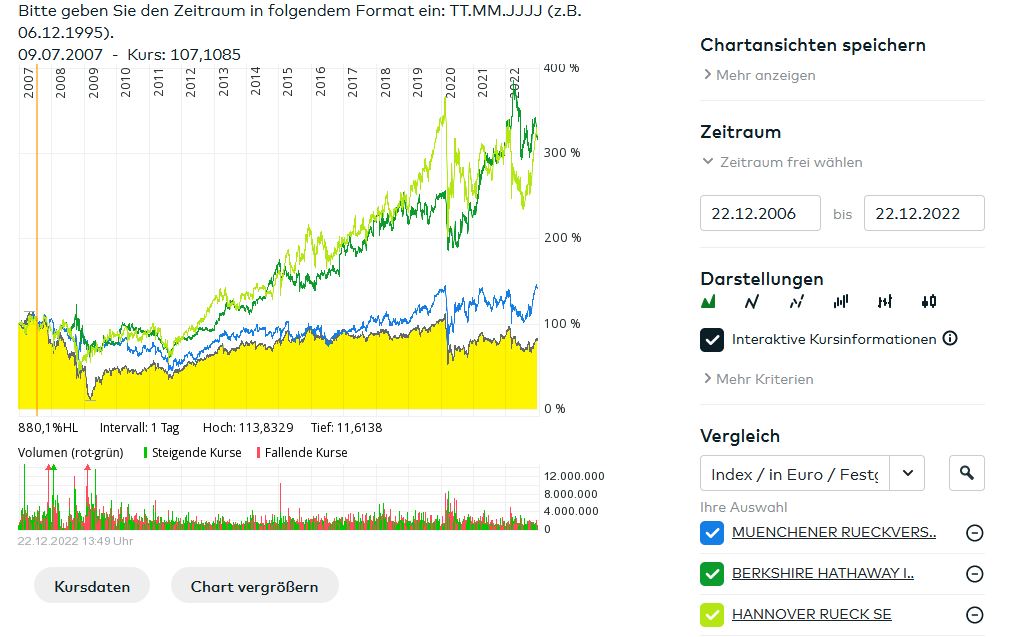
Looking at the chart, I should have considered them earlier: Over the past 15 years, Hannover outperformed the larger and better known peers like Munich Re and Swiss Re by a wide margin and ties with Berkshire (before FX):

hannover 15 years

This is very interesting, considering that Hannover Re is only the No. 3 global Reinsurer and Berkshire only number 5. Absolute size doesn’t seem the drivig factor for shareholder returns in the Reinsurance industry.

Deep dive Comparison: Hannover Re vs. Munich Re

Read more

DCC Plc (ISIN IE0002424939) – Extremely unsexy Business meets sexy Track Record at a super sexy Valuation

Disclaimer: This is not investment advice. PLEASE DO YOUR ON RESEARCH !!

As this post has become quite long, here is the Elevator pitch:

DCC Ltd, a 4,3 bn market cap UK listed, Ireland based company at a first look like a very boring, unremarkable collection of very boring distribution businesses. A second (or third) glance however, reveals a very stable , well managed distribution company that has been compounding EPS at double digit growth rates for the last 28 years and can be bought for a very modest valuation of ~10x earnings. The company clearly faces some challenges but this might be more than outweighed by very good capital allocation, company culture and growth opportunities.

  1. History

DCC has a very interesting history. It was founded actually as some kind of Venture Capital company in 1976 in Ireland and was led for 32 ears by founder Jim Flavin. After turning into an operating company, DCC went public in 1994. Over the years they acquired a lot of businesses, many of those where distribution businesses from oil majors but also in other areas such as health care and technology components.

What I find extremely impressive is their track record since they listed in 1994 and is available in each annual report:

Read more

Royal Unibrew (ISIN DK0060634707) – A High Quality Beverage Compounder at a reasonable price ?

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!

The company:

Royal Unibrew logo

Royal Unibrew is a Danish Beverage company that I “discovered” during my journey through all Danish shares some weeks ago (too expensive back then but “watch”). I had also seen them some months ago in the Profitlich&Schmidlin portfolio.

The company is mostly active in Scandinavia and the Baltics where they have offerings in all areas (including a contribution agreement with Pepsi), whereas in some countries (France, Germany, Italy), they are running a focused niche strategy. Despite the name, Beer is only around 35% of their offerings (as of 2021), the other 65% are mostly non-alcoholic drinks from soft drinks to water and energy drinks.

Read more

Inflation vs. Pricing Power for Chemical companies & Nabaltec follow up (ADD)

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!

Inflation & Pricing power

One of the obvious strategies for for investors in an inflationary environment is to pick companies that have “Pricing power”. Pricing power means that companies should be able to raise prices at least as quickly as costs rise.

Now one could try to do some deep thinking if and how different business models react to inflation. As I am a more “hands on” guy, my solution is to look at actual numbers and then try to draw my conclusion.

For any company that is producing material goods, the best indicator for pricing power in my opinion is Gross profit, i.e. the difference between selling price of a product minus the direct costs to produce them.

A company with pricing power should keep the gross margin or ideally even improve gross margins in an inflationary environment.

Read more

Protector Forsikring ASA – The Scandinavian “Baby Markel/Berkshire” ?

The company:

Protector Forsikring ASA is a name that came up more often in my “stream”. It is a Norwegian “Challenger” Insurance company founded in 2007 (and IPOed in 2008) that has been growing nicely over the past years and doesn’t look expensive.

The stock price has been quite volatile but recently the stock has reached new highs and long time shareholders should be quite happy:

Protector

The high level financial indicators look very attractive: A relatively Ok valuation with an impressive ROE:

Read more

Gaztransport & Technigaz (GTT) – welcome back !!

Background:

Gaztransport & Technigaz is a company that I had looked at in early 2016 and most of what I have written back then still applies:

Imagine you could invest into a company with the following characteristics:

– Global market leader with 70-90% market share (95% new built)
– Net margins after tax of 50% or more
– business protected by patents
– almost no capital requirement, negative working capital
– a potentially huge growth opportunity
– conservative balance sheet (no debt) and “OK” management

Back then, I found the stock initially too expensive at EUR 34 per share, however I invested then at around 22 EUR but sold after a quick gain at around 31 EUR.

What did happen since then ?

Looking at the chart, I was clearly underestimating the value of the stock by a wide margin as the stock more than tripled until early 2021:

Read more

Nabaltec AG – Boring Old Economy Dinosaur or “Hidden Champion” Electrification beneficiary ?

Disclaimer: This is not investment advice. PLEASE DO YOU OWN RESEARCH !!!!

The company:

naba logo

Nabaltec is not a fancy Biotech company as the name might indicate, but a rather “old economy” Specialty Chemical company focusing on Aluminium-oxide based materials, located in the middle of nowhere in my home state Bavaria. This  typical “German Mittelstand” company had its IPO in 2006, and was created 1996  as management buy-out of a production facility from VAW AG. The beginnings of the plant as such seems to have been built in 1938 and looks like this:

Read more

« Older Entries Recent Entries »