CEWE Group CMD – More potential upside than I thought
DISCLAIMER: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!
Background/Follow up:
When I wrote the initial post about CEWE a few days ago, I didn’t know that CEWE actually held a Capital Markets Day for selected investors on the very same day that I was publishing my post. They didn’t disclose it on their Website or IR calendar either.
Anyway, in the meantime, the slides are online.
On the capital markets day they presented more background on the Kodak acquisition. In a nutshell, I can now better understand the rationale and see it as less opportunistic but more strategic than without that information.
I think there are clearly some risks with the Kodak Moments acquisition, but on the other hand, there seems to be also a plausible path for some extra growth on top of the rather slow growth in the past few years.
Here are a few interesting snippets:
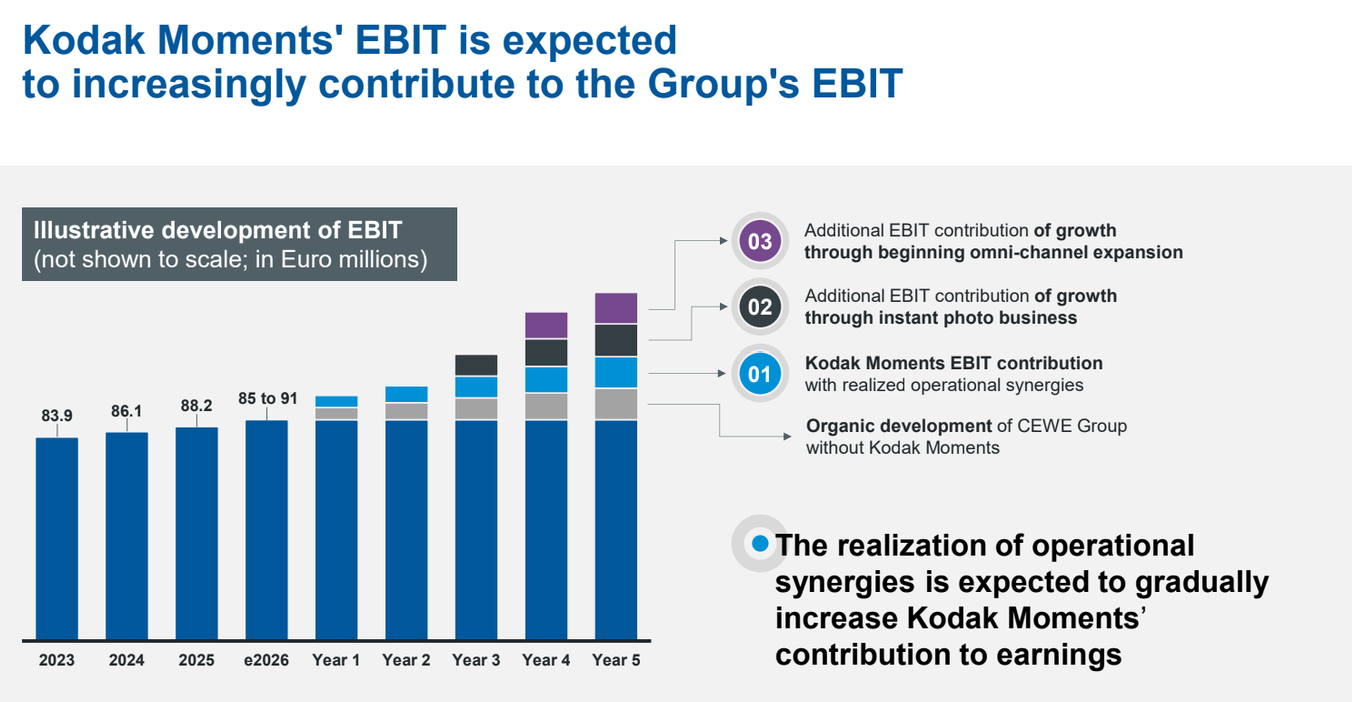
Although there are no actual numbers, they project EBIT growth that in the first 2 years is double the organic run rate and up to almost 3x in year 5. As organic growth in the last years was more like 3-4%, this implies growth rates of 6-10% for the next 5 years which would of course be really great.
If growth would actually accelerate like this, then there is also a decent chance that the stock might get back to historical valuation ranges. So in the upside case, there is potentially much more upside than I thought initially.
One detail they seem to have mentioned only verbally is that Kodak Moments currently only charges around 50% per printed picture than CEWE. It seems that Kodak’s quality is also lower, but this is clearly a relatively simple lever for CEWE to increase prices (and quality) up to CEWE’s levels.
They also point toward some risk, where the regulatory approvals might be the most relevant ones:
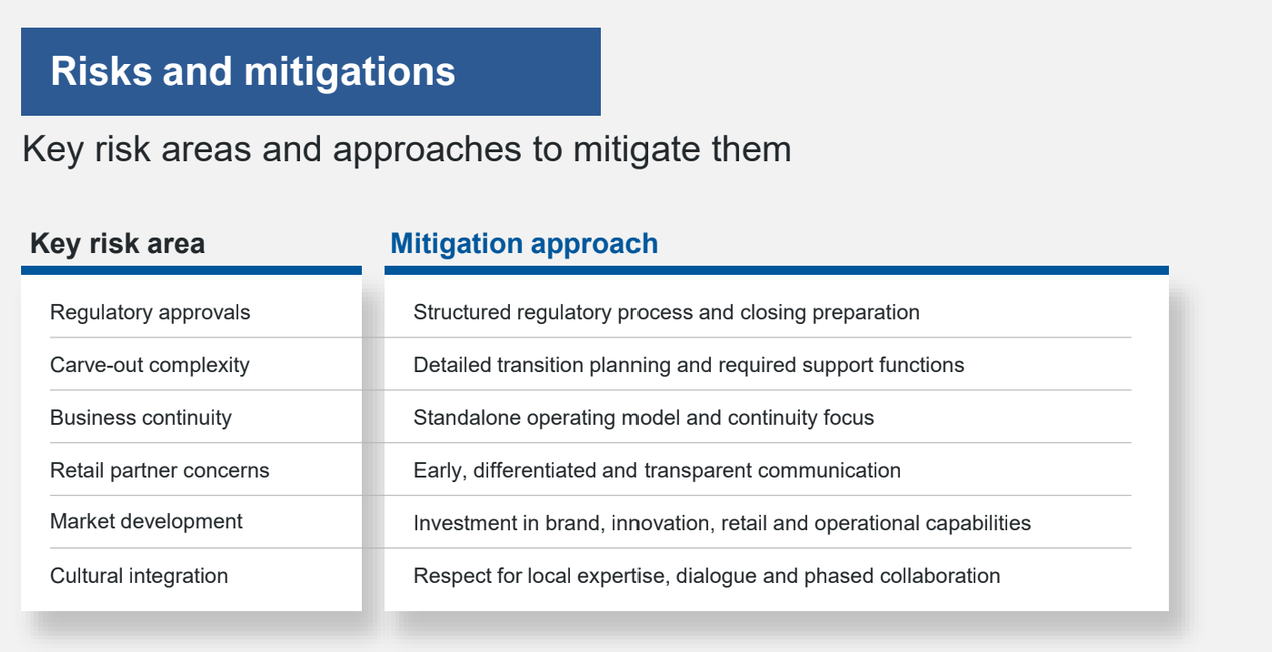
From previous reports one can estimate that ~40% of Kodak Moment’s business is actually from Germany.
The attractiveness of the instant photo kiosk business
Another aspect that seems to have been mentioned in the call is that the “instant photo” business as such has been growing nicely within CEWE already. I always thought that only the online photo books were the growth driver, but with this information, the acquisition could make even more sense.
I did a little background research on these photo kiosks and it seems that they fulfil quite an interesting niche for customers. We shoot more and more digital pictures and it seems that from time to time, people have the urge to print out pictures rather today or tomorrow than to wait 4-5 days and uploading them online.
Modern Photo kiosks often offer additional formats like larger prints or even more sophisticated Greeting card or invitation card formats.
On my past visits to a dm or Rossmann, I always checked on the photo kiosks and I was surprised how busy they are at any time of the day. Interestingly, I have seen branches where CEWE stations were next to Kodak stations in the same store.
From the perspective of the drugstores, these photo kiosks seem to be helping to draw customers into the store who might then also purchase something else. So these photo kiosks seem to look like a win-win. It would be interesting to know how the revenue sharing looks between Rewe/Kodak and the drugstores.
Some other aspects of CEWE
Governance/Incentivation
As a KGaA, the Governance is different to a normal “AG”. Effectively, common shareholders have no say who runs the company, this is solely determined by the “Komplementär”, in this case the foundation of the family that owns around 30% of the shares.
Therefore it is important to understand how Management is incentivized. In CEWE’s case, the variable component of the Management’s salary is relatively small and almost exclusively tied to EBT development. So no per share or Return on Capital measures.
There is a share option program but the amounts are rather insignificant.
From that perspective, incentives are not optimal. Interestingly, they still buy back some shares and report ROCE, but the variable component of the Board’s compensation really only depends on absolute EBT.
Share price momentum
Although it is not a criteria per se, the stock has positive Momentum. Looking at the long term chart, we can see that it is still below the ATH from COVID, bt it has been breaking out a little from a trading range recently:
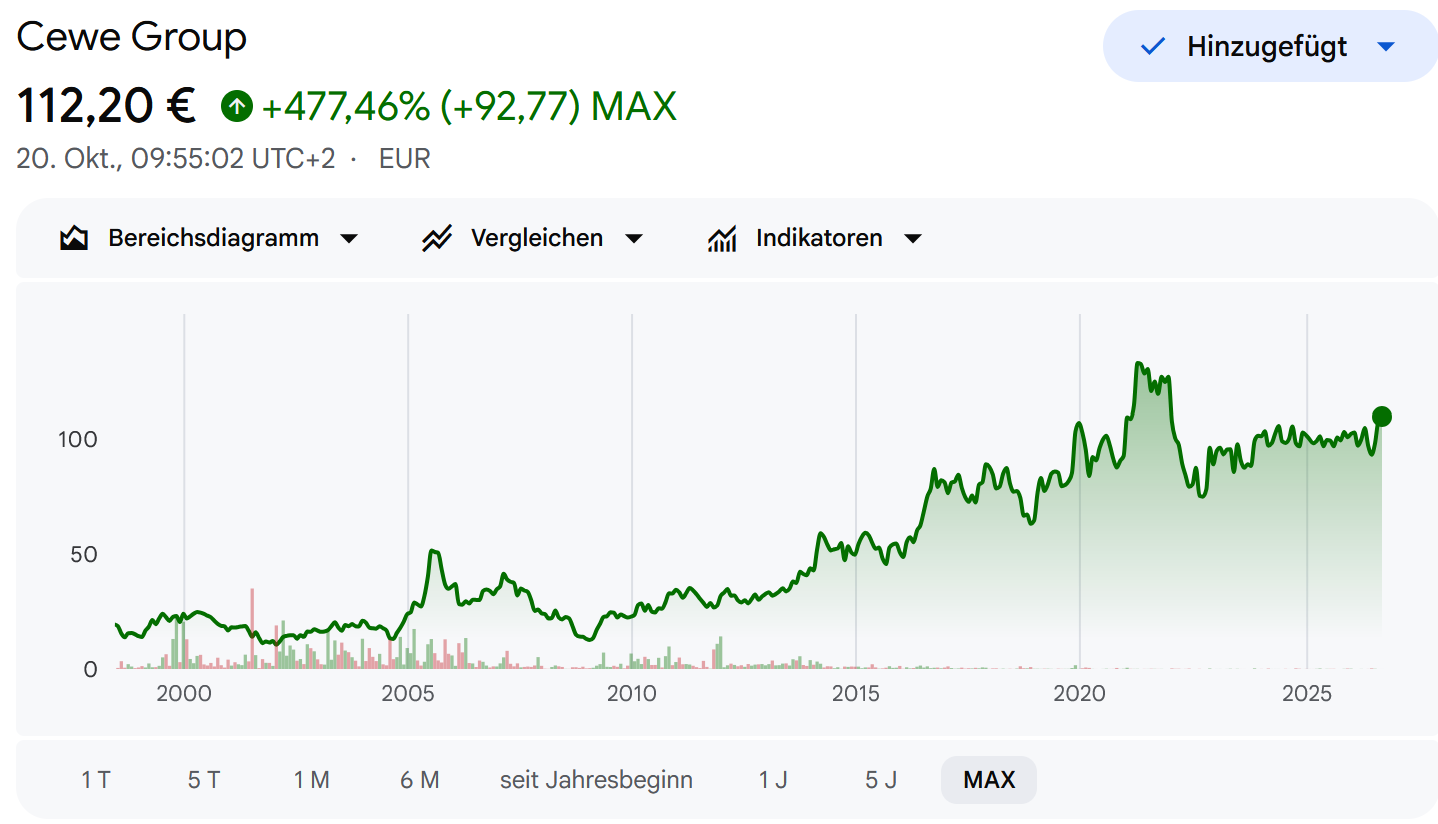
In my screening model, the overall score at the moment is quite good, putting CEWE fromly into the top 10 of stocks that I monitor.
Summary & conclusion
Following the CMD material, I have become more optimistic about a potential longer lasting growth runway following the Kodak Moments Acquisition.
As mentioned above, I now better understand the motives and think that there is a potential for some additional growth if they execute that acquisition well.
I therefore decided to allocate 3% of the portfolio into CEWE at the current price of ~112 EUR per share. My expected investment return for this will be somewhere between 40-50% including the dividend yield, buybacks and maybe a little valuation uplift over the next 2-3 years. This is clearly not exceptionally high, but I think the downside is also relatively well protected at less than 9x EV/EBIT.
Due to the Governance topic (KGaA) and suboptimal Management incentives, I will most likely not increase the position much above the current level. For a full position, I would need better scores on that aspect.
The next milestones will be as every year, the result of the all important Q4 and then in 2027 the successful closing of the Kodak moments transaction.


Nice Update
Thank you.