Wise Plc – Short update after one year
1 year since investing/writing
A little bit more than a year ago, I wrote up and invested into Wise Plc. In general, I do think it makes sense to review an investment a little bit more “formally” after one year which so far, I haven’t done on a regular basis.
The investment thesis back then was that Wise is a fast growing specialist payment/remittance company that also had a kind of short term catalyst in the form of an additional US listing.
After around 1 year, Wise doesn’t look like a big winner and the US listing turned out to be a doozie after a short run up just before the listing:
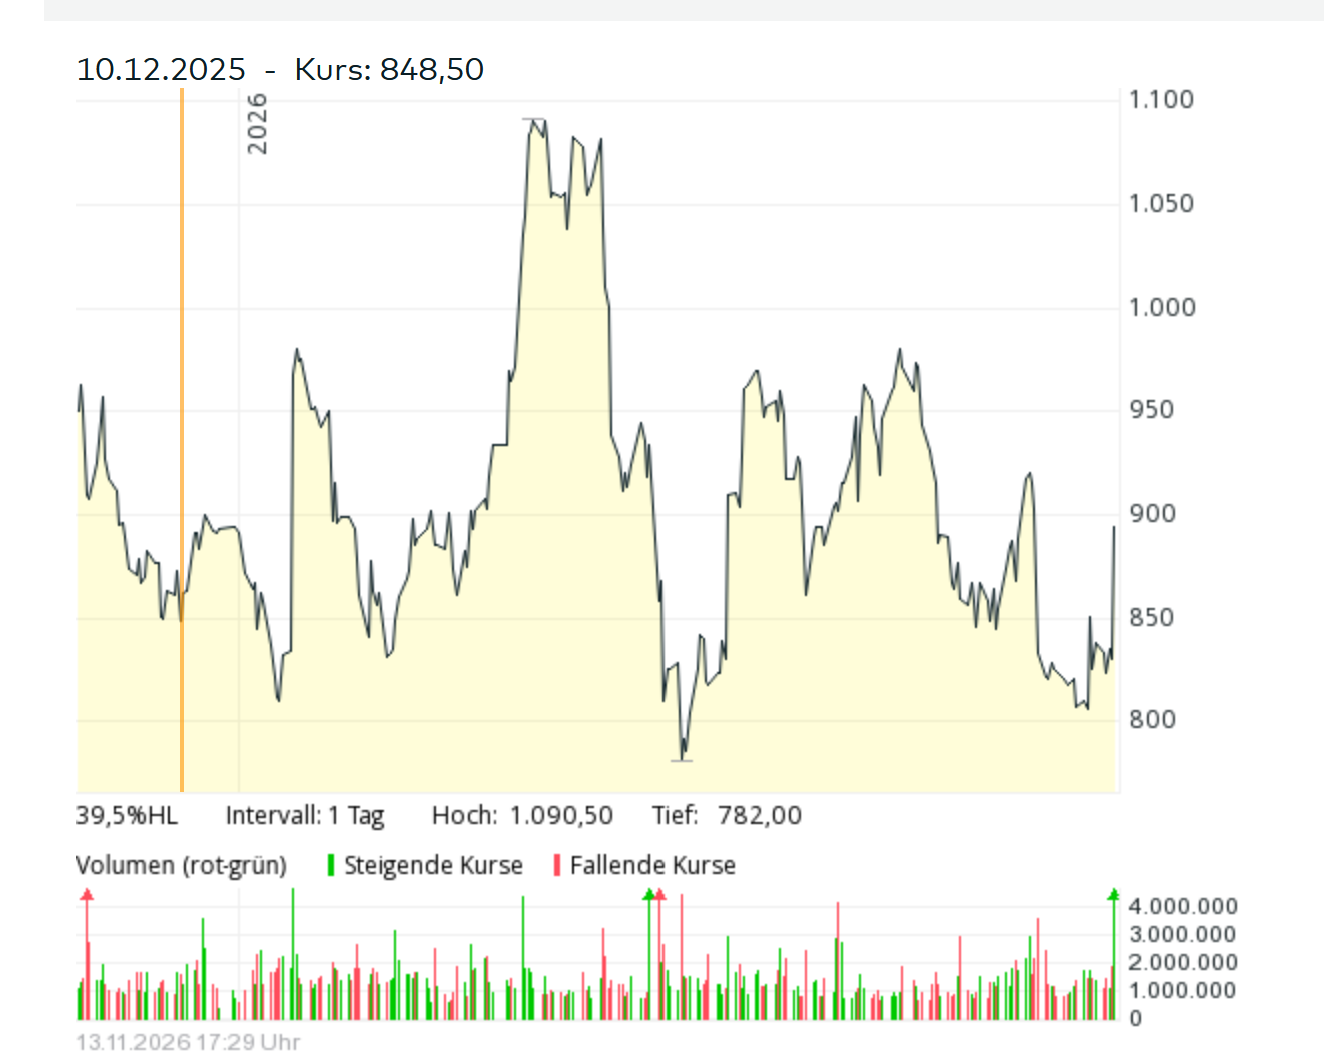
The Half year 2027 numbers:
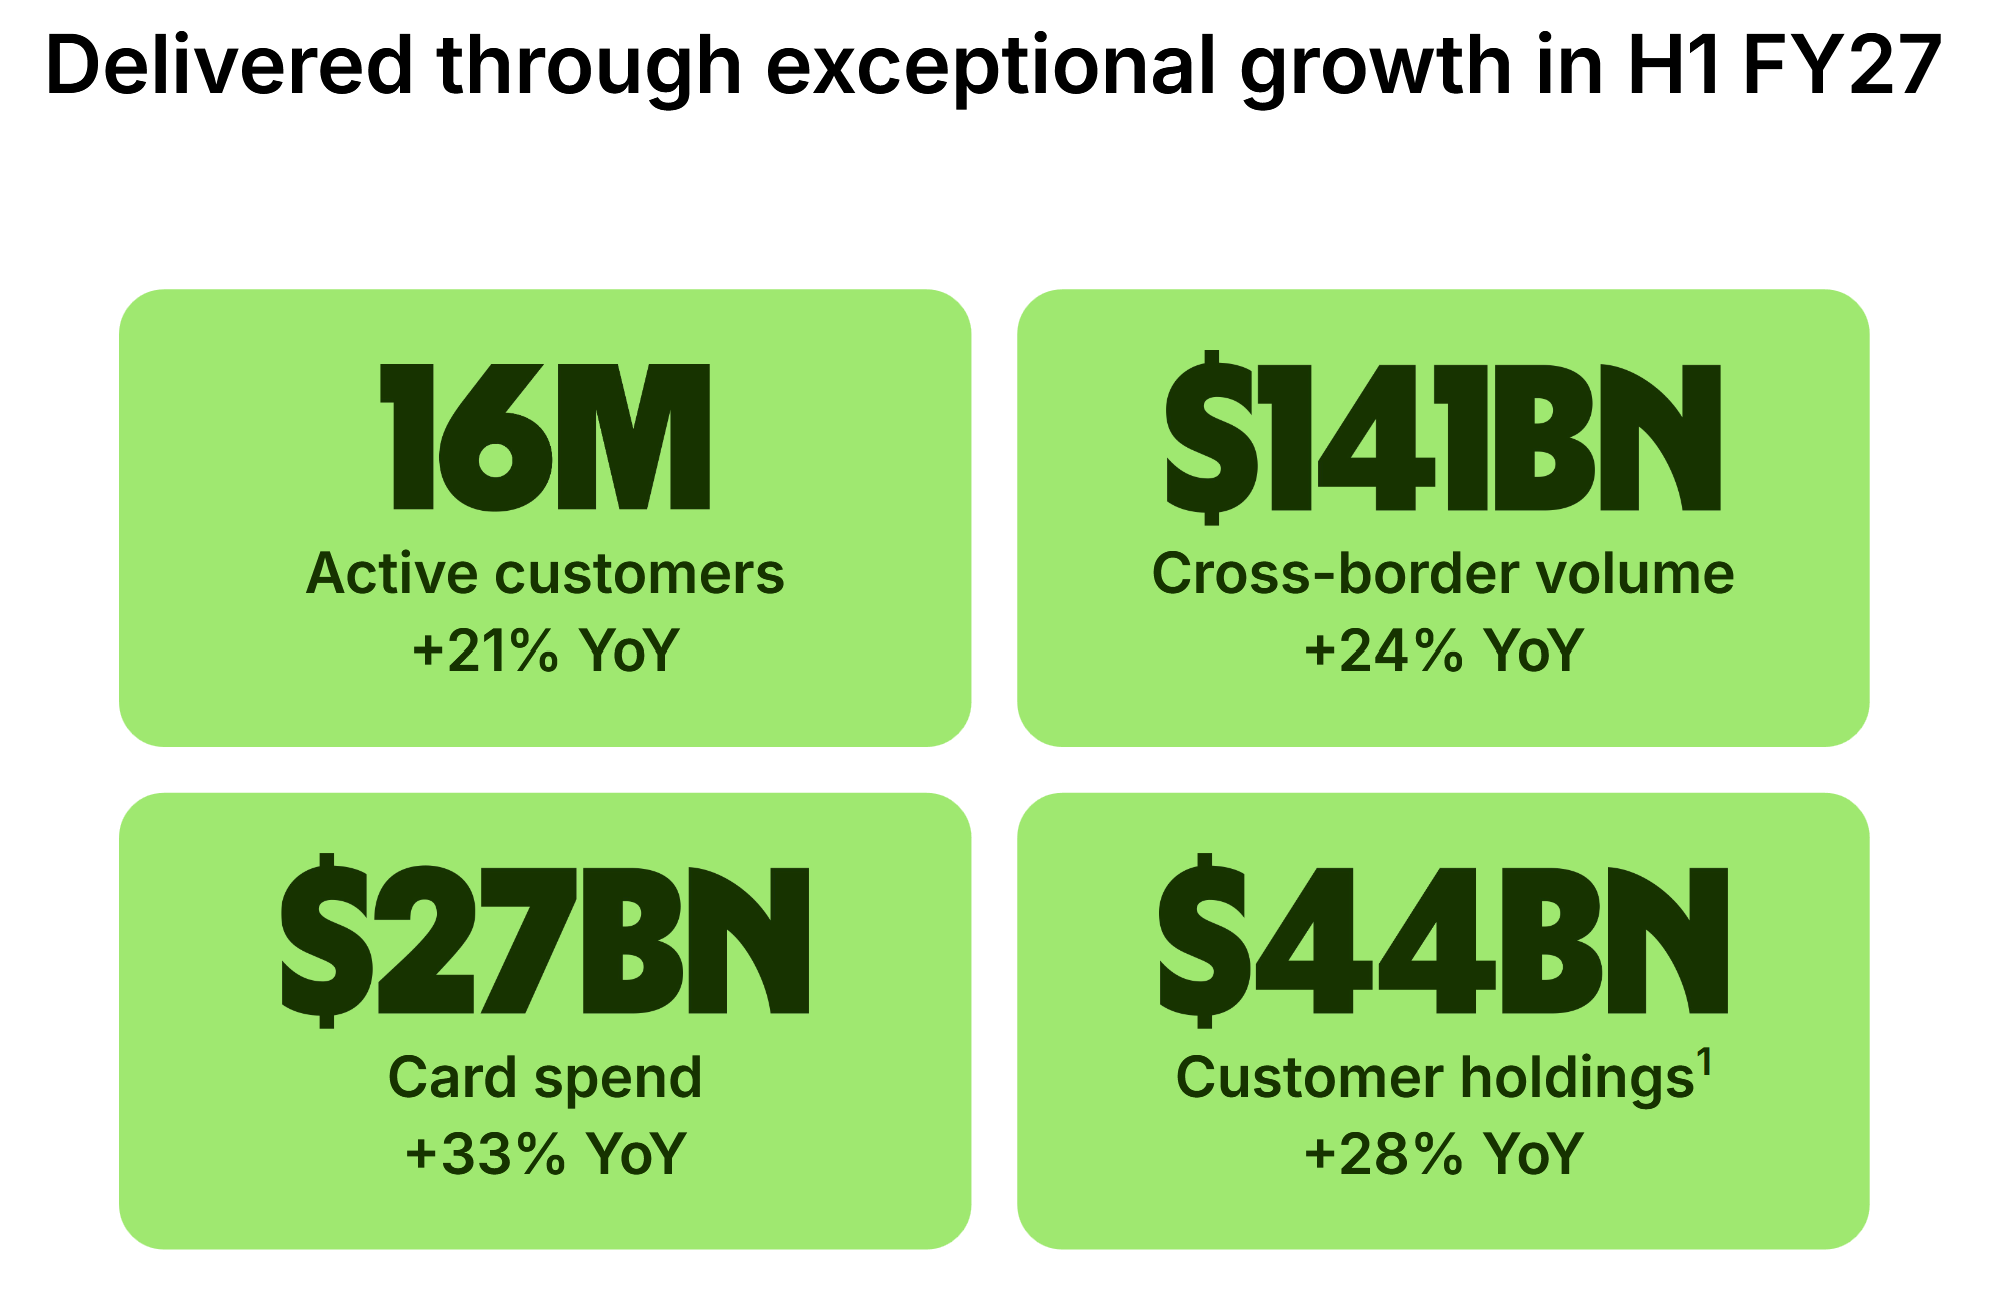
Business has done quite well. Yesterday, Wise published official half year numbers for their FY 2027. Customers, deposits, volumes are all up between 21-33%:
Guidance for the full year was decent, despite significant investments into the business:
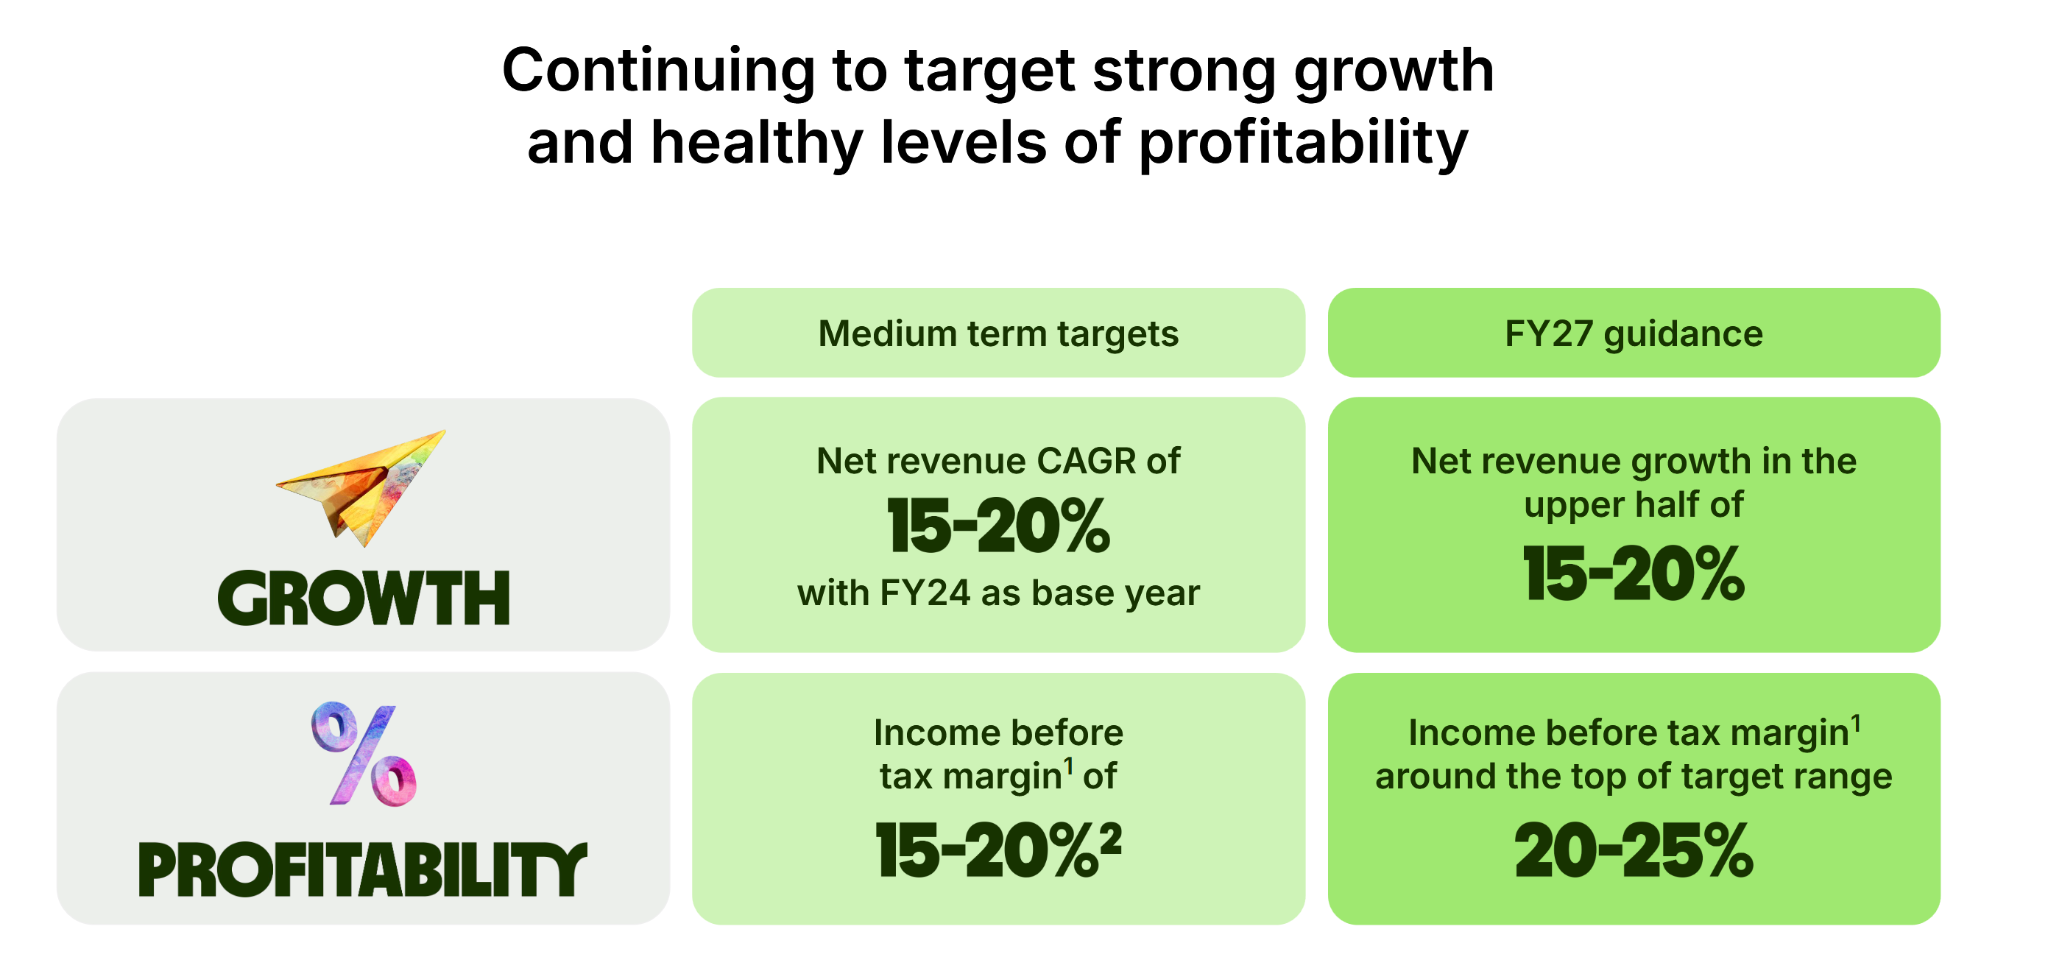
If we assume revenue growth would be 20% and EBT is 25%, I would actually end up with an EPS of 0,56 GBP or an P/E of 16,2 in a positive case. If we assume 0,50 GBP EPS in the mid case, the P/E would be ~18. Which is kind of OK.
However, if we look at the actual net income development, we can see that operating costs increased significantly quicker in the first 6M than revenue which leads to an “only” single digit EPS increase despite a share buyback program:
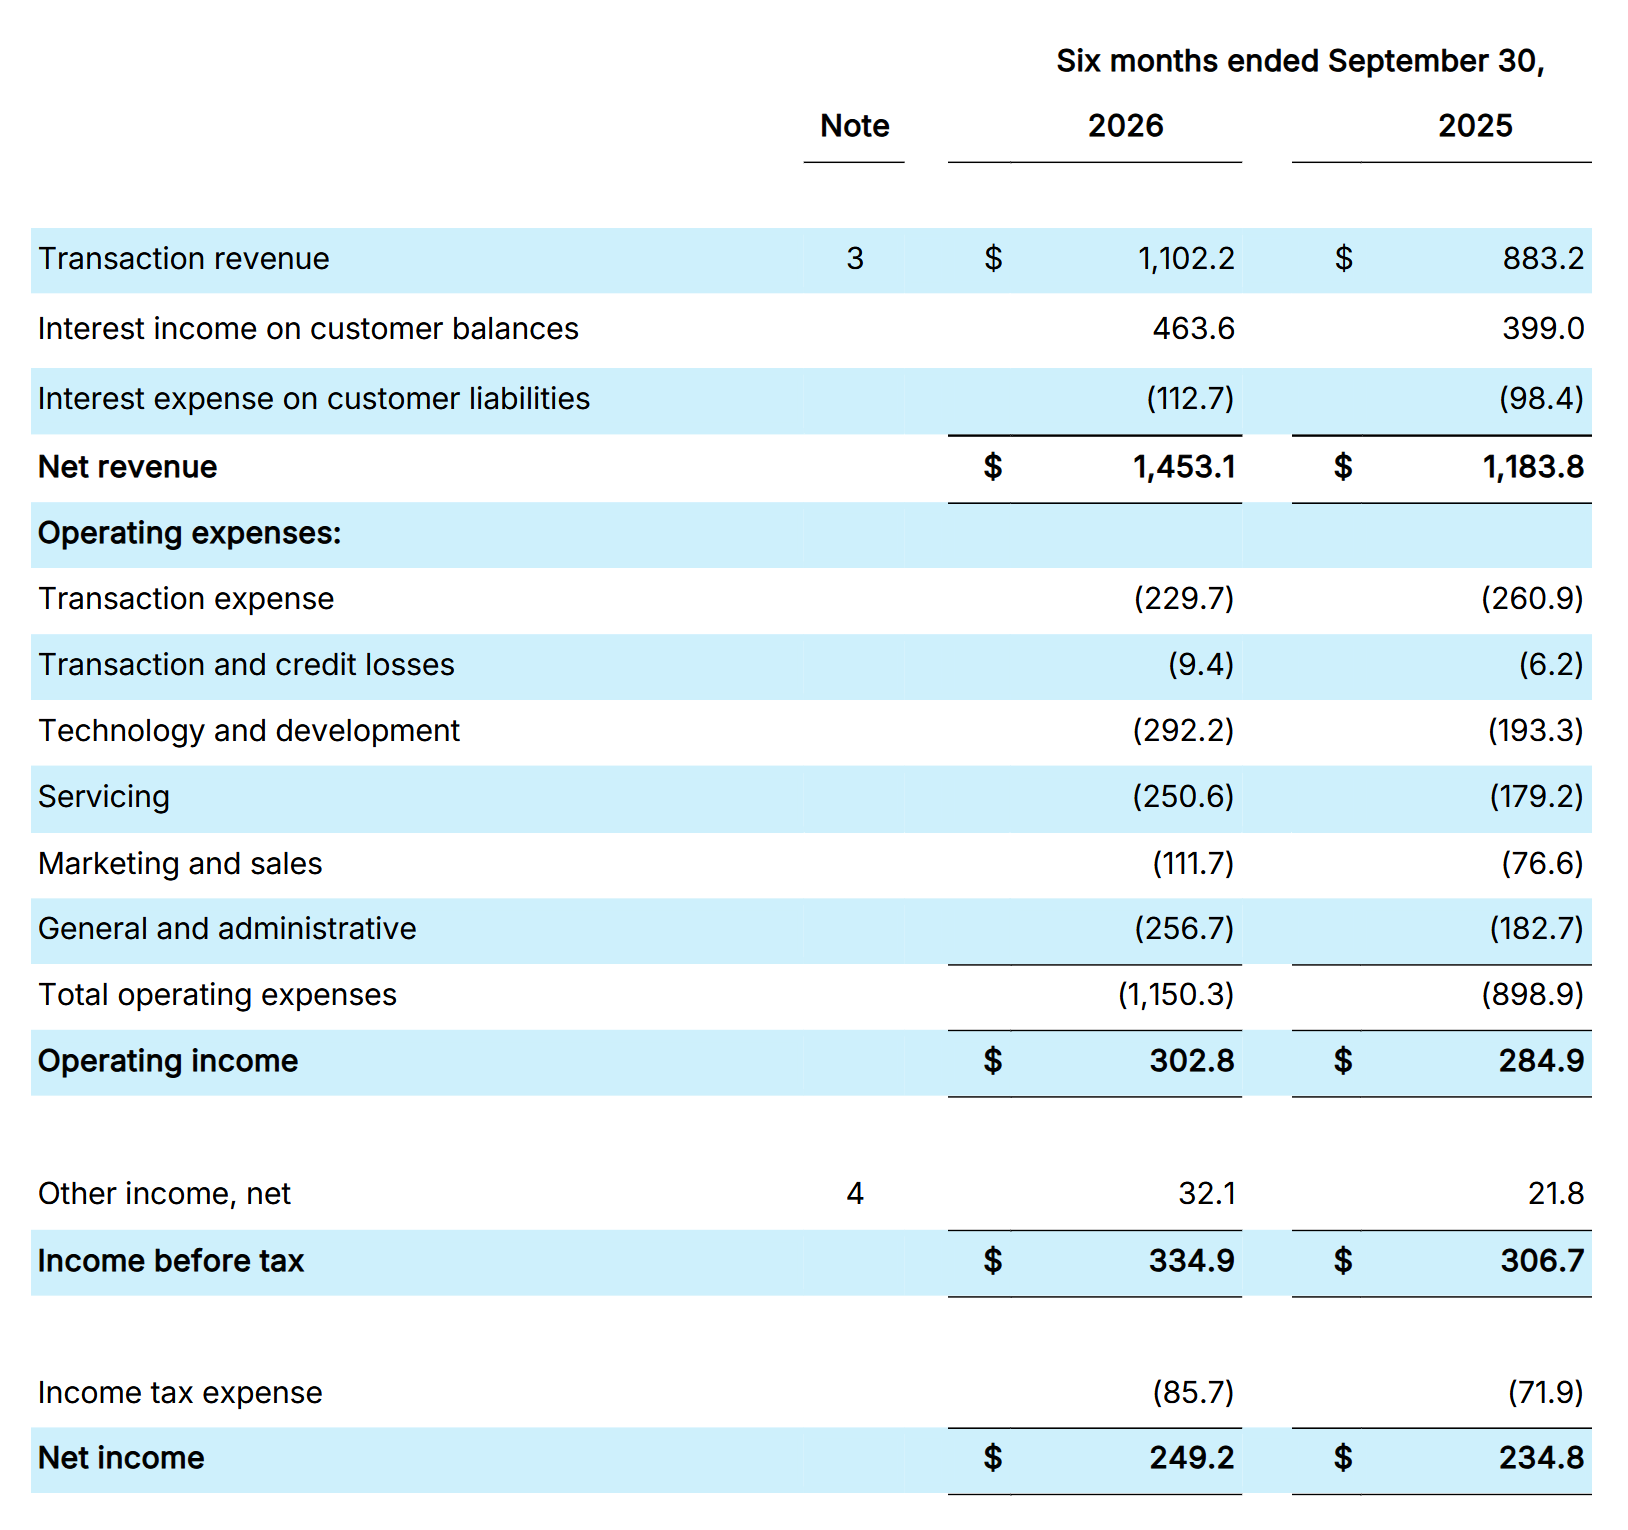
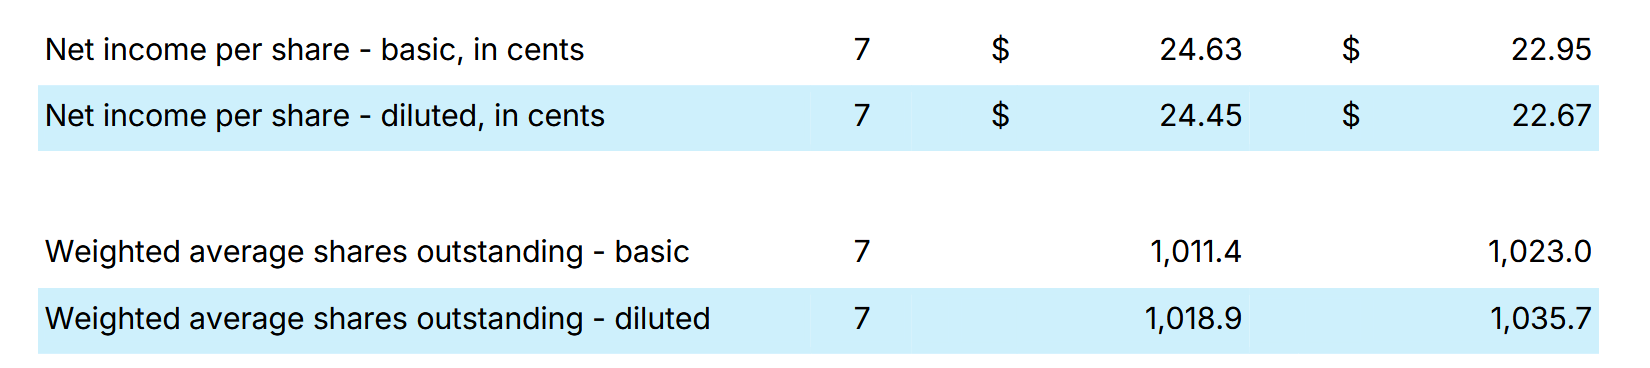
That’s only an 8% EPS increase which, compared to the headline number looks quite slim.
My French intern also pointed out that last year’s first half had a negative one-off charge of ~28 mn for transaction costsOn the other hand, there also seems to have been a 15 mn USD one off for the US listing.
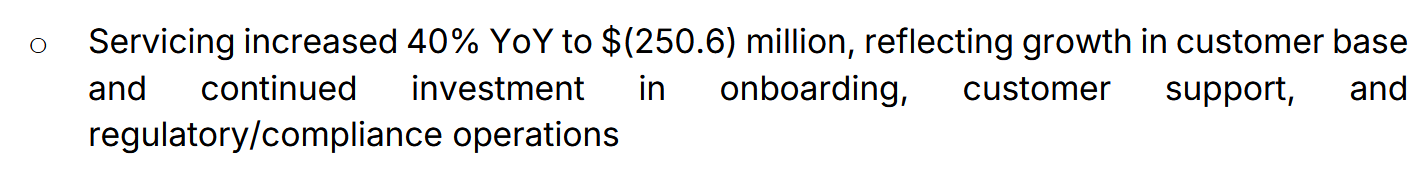
What is especially surprising in my opinion are the pretty drastic increases in “Servicing” and “G&A”. These two categories do not necessarily look like investments in contrast to technology & Marketing and sales. As we see later, the increase in servicing costs seems to be driven by increased compliance cost, whereas the increase of G&A was attributed to “Compliance costs with the US listing”:

Another point to watch is the Tech spend. Increasing the tech spend by 51% is very significant and a little bit puzzling, as many other players claim that using LLMs (Claude Code &Co) is increasing productivity dramatically. They mention that they shipped much more updates, but overall, there doesn’t seem to be a lot of scaling at the moment. Maybe this is by design, maybe not.
Multiple compression risk has realized
As mentioned above, Wise has now become significantly cheaper with the mid case p/E of around 18x. What we have seen now is clearly multiple compression, which I mentioned as top risk in my write-up back then.
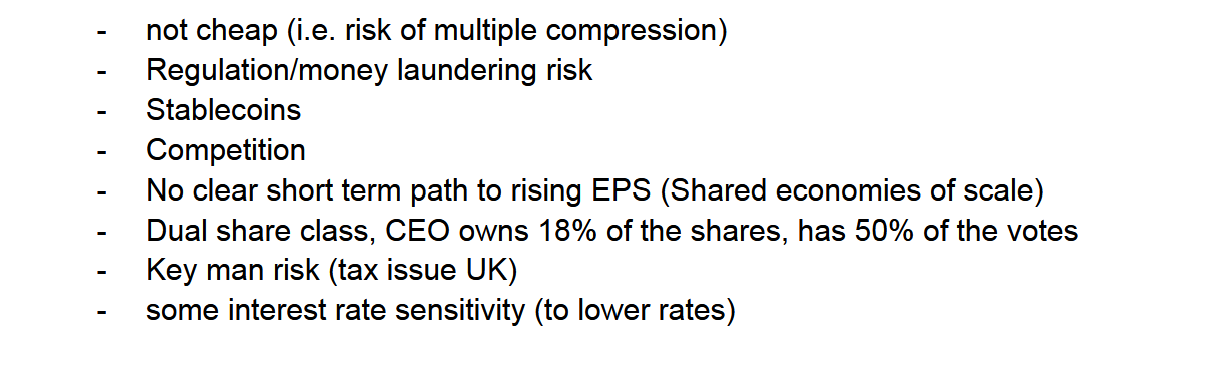
Potential explanations for the rather disappointing performance
So what were the reasons for that mediocre share price performance despite a slightly disappointing EPS development ? In my opinion, these three factors negatively affected the share price:
- The EU fraud investigation
- the non-approval of the US Banking license
- the relatively disappointing development of the whole payment sector
1) I wrote about that incident some months ago. The good news is that this has been resolved.
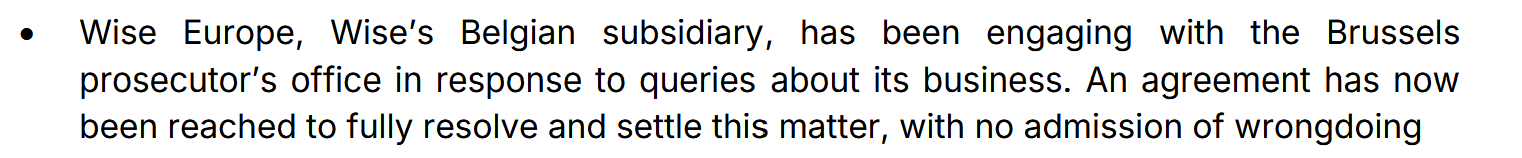
The not so good news is that this seems to have driven up costs especially in the “servicing” costs:
My French intern also mentioned that initially there were two streams: An investigation by the Belgium prosecutor and a process started by the National Bank of Belgium. It is not clear if the second part is also resolved.
2) There is no news on the US banking license. They plan to re-apply but we don’t know if they made any progress. Interestingly however they spoke of winning to major US banks as clients for the “infrastructure” business for which they don’t need the banking license.
3) Peers:
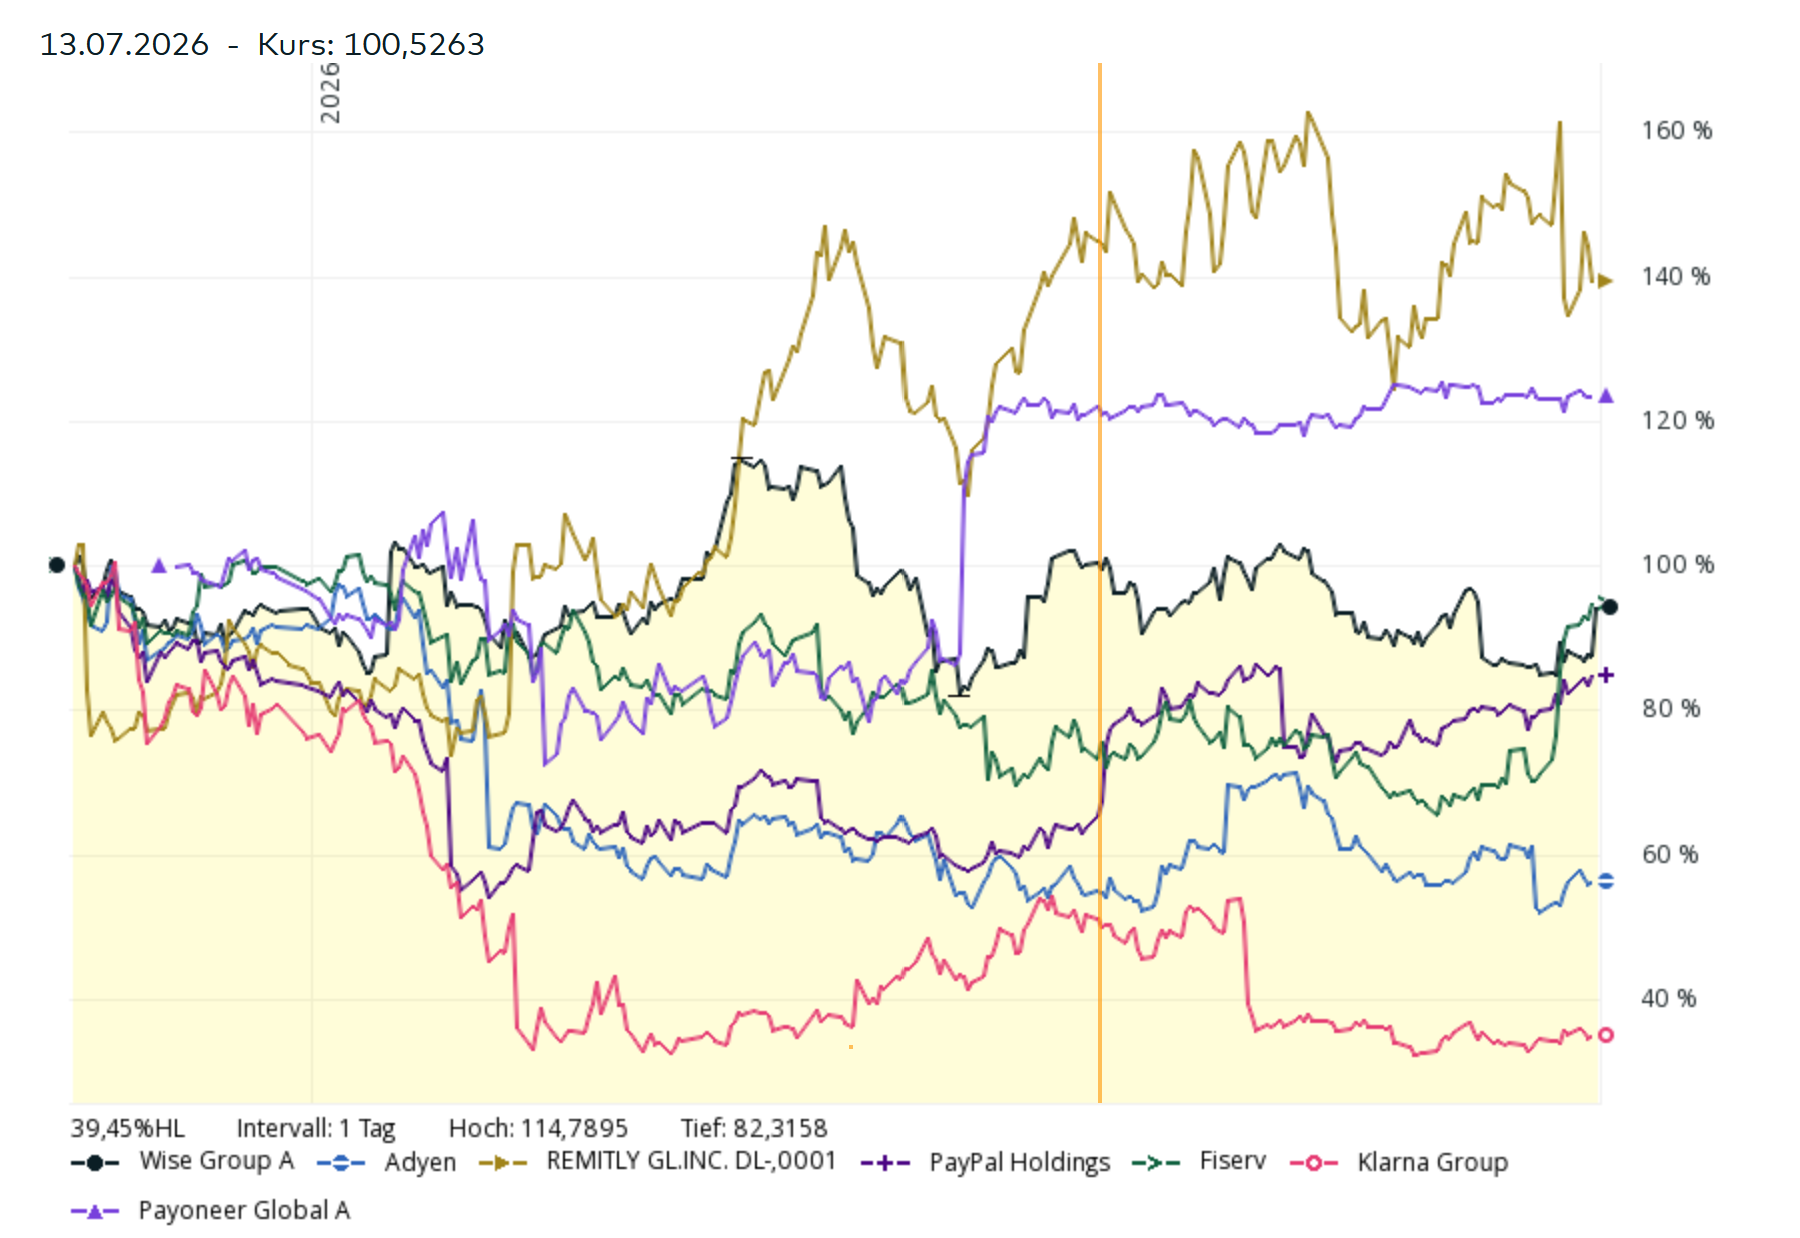
I collected a few peers and only Remitly, the US based remittance specialist did relatively well. Whereas especially Adyen and Klarna did really badly.
But overall, the payment sector was clearly not a sector that was very popular over the past 12 months which clearly didn’t help Wise.
Interestingly, Payoneer, which is maybe the closest listed competitor, did quite well, too. The reason here was a take over offer from another company called Nuvei.
Nuvei itself was a listed Canadian payments firm that was taken private by PE giant Advent in 2024. So at least the PE guys still see some future for this kind of business.
It needs to be seen if a combined Nuvei/Payoneer entity becomes a more serious competitor for Wise or not.
Interesting Blog Post from Reimar Scholz
Reimar Scholz is a Munich based investor who got quite rich by buying struggling private companies for 1 EUR. He has now turned into a listed securities investor and writes a pretty decent Substack.
Just recently he wrote about payments and Wise.
For Wise, his argument is that the stock is too expensive and that there are some initiatives underway (Project Nexus, direct Link Europe to India) that could make life harder for Wise:
Project Nexus seems to have started by the BIS and now handed over to some South East Asian National Banks. The last official announcement of this project according to Claude is from 2026 and it is rumored that something should go live in 2027.
The Europe India project is also expected to go live in 2027. This is what Claude summarized for me:

Importantly, there will still be a bank involved on both sides which will charge fees and most likely screw you on the Exchange rate.
I agree with Reimar Scholz that there are a lot of moving targets in the payment sector, but my take away is that the biggest losers will be the traditional banks, not the new players like Wise.
Summary/Conclusion:
So what is now the conclusion for me ? Should I buy more, sell or do nothing ? After some intense discussion with my French intern, I came to the conclusion that I will do nothing.
My triggers for selling have not been hit, however, business wise the number are also not good enough to increase the position despite the lower valuation. Especially the rather slow growth of EPS due to the increase in costs is something that needs to be monitored closely.
For the next quarters, it will be especially important to see if and how the expenses develop and if they may rise a little less than in the first 6M.

