Updates: DCC (sold), TFF (sold), EVS (hammered) & Rightmove (rumours)
DCC – post mortem
Let’s start with the positive case. I realized my DCC position recently as the share price (~64,4 GBP) approached the bid value (66,72 GBP) and the remaining upside was not so attractive anymore, especially considering potential GBP volatility for me as a EUR investor.
Looking back at the initial write-up, the result was pretty Ok.

I made slightly over +50% over 3 ¾ years plus some more on the additional portion I bought after the first bid in May this year. This was within the expected range of outcomes:
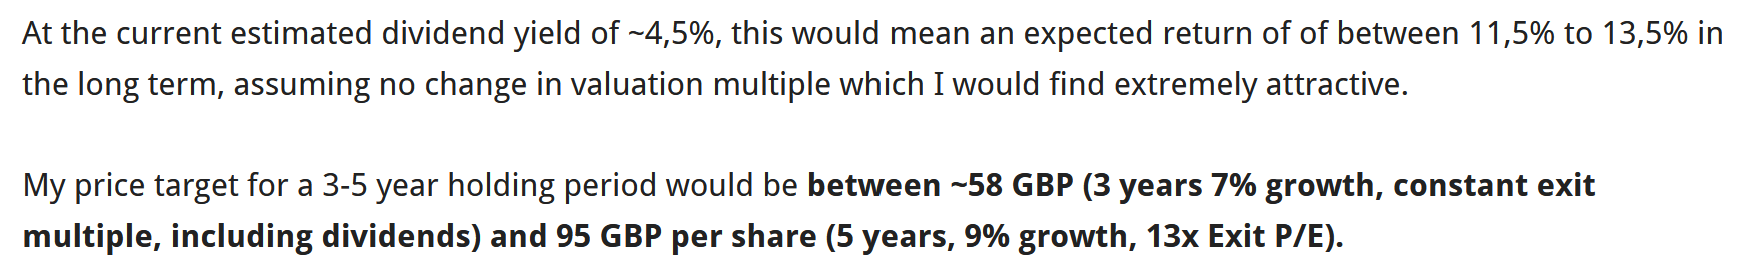
However, and this is a big HOWEVER, this positive result was not driven by the business case that I had underwritten, but purely a function of the premium paid by the acquirer KKR.
Looking at the earnings history, we can see that DCC’s earnings didn’t improve at all since my purchase in late 2022:
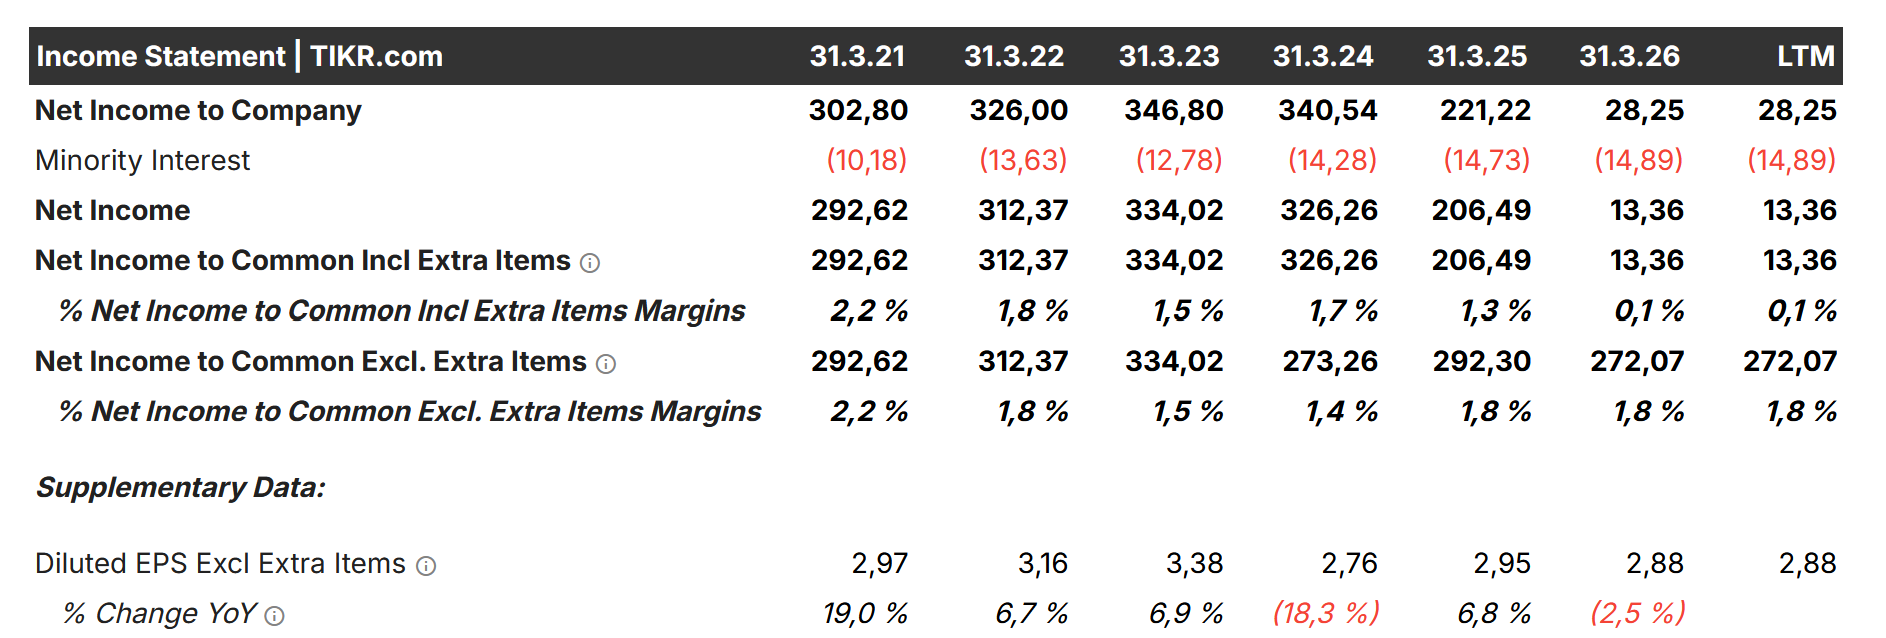
DCC rather had to go through a painful restructuring because they found out that everything they acquired outside their core business Energy was rather not good.
To be honest, I didn’t see this when I invested back then. I rather thought that having 3 different “platforms” gives them a lot of flexibility to allocate capital.
Looking at the stock chart we can see that my entry timing was quite lucky, but then not much happened until very recently:
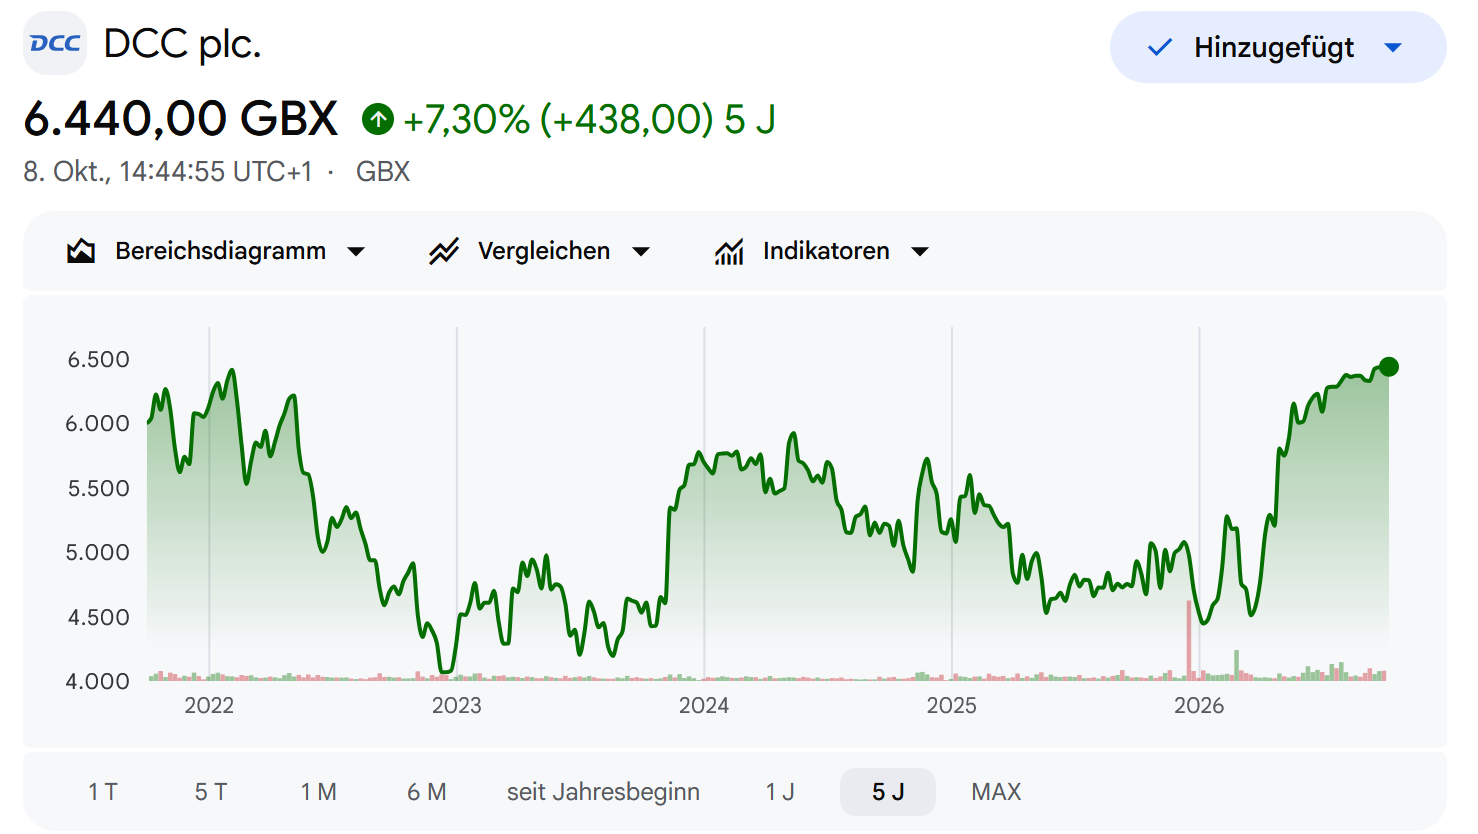
So the positive outcome of this investment was much more luck than my ability to pick an undervalued company with a great past that performed well.
I think this is/was maybe a major weakness of my investment approach: Just assuming that a successful past is a good indicator for an equally successful future, depsite some temporary headwinds. This can work, but it clearly doesn’t have to work.
What went well though was the decision to increase the position after the first bid. While this was not a huge performance driver for the overall position, it was a very low risk Special situation add-on.
Quick update: Just an hour ago, DCC announced that they sold the remaining business from the Technology segment for a rather “lowish” price. From a potential 125 pence “Sweetener” for this deal the actual outcome seems to be “only” 42 pence now.
TFF post mortem
Funnily enough, I funded part of my DCC position as mentioned above with a partial sale of TFF, which back then was my largest position. I just checked my files and I sold ~11% of my position back then for ~39,70 EUR per share.
TFF was my oldest position and the only stock remaining from the initial portfolio from December 2010.
So why did I decide to sell now ? To be honest, i had been thinking about reducing/selling for quite some time. I wrote about my doubts already in the 2026 performance review in January 2026 and subsequently sold my Laurent Perrier shares.
With regard to TFF, I cautiously thought that maybe the worst is behind us.

And:
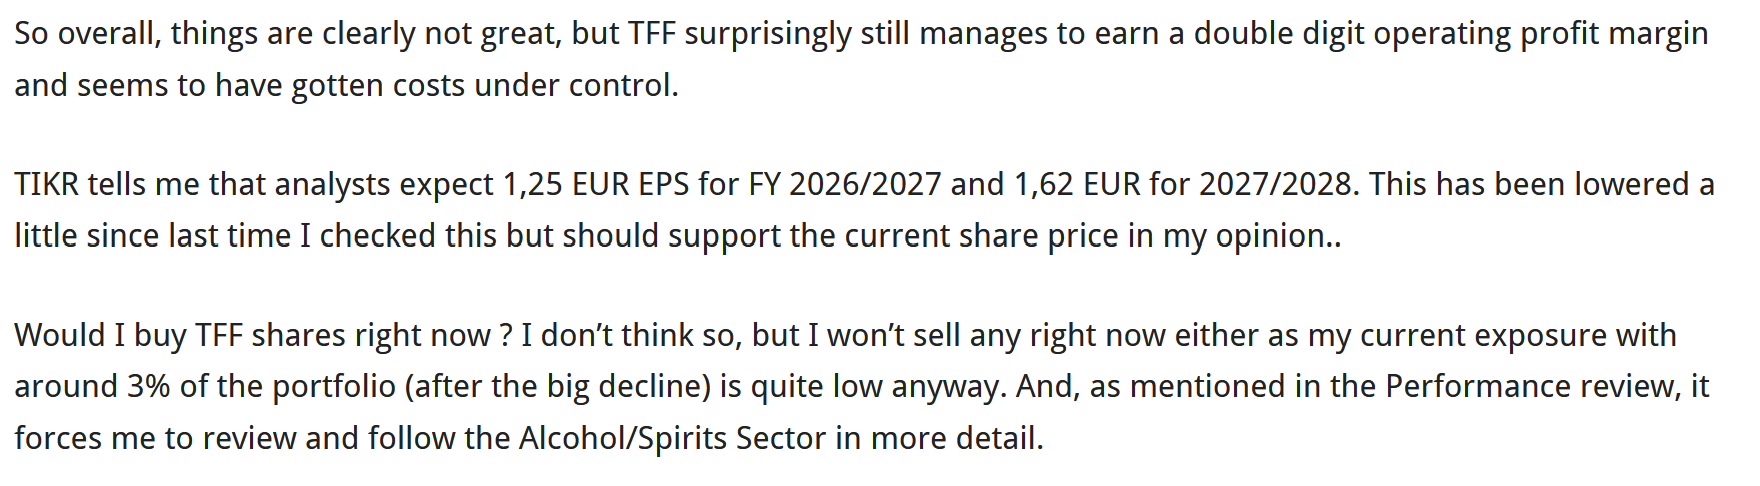
Then however came the horrible horrible Q1 (2026/2027) report in mid Septmeber which showed once again an acceleration of the sales decline, both in Wine and Whisky:
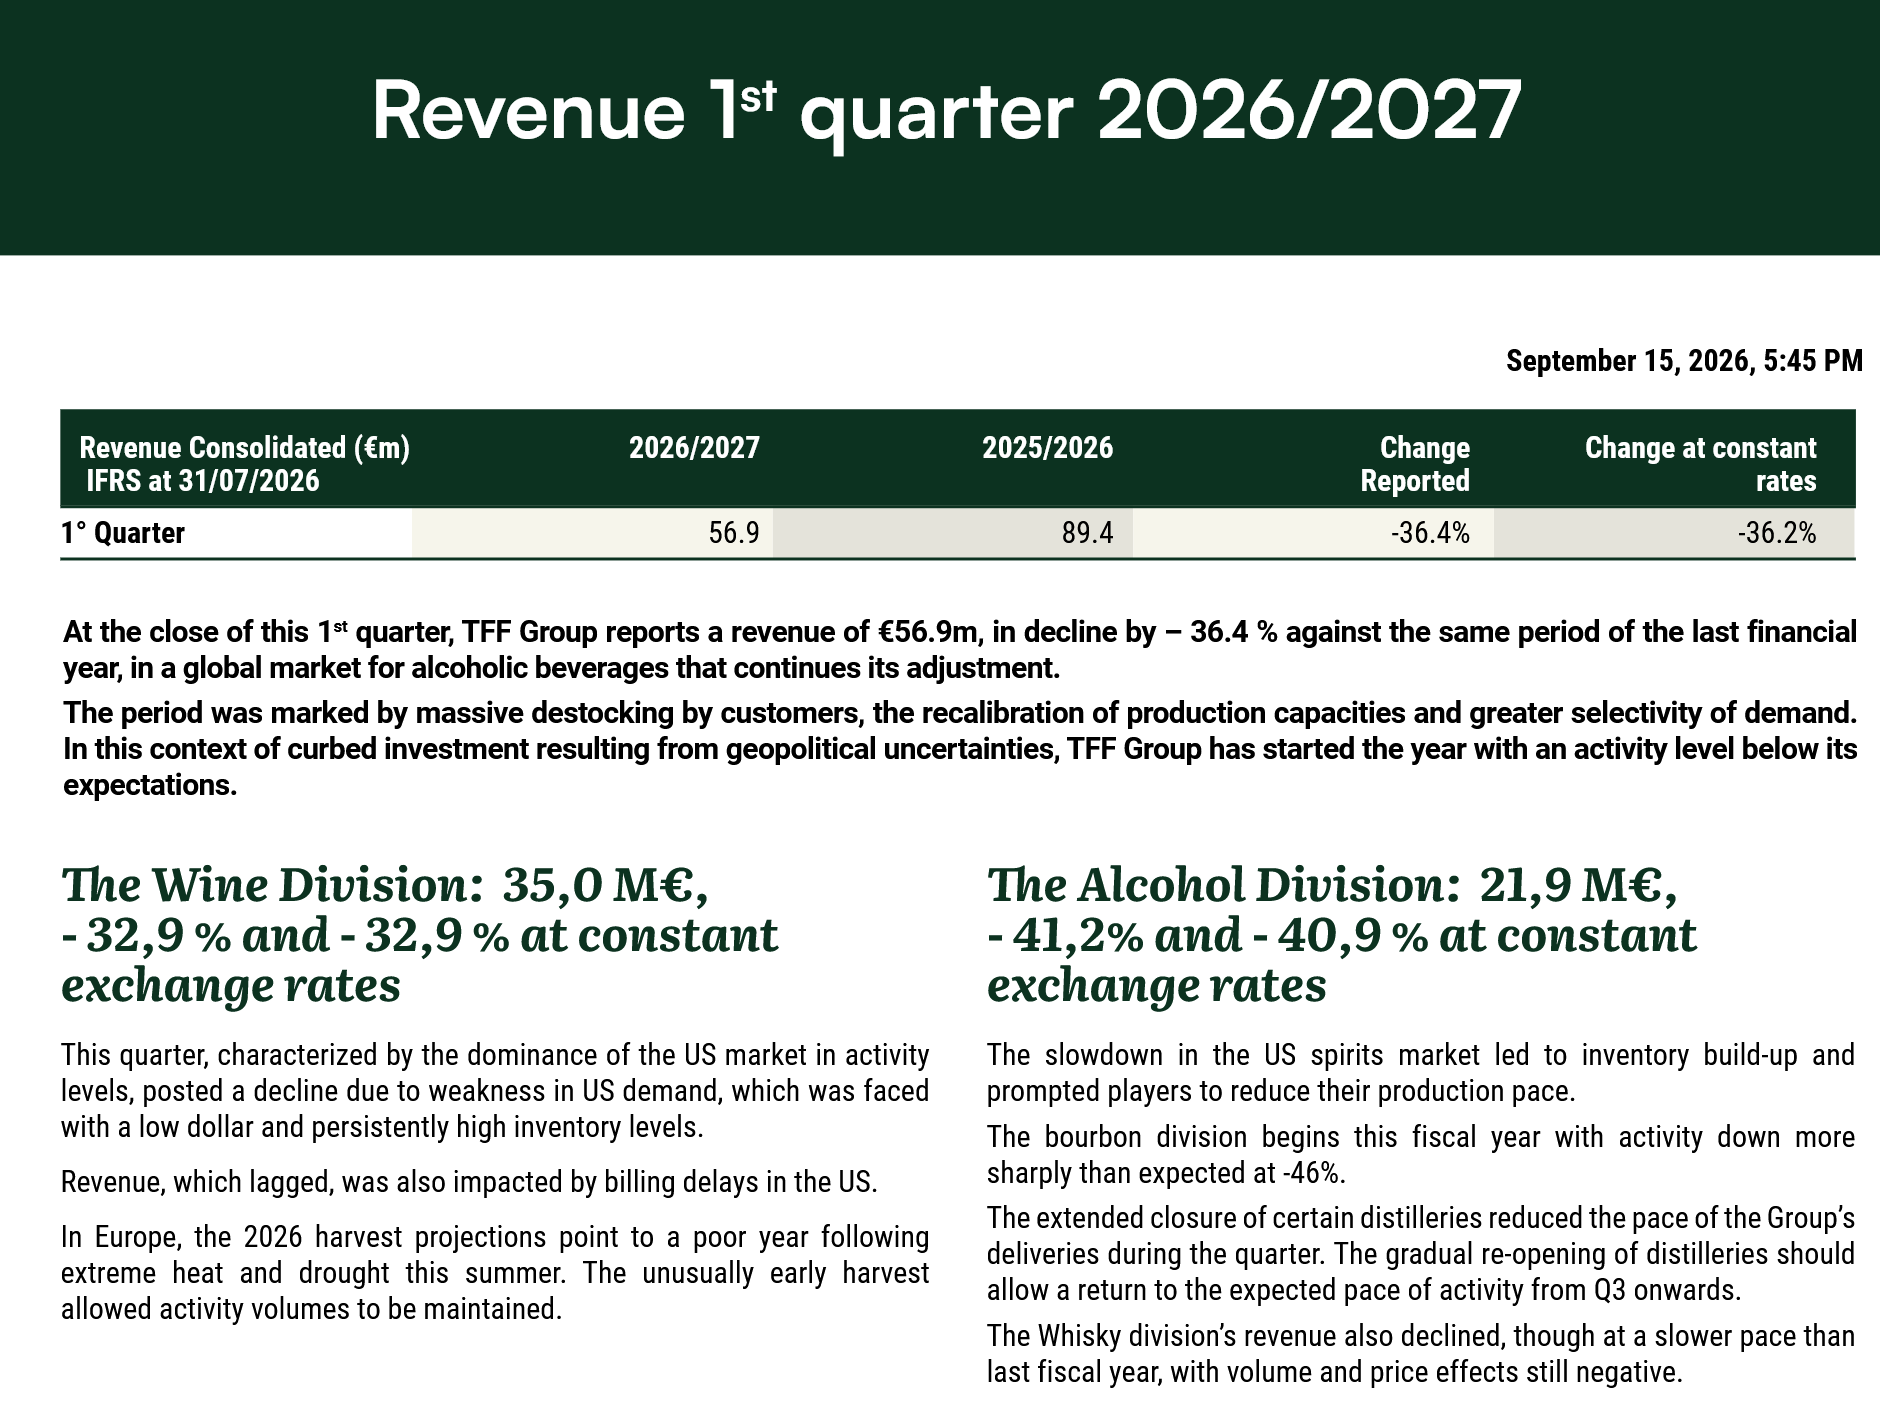
What really worries me now is the debt level of TFF. With declining Sales and profits, the 300 mn in net debt will become a larger and larger burden and refinancing this with the rapidly increasing interest rates especially in France is clearly not so easy.
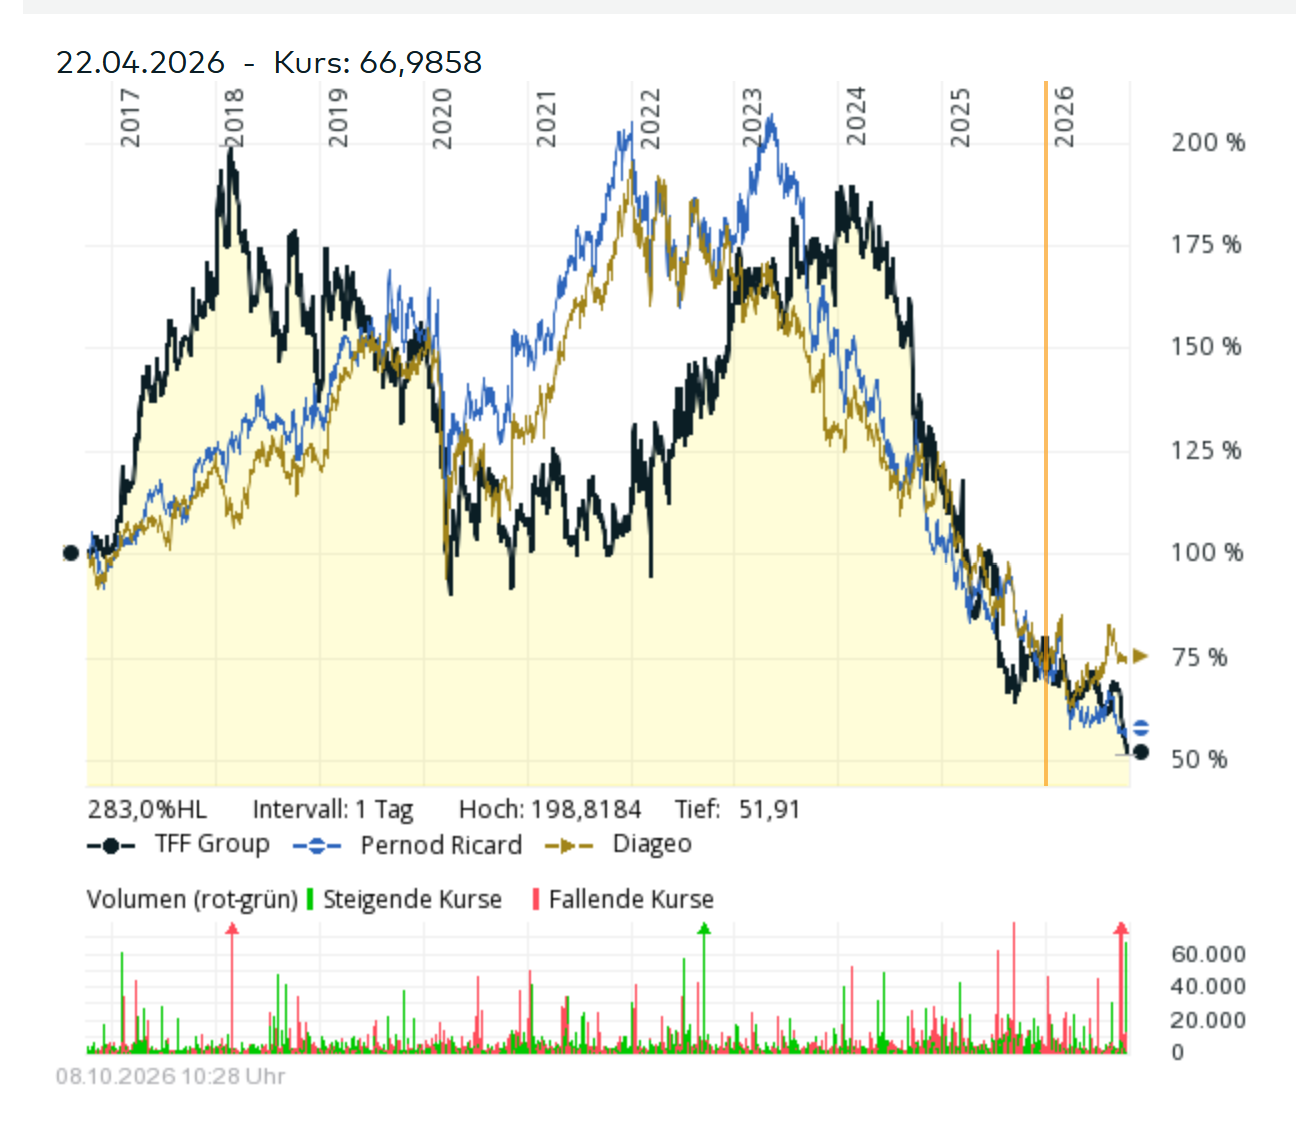
What I find interesting, looking at the charts of TFF vs. Pernod and Diageo, is that TFF’s share price for some reason kept up longer than the actual spirits makers:
One of the disadvantages of writing a blog is that when I write about a decision like this one, the risk is relatively high that I look like a complete idiot if the stock rebounds within a short period of time. Then the usual group of trolls will make nasty comments that I delete (of course).
I think that was also one of the implicit reasons why I didn’t sell earlier. Going forward, I think I will move from a “real time blog portfolio” to something like a “quarterly rebalanced watchlist” in order to avoid such “mental traps”.
In any case, after almost 17 years, I sold my TFF position which now was only 2% of the portfolio. My average purchase price (including a later purchase at a higher price ) was 11,75 EUR and I collected 4 EUR in dividends per share. That’s about 2% p.a. over almost 17 years. It improves a little bit taking into account the mentioned partial sale in 2022. But overall, the result was not great.
EVS
Luckily, I sold EVS in July because I didn’t feel comfortable after the CFO suddenly disappeared and numbers looked weak in an “event year” with Olympics and the Football Worldcup.
Yesterday, EVS drastically reduced their sales outlook for 2026 and the stock got hit really hard and was down -30% at the end of the day:
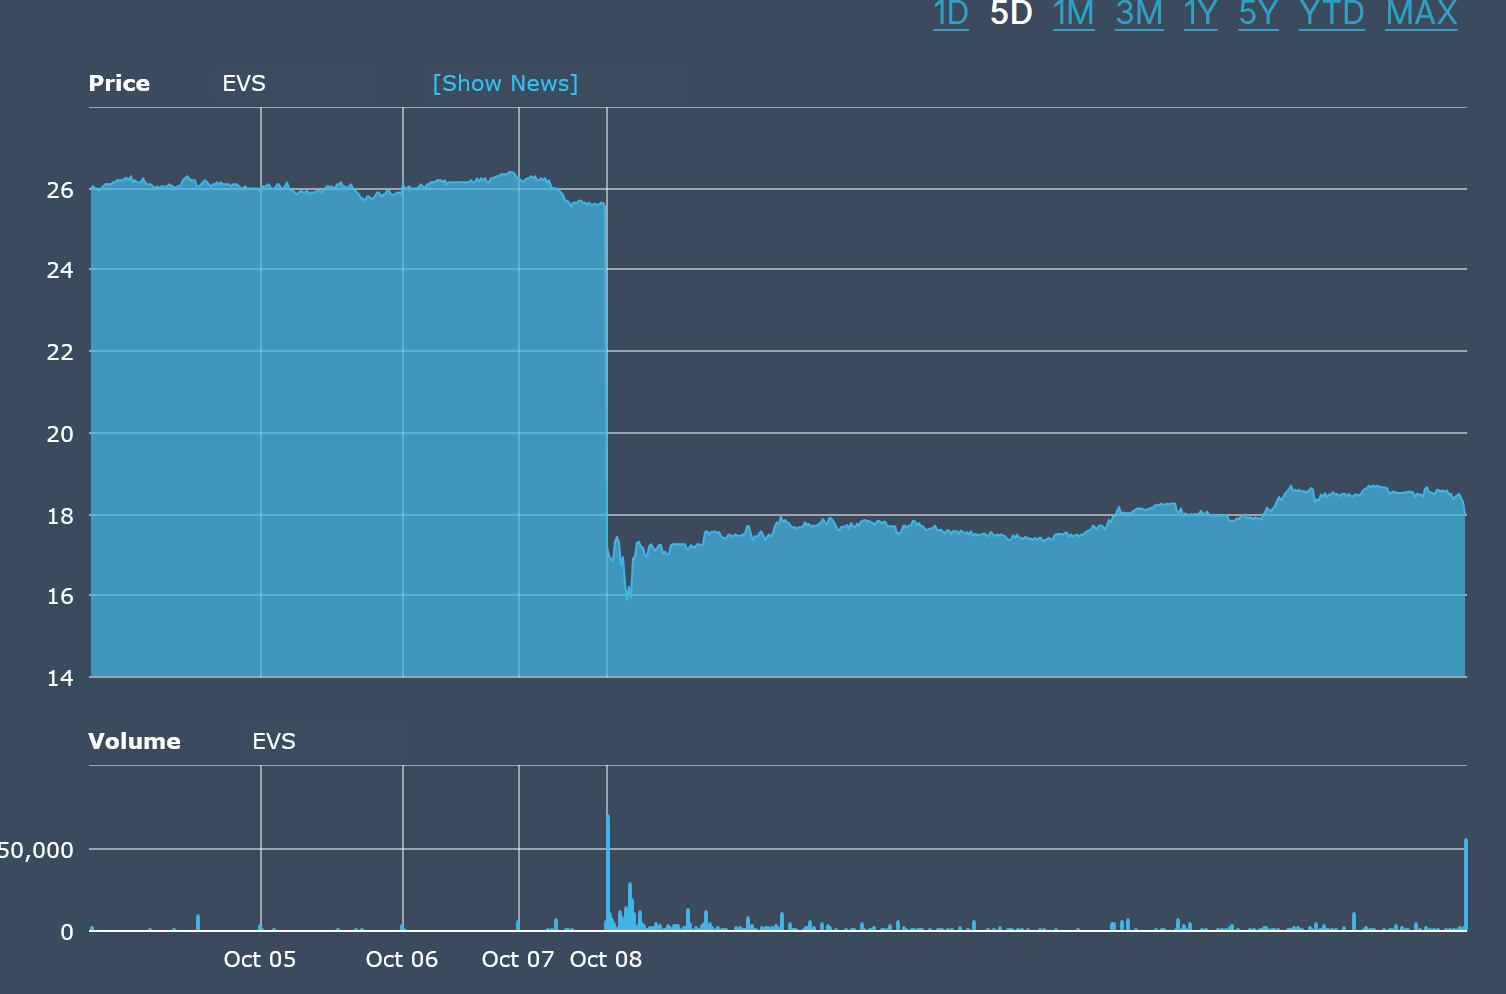
And this after being already down -30% YTD.
In this case, my timing was fortunately better than usual.
Rightmove
Yesterday around 4 pm my time, Rightmove suddenly jumped almost 15% because an outlet called “Betaville” mentioned that they heard about a rumor of take over interest for Rightmove.
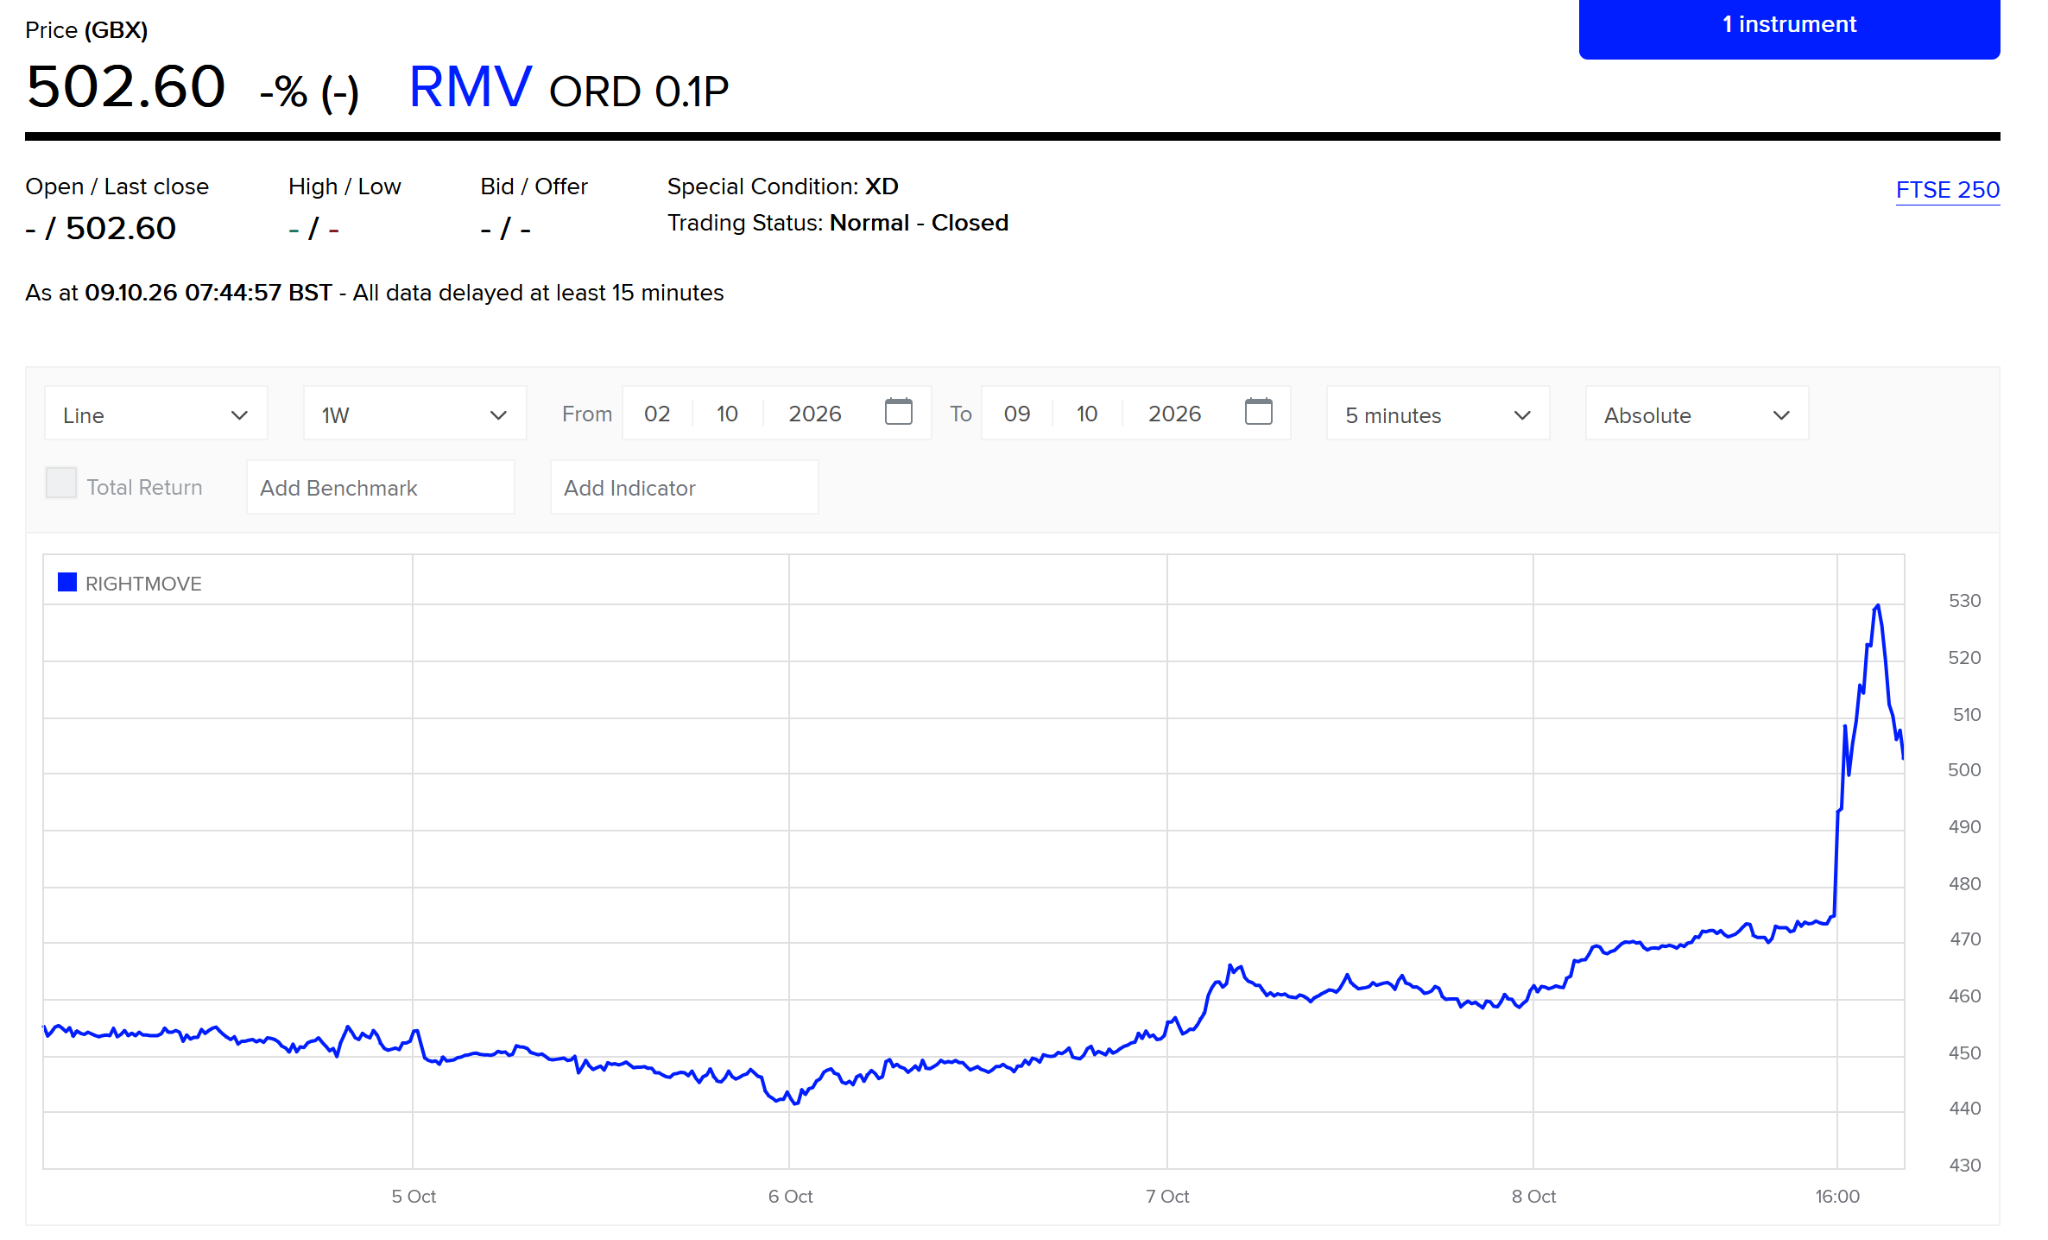
No one knows if there is any truth in that or not, but the significant reaction in the share price in my opinion shows that maybe (and this is a big maybe), the worst is behind for the major classified/marketplace players.

