Category Archives: Anlage Philosophie

All Norwegian Stocks part 7 -Nr. 91-105

To keep the running gag going: No fish this time and only a few ships, but a lot of other stuff in this random selection of 15 Norwegian stocks. 4 out of these 15 qualified for my prelimiary “watch” list. Let’s go:

91. Wilson ASA

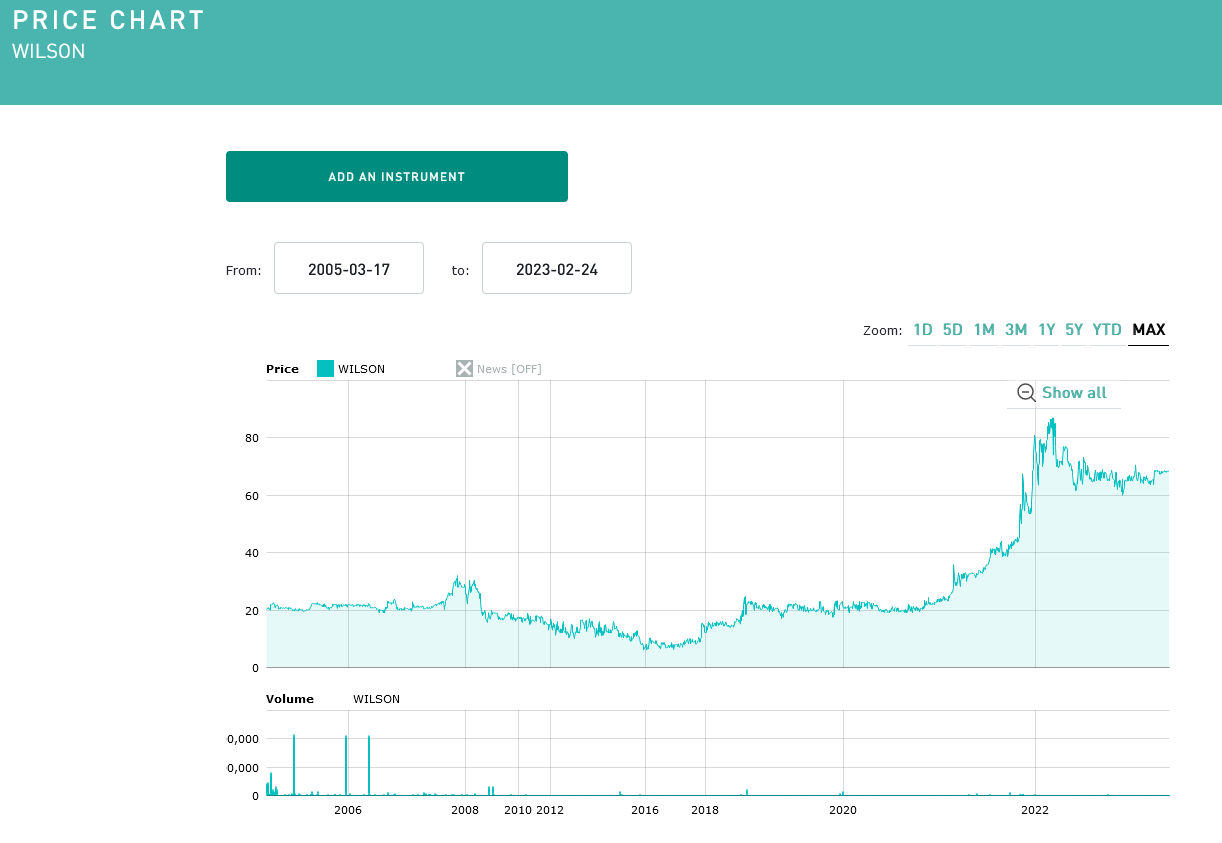
Wilson is a 270 mn EUR market cap shiping company that operates ~130 smaller vessels. As other shipping companies, they trades at very low valuations, in this case 3,5x 2022 P/E. Operating margins have increased from 2,5% to 40% in 2022. I have no idea how sustainable these margins are, but historically the peak has been around 20% and on average maybe 10-15% with a high volatility. Interestingly, the share price hovered around 20 NOKs for 20 years before going up more than 3x in 2021:
Nevertheless, volatile shipping stocks are not my area of expertise, “pass”.

92. Elektroimportoeren ASA

As the name indiactes, this 84 mn EUR market cap company retails and distributes equipment for electrical installations (light, electricity etc.). The company has grown nicely over the past 5 years, however EPS halfed in 2022 which led to a significant drop in the share price below the level of the IPO in 2020:
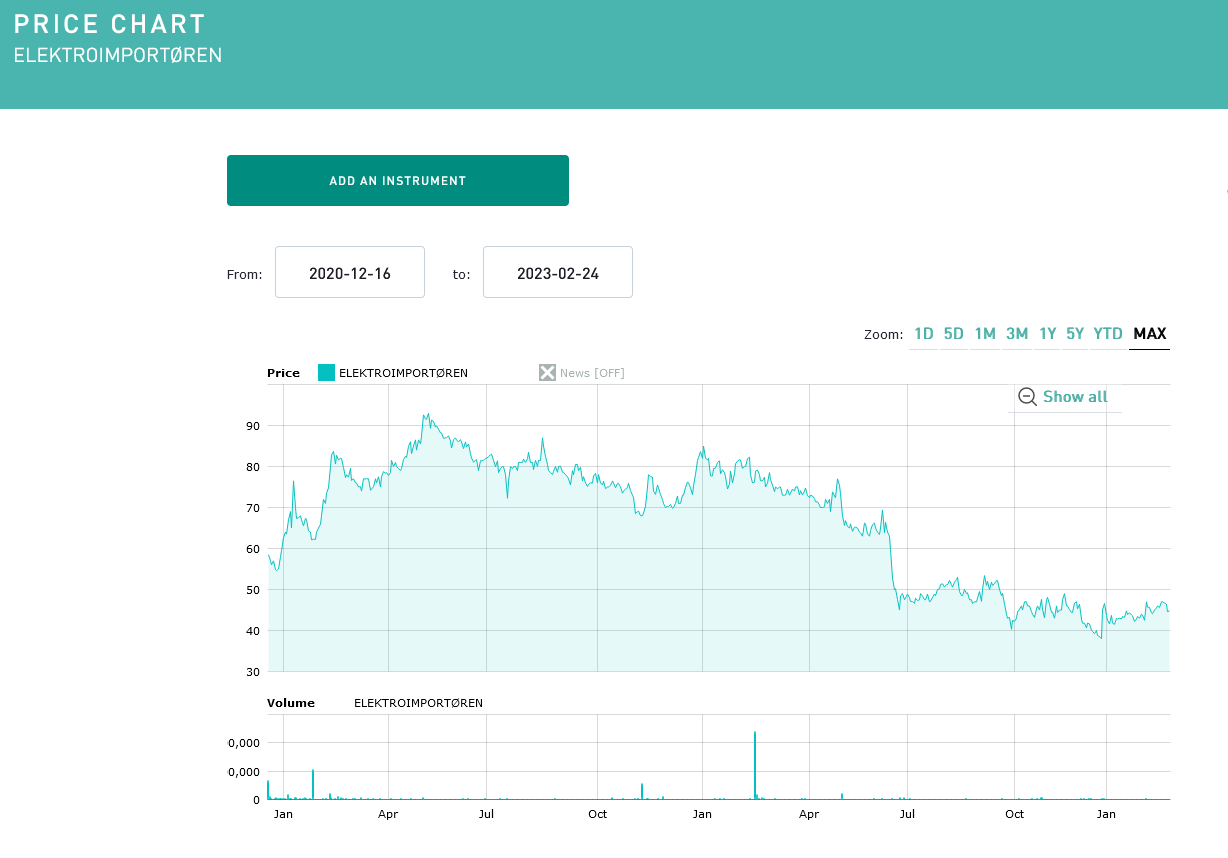
They seem to have entered the Swedish market in 2022 but overall, Gross margins and like-for-like sales struggled and interest expenses increased, leading to a big reduction in profits. At 19x trailing p/E and 15x trailing EV/EBIT, the stock is not cheap and the IPO seems to have been “well timed”. “Pass”.

93. Entra

Entra is a 1,9 bn EUR market cap real estate company that mostly owns office buildings in Norway. The stock lost almost -50% from its top, similar to many other real estate stocks. I always find it hard to understand the commercial real estate KPIs like EPRA NAV and this stuff, their P&L is quite messy as the show mark-to-market gains and losses in the P&L. Real estate is something I would only consider in very specific circumstances which this is not. “Pass”.

94. Navamedic

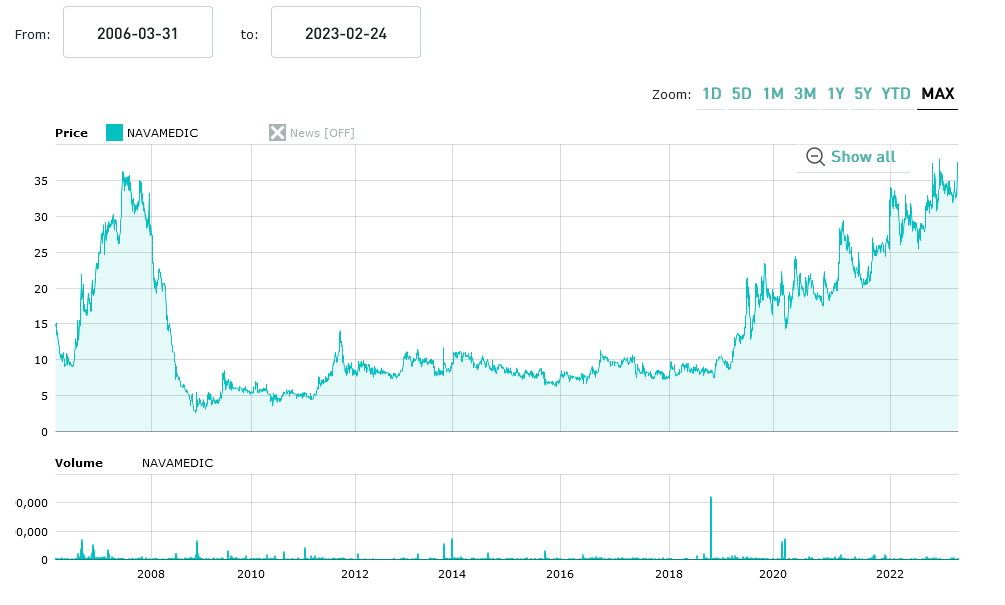
Navamedic is a 57 mn EUR market cap “Nordic pharma company supplying hospitals and pharmacies with pharmaceutical and medical nutrition products”. The company has been loss making for many years but, surprisingly, became profitable in 2022. This is reflected in the share price which is now close to ATH:
The company seems to have a wide protfolio of OTC and prescription drugs as well as “medical nutrition” with some focus on obesitiy, but also antibiotics and other stuff. At less than 20x P/E, the stock is not too expensive and the company plans o grow via M&A etc to 1bn NOK in revenue and 150 mn NOK in EBITDA. For the time being, I will put them onto the extended “watch” list

95. Cyviz

Cyviz is a 44 mn EUR market cap “global technology provider for standardized conference rooms, control rooms and experience centers.” The company was IPOed in December 2020 and is loss making, but based on TIKR at least cash flow positive.

If I understand their business correctly, they establish control rooms for the defense sector as well as high quality board rooms atc around the world:
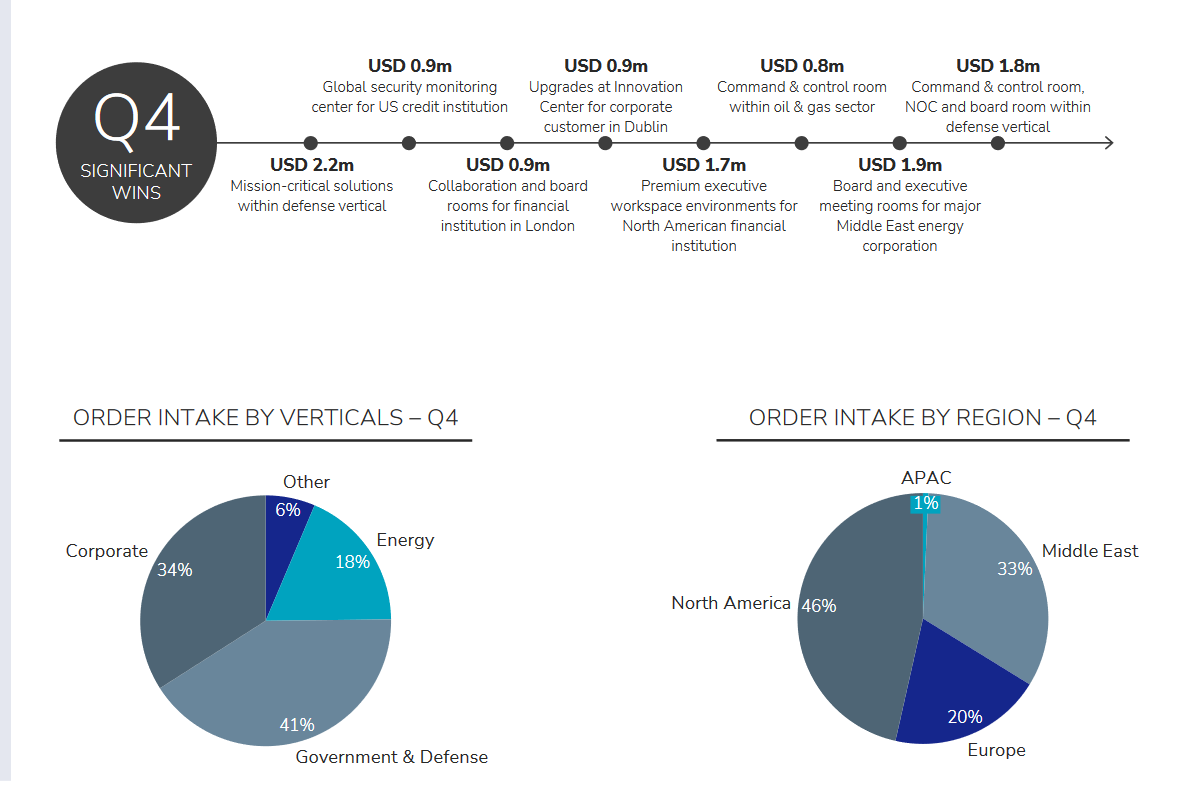
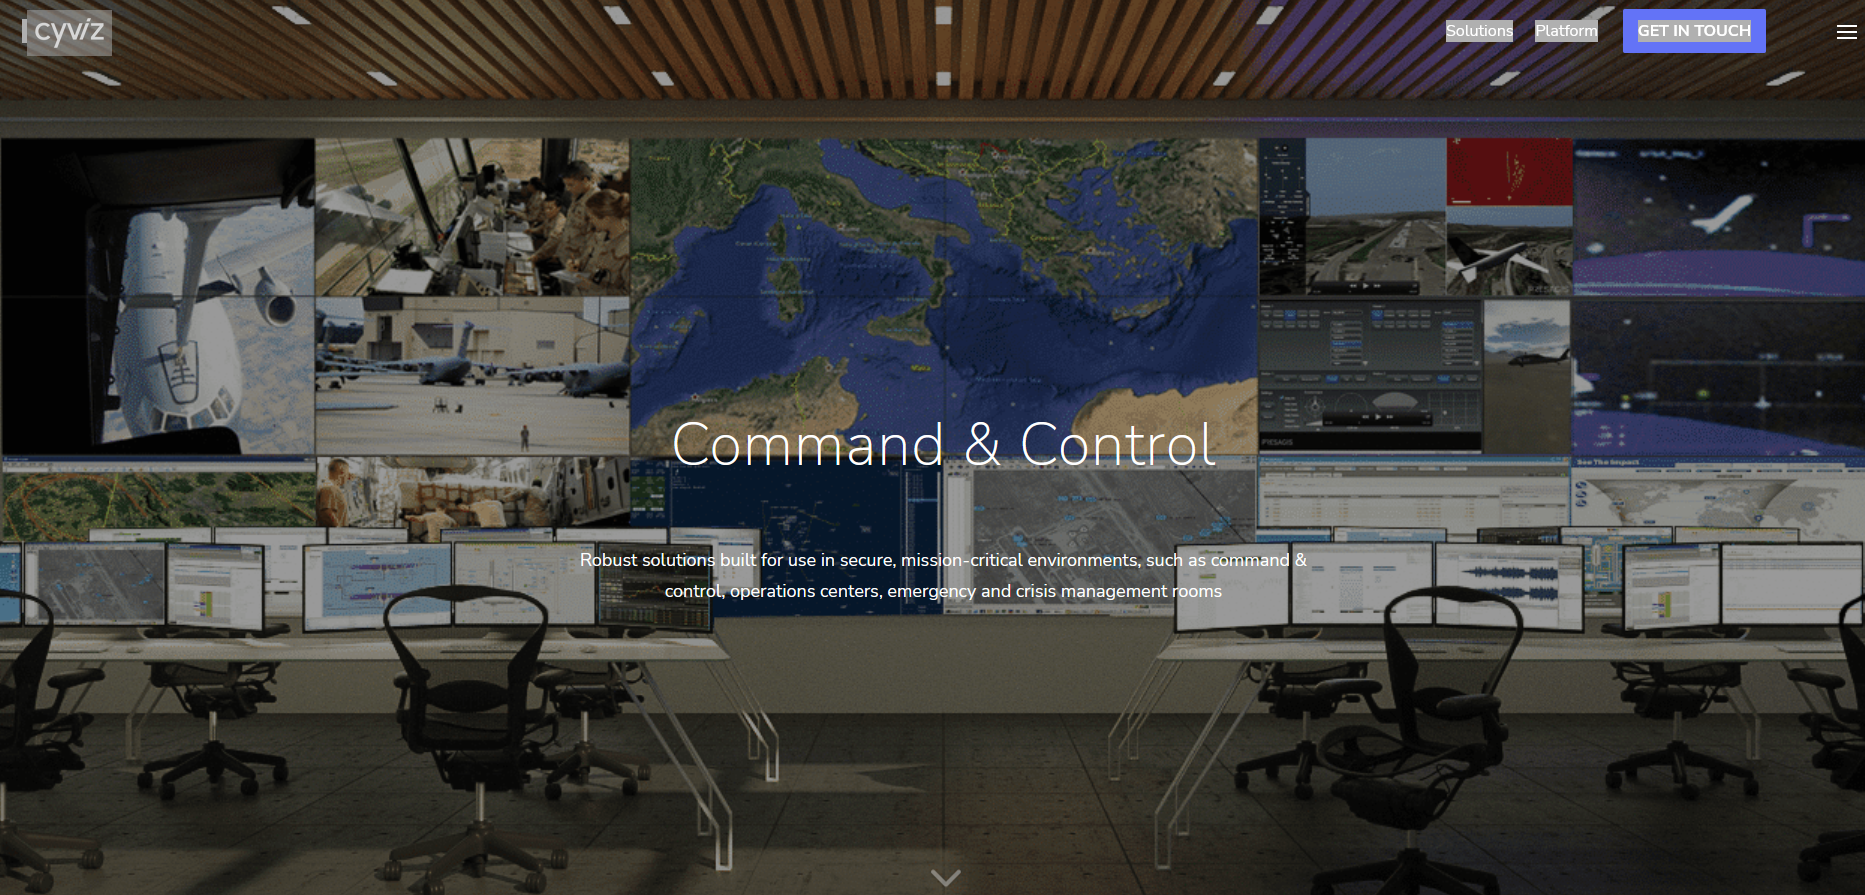
Somehow I find this company quite interesting, especially as it is still growing quite quickly (+50% full year, +80% q-o-q). This seems to be one of the better 2020/2021 IPOs, therefore “watch”.

96. Elliptic Laborator

Elliptic is a 160 mn EUR market cap company that does some “”sexy” things like “AI Based 3D gesture Software sensors”. However, Revenue is only 5 mn EUR, stagnating and they are making losses. One of the weaker 2020/202 IPOs, “Pass”.

97. ATEA

ATEA is a 1,2 bn EUR market cap “leading Nordic and Baltic solution provider of IT infrastructure with over 7,000 employees. Atea is present in 85 cities in Norway, Sweden, Denmark, Finland, Lithuania, Latvia and Estonia. “

With operating margins of 2-3%, the bsuiness model seems to be more of a reseller or distributor. The company is relatively moderately valued at 14x P/E and return on capital/equity is currently at around 20% or more.

Atea has net cash, is paying a rather generous dividend (~5% yield) and has been growing nicely over thy past few years. The share price however does not fully reflect this:
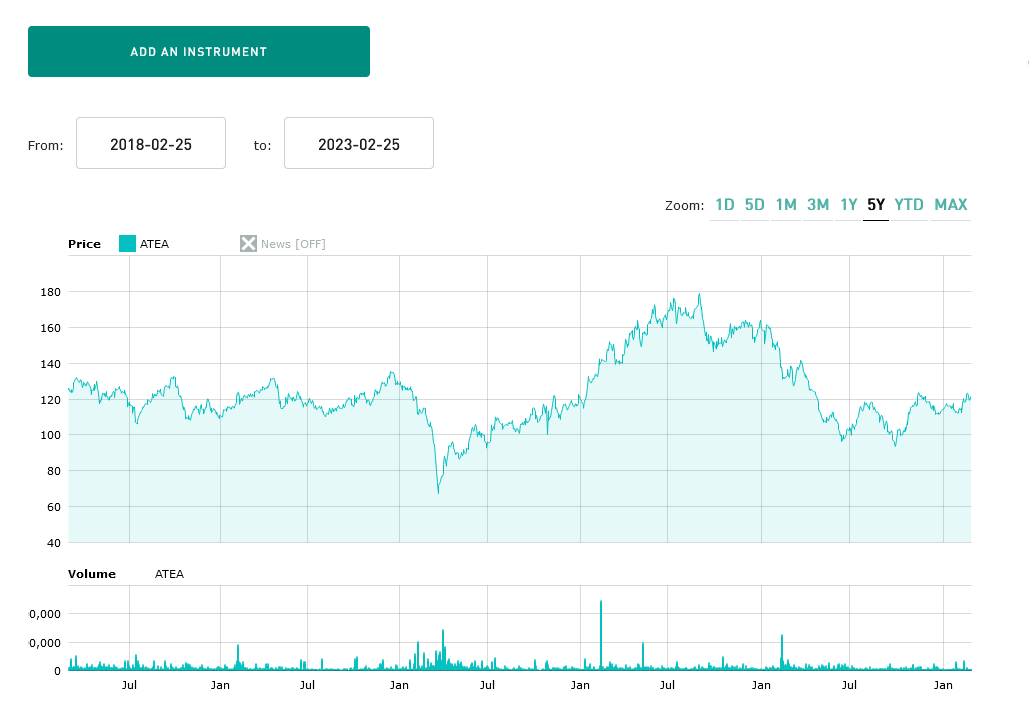
Although similar IT distributors are equally cheap, I put ATEA on “watch”.

98. Green Minerals

Green Minerals is a 5 mn EUR Nano Cap that claims to be the ” pioneer in marine minerals on the Norwegian Continental Shelf”. The company has little revenue and is burning money, with a runway of less than 2 years left. “Pass”.

99. Norwegian Block Exchange

This 10 mn EUR market cap 2021 IPO runs a Crypto exchange. Of course they are burning cash and they have raised addtional money in Q3 2022. “Pass”.

100. Questback Group

Questback is a “leading platform for conducting Employee and Customer Experience surveys”. The market cap of only 5 mn EUR indicates that business is not so great. They have been growing in 2022 but are CF negative and have substantial debt. Further equity financing is likely required as they have less than 1 year runway left. “Pass”.

101. Exact Therapeutics

Exact is a 31 mn EUR market cap stock that IPOed in 2022 and lost around 2/3 of its value since then. They develop technology ” for targeted therapeutic enhancement – Acoustic Cluster Therapy (ACT®). ACT® sonoporation is a unique approach to ultrasound-mediated, targeted drug enhancement”, whatever that means. The company has no revenues, “pass”.

102. Solstad Offshore

Solsatd is a 320 mn EUR market capo company that “operates offshore service and construction vessels for offshore and renewable energy industry worldwide. It provides platform supply vessel, anchor handling vessel, subsea construction, and renewable energy services.”.

Looking at the stock chart, the company went through hard times and was restructured in 2022 including a debt-to-equity swap.

Operationally, things look relatively good these days, but the company still carries a lot of debt (~2 bn EUR) and is making losses on GAAP basis. Largest Shareholder seems to be Aker who snapped up other Norwegian players in the past. “Pass”.

103. Adevinta

Adevinta is a 8,4 bn EUR market cap online classifieds company that was spun-off from Schibsted in 2019. Schibsted owns ~34,8% and interestingly Ebay owns almost the same amount. Looking at the chart, we can see that initially the stock perforemd very well before than suffering from 2022 on:
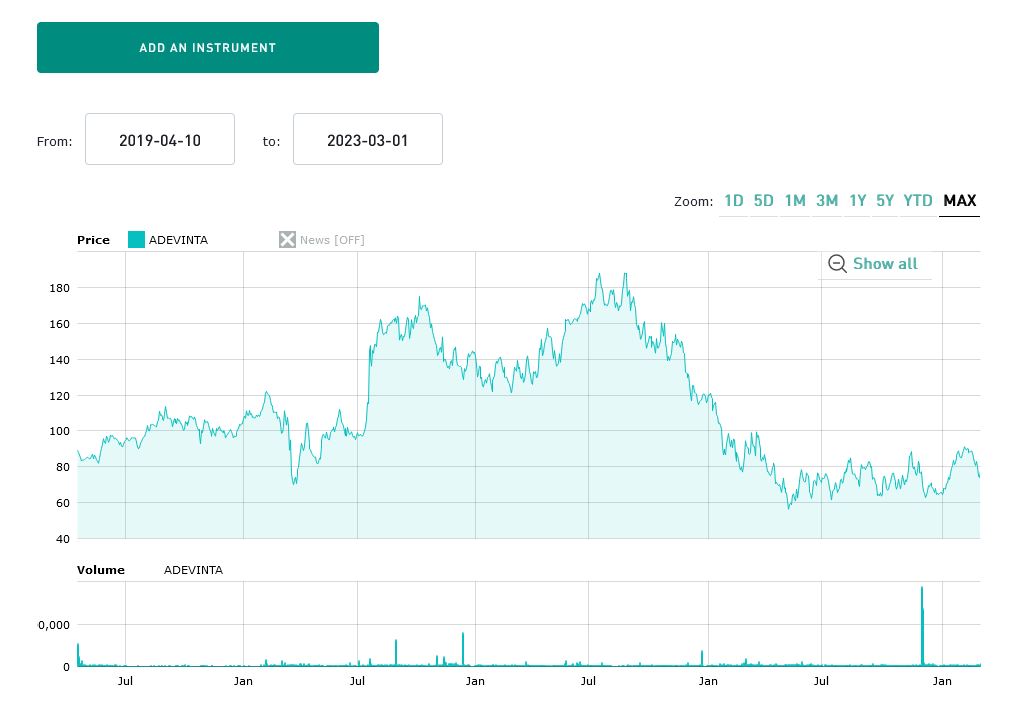
The business as such looks attractive. High growth rates (+40% in 2022) and decent operating margins. However, a large Goodwill impairment in 2022 led to a GAAP loss.

Based on the projections, the stock is valued a ~15x EV/EBITDA for 2023 and they expect to grow at “low double digits” for the next years. Although the stock is not cheap, it is defintely one to “watch”.

104. Nel ASA

Nel is a (much hyped) 2,2 bn EUR market cap company that is active in the Hydrogen Economy. Nal manufactures Electrolyzers and Hydrogen Filling station equipment. Looking at the chart we can see that Nel has been around for some time and had a frist hype cycle just before the financial crisis:
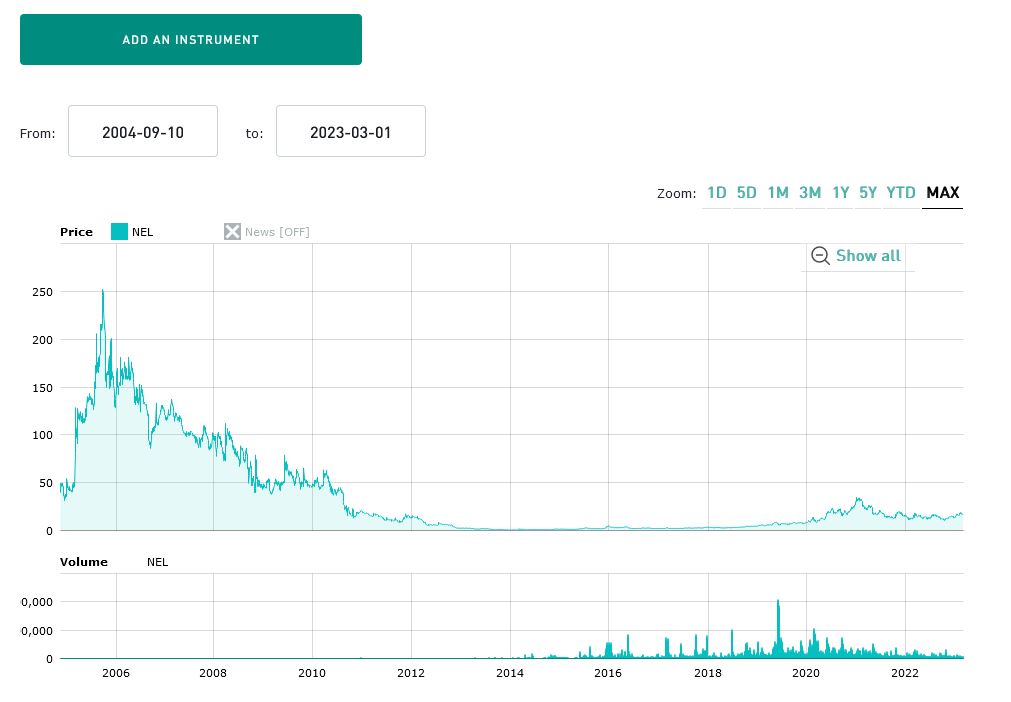
Compared to other companies in that space, NEL actually does have sales (~90 mn EUR in 2022), but is not making money. Losses are actually higher than sales. Personally, I do not believe in a mass market for Hydrogen as a car or truck fuel at least for the next 10 years or so, therfore I’ll “pass”.

105. Arctizymes Techno

This “fancy name” company has a market cap of 180 mn EUR does something with enzymes and surprising to me is actually making a small profit. Nevertheless, at around 13xEV/Sales and 50x EV/EBIT with only moderate growth, I do not think that this is interesting. “Pass”.
All Norwegian Part 5 – Nr. 61-75

And on we go relentlessly with another 15 randomly selected Norwegian Stocks. As this time, an “old friend of mine” is within the selection, maybe one interesting aspect:

When I bought my first Norwegian stock in 2014, the Exchange rate had been 8,21 NOK per Euro. These days, Norway is stronger then ever and Europe is limping along. Nevertheless, the exchange rate today is 10,92 NOK/EUR which means the the NOK lost -25% over 8 plus years. Quite a surprise if you just look at this from the outside. And maybe the Euro is not so weak after all.

61. Höegh Autoliners

Höegh is a 1,15 bn EUR market cap “leading global provider of Roll On Roll Off transportation services, operating a fleet of around 40 Pure Car and Truck Carriers”. The company IPOed in late 202, but compared to other 2021 vintage IPO’s, Höegh investors are quite happy with the share price being up 3x since IPO.

The company seems to have a rather short financial history. Because of supply chain disruptions, charter rates are at mutli-decade highs. The market thinks that these rates are not so sustainable, otherwise the stock would not trade at a P/E of 3,5:

Read more

SFS Group AG (ISIN CH0239229302) – Super boring but sexy “Hidden Champion” from Switzerland

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!!!

Summary:

In my relentless effort to create the most boring and unremarkable stock portfolio imaginable, I think I identified an ideal  candidate with SFS Group from Switzerland.  Despite having a market cap of ~4 bn CHF, this majority family-owned company is not very well known and its products and B2B business model look similarily unremarkable.

The company doesn’t have an easily identifiable moat, doesn’t pay high dividends or buys back stock, is not super cheap and also not super profitable, doesn’t grow like crazy and doesn’t have sexy products that one can see in the supermarket.

Nevertheless I do think it is an great addtion to my portfolio as it is attractively priced and both, the business as well as the management are of high (Swiss) quality. Based on my own estimates, the stock trades at a PE of ~12x for 2023, despite having delivered EPS growth in EUR of around 15% p.a. since its IPO in 2014 and maintaing double digit EBIT margins across the cycle.

Read more

All Norwegian Shares part 3 – Nr. 31-45

And another 15 Norwegian stocks chosen from my Google Sheets random number function.This time only one “watch” candidate and not even a strong oe. C’mon Norway, you can do better !!!

31. KMC Properties

As the name indicates, this 212 mn EUR market cap company (IPO in 2021) is active in property. They specialize in industrial and logistics property that seems to grow quickly through purchases. The share price hasn’t done much since the IPO and seems to tarde close to NAV . “Pass”.

32. Argeo

Argeo is an 8 mn EUR market cap company that was IPOed in 2021. The company is active in fancy sounding seismic analysis activities. Unfortunately, the fancy technology does not translate in earnings but increasing losses. The stock lost more than -75% from the IPO and the company just had to issue new shares. “Pass”.

33. Hexagon Purus

Hexagon Purus ASA, a 520 mn EUR market cap stock sounds like an “Energy transation dream”: Accroding to the Euronext page, the company  “is specialized in the manufacture and marketing of Type 4 composite tanks for high pressure hydrogen storage. The group also manufactures battery packs, electric drive systems, components and battery systems for electric and hybrid vehicles.”

Read more

Reinsurance follow up: SCOR SE- Too cheap to ignore a P/E of 6x for 2023 ?

Disclaimer: This is not investment advice. PLEASE DO YOUR OWN RESEARCH !!!!

Background:

After looking at Hannover Re and Munich Re a few days ago, I decided to include also Swiss Re and Scor in my analysis. Unfortunately, for both of these players, the CAGRs for profit etc. are meaningless as they were making losses in 2022. However, especially for SCOR I found a few numbers very interesting:

Read more

Value & Opportunity 2022 Performance Review & 2023 Outlook

2022 overview

2022 was a in absolute terms pretty bad, in relative terms however very lucky. The Value & Opportunity portfolio lost  -3,9 % (including dividends, no taxes, AOC fund as of 30.09.) against -16,7% for the Benchmark (Eurostoxx50(25%), Eurostoxx small 200 (25%), DAX (30%), MDAX (20%), all performance indices including Dividends).

Links to previous Performance reviews can be found on the Performance Page of the blog. Some other funds that I follow have performed as follows in 2020:

Partners Fund TGV: -33,6% (30.12.) 
Profitlich/Schmidlin: -19,2% (30.12.)
Squad European Convictions -14,1% (30.12.)
Ennismore European Smaller Cos (30.12.) +3,8% (in EUR)
Frankfurter Aktienfonds für Stiftungen (30.12.) -17,3%
Greiff Special Situation (30.12.) -3,5%
Squad Aguja Special Situation (30.12.) -19,2%
Paladin One (30.12.) -19,1%

Most of the “Long only funds” in the peer Group were clustered together near the benchmark in a tight range of -14% to -19%. The only positive peer was Ennismore, which is a long/short funds.

Read more

All Norwegian Share part 2 – Nr. 16-30

There is nothing better than starting a year with looking at 15 “fresh” and randomly selected Norwegian shares. Three of them made it onto my preliminary watch list. As always, I am more than happy to get my reader’s input in the comments as these are quite rapid analysis and I most likely miss a lot of interesting things. Let’s go: 

16. Melhus Sparebank

Melhus is a 43 mn EUR market cap local savings bank. The stock trades at around 10x earnings, pays a 6% dividend but hasn’t moved much for the last 20 years. EPS is oscillating in a range since 20 years, too. “Pass”.

17. Europris ASA

Europris is a 1,1 bn EUR market cap retailer that sells “discount variety” items in Norway, both through a chain of 300 stores but also online.

AT 12x earnings, the stock doesn’t look expensive and according to TIKR, they did 10x their EBIT since 2013. The company IPOed in 2015 and looking at the chart, they seem to have done quite well for a retailer, especially in the last few years despite Covid Read more

Hannover Re: An overlooked Reinsurance Compounder & Comparison with Munich Re

Spoiler: This rather long post contains no actionable investment ideas.

Background:

Hannover Re is a stock that for some reason I have ignored for some time although I consider Insurance stocks as part of my circle of competence. Why did I ignore them ? I was always put off from the ownership structure. Hannover Re is majority owned by Talanx, which itself is also listed. Talanx again is owned ~80% bei HDI, which is owned by …I don’t know.

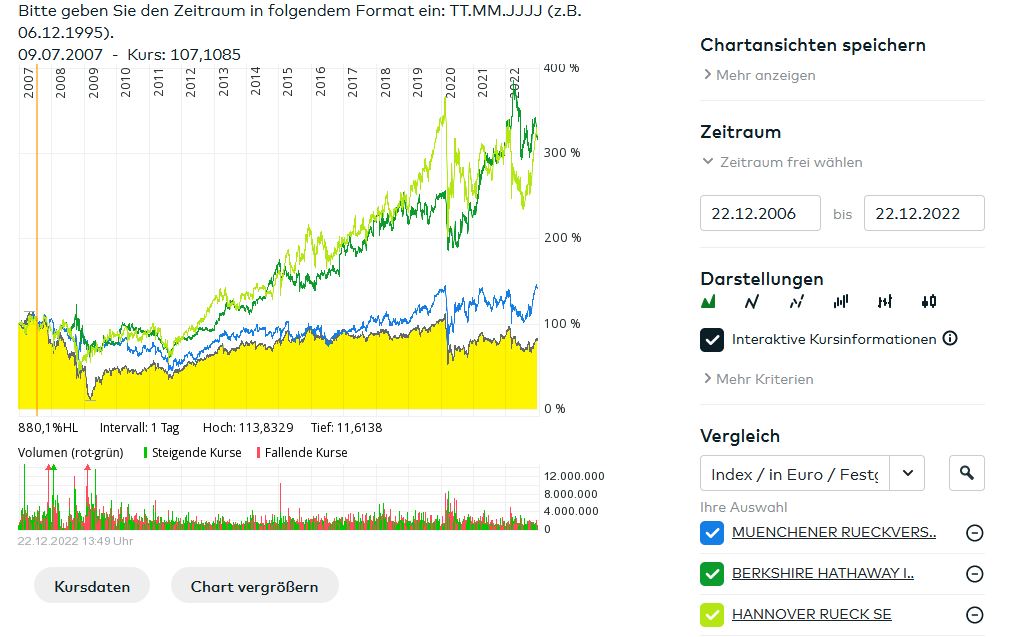
Looking at the chart, I should have considered them earlier: Over the past 15 years, Hannover outperformed the larger and better known peers like Munich Re and Swiss Re by a wide margin and ties with Berkshire (before FX):

hannover 15 years

This is very interesting, considering that Hannover Re is only the No. 3 global Reinsurer and Berkshire only number 5. Absolute size doesn’t seem the drivig factor for shareholder returns in the Reinsurance industry.

Deep dive Comparison: Hannover Re vs. Munich Re

Read more

My 23 Investments for 2023

Following an annual tradition, I’ll try to review my current portfolio at least once a year by writing short summaries for each individual position.  14 of the 28 positions from last year are still in the portfolio and I have added 9 new positions. That tunover has been mainly driven by the events in 2022, which have changed fundamentals for quite a few of the old positions, but also opened up opportunities for new ones. A more comprehensive Performance review will follow in early January 2023.

A short user guide:

My style of investing mostly concentrates on 20-30 small/midcap stocks that in my opinion have a good return/risk profile over the next 3-5 years. Many of this stocks are not household names and are unlikely to make spectacular gains in a single year. Many of them look interesting only after the second or third glance. So if you are looking for a “Hot stock for 2023”, this post won’t help you much.

And always remember: THIS IS NOT INVESTMENT ADVICE. PLEASE DO YOUR OWN RESEARCH.

The summaries of the previous years can be found here:

My 28 Investments for 2022
My 21 (+6) Investments for 2021
My 20 investments for 2020
My 22(+1) Investments for 2019
My 21 investments for 2018
My 27 investments for 2017
My 27 investments for 2016
My 28 investments for 2015
My 24 investments for 2014
My 22 investments for 2013

Let’s go:

1. TFF Group (Portfolio weight 8,1%, Holding period 12,0 years)

Read more

Listed Venture Capital part 3 – The “Tale of the two Vostoks” & UK Vehicles

Background:

Back in the good old days (2018) when Venture and Growth investing were still sexy, I looked into the world of “listed Venture Capital”:

Part 1: HOW TO INVEST INTO VENTURE CAPITAL – LISTED VEHICLES (PART 1)
Part 2: HOW TO INVEST INTO VENTURE CAPITAL PART 2: AUGMENTUM, VOSTOK & OTHERS

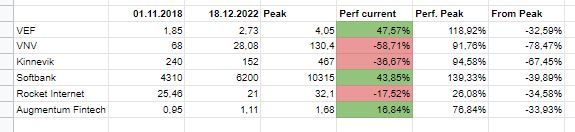
Inititally I bought into Kinnevik, Vostok New Ventures (renamed to VNV) and Vostok Emerging Finance (now VEF), however, I sold both Kinnevik and later VNV (at smallish profits) and only held onto VEF. This is how the Group has performed since then (november 2018) (Prices in local currency only, no dividends/Spin-offs):

Listed VC

Unfortunately I could not find continuous comparison charts for VNV and VEF, but almost all of the stocks at first struggled in 2019, only to go bonkers in late 2021 and then crumble in 2022.

Initially I cursed myself for selling too early , but now it looks super smart to only keep one that is a “winner”.

The tale of the two “Vostoks”: Why so different ?

Read more

« Older Entries Recent Entries »